Banking
CBN OMO Subscriptions Hit N20.6tn: How to Invest
CBN OMO subscriptions rose to N20.6tn in September 2026. Learn how to invest in OMO bills through your bank and what returns to expect.


CBN OMO subscriptions hit N20.6 trillion in September 2026, up from N18.72 trillion in August. That is a 10 per cent jump, or N1.88 trillion more, according to CBN data. If you have been watching from the sidelines, this is your signal to understand how OMO bills work and whether they fit your portfolio.
Here is a step-by-step guide to participating in CBN OMO auctions as an individual investor in Nigeria.
Step 1: Understand what OMO bills are
Open Market Operations bills are short-term instruments the CBN uses to manage liquidity in the banking system. When the CBN wants to absorb excess cash, it issues OMO bills. When it wants to inject liquidity, it buys securities.
In August 2026, the CBN widened access. A circular dated August 12, 2026, from Mr. Okey Umeano, Acting Director of the Financial Markets Department, allowed individuals, companies, and non-bank financial institutions to participate in both primary and secondary OMO markets through deposit money banks.
Before this, access was largely limited to banks and select institutions. Now you can join through your bank.
Step 2: Check current rates and auction schedules
At the September 24 auction, the stop rate on a 152-day OMO bill was about 17.29 per cent. That is the rate the CBN accepted for that tenor. Rates vary by tenor and auction.
So far in September, the CBN offered N3.9 trillion at OMO auctions, compared with N3.8 trillion in August. Successful bids totalled N12.82 trillion, up from N12.02 trillion in August. The numbers show demand is strong even after liquidity has been withdrawn from the system.
Step 3: Approach your bank
The CBN does not deal with individuals diretly for OMO bills. You must go through a deposit money bank. Ask your account officer for the OMO desk or the treasury department.
Tell them you want to participate in the next OMO auction. They will provide the application form and current auction details. Some banks require a minimum of N10 million or more for OMO participation. Others may have lower thresholds depending on their internal policies. Confirm the minimum with your bank before you commit.
Step 4: Submit your bid
You will bid for a specific tenor and amount. The CBN offers different tenors, such as the 152-day bill. Your bank will submit your bid to the CBN on your behalf.
If your bid is successful, the CBN allots you the bill at the stop rate. The stop rate is the highest rate the CBN accepts for that auction. If your bid is above the stop rate, it may be rejected.
Step 5: Fund your account and hold to maturity
Once allotted, your bank will debit your account for the amount you bid. The CBN holds the funds for the tenor. At maturity, you receive your principal plus interest.
For a 152-day bill at 17.29 per cent, a N1 million investment would yield roughly N72,000 in interest over the period, based on simple calculation. Your actual return depends on the rate you gett and the tenor.
Step 6: Consider the secondary market
The CBN now allows participation in the secondary OMO market through banks. This means you can buy and sell OMO bills before maturity. If you need your money earlier than the maturity date, you can sell in the secondary market, though the price may differ from your purchase price.
Common mistakes to avoid
Do not assume OMO rates are fixed. They change at every auction based on demand and CBN policy. The 17.29 per cent stop rate from September 24 is not guaranteed for future auctions.
Do not ignore the restriction on the Discount Window. The CBN removed certain restrictions that prevented banks participating in the Nigerian Foreign Exchange Market or purchasing government securities at primary auctions from accessing its Discount Window on the same day. However, the restriction on accessing the Discount Window and participating in an OMO auction on the same day remains. This affects banks more than individuals, but it shapes overall market liquidity.
Do not compare OMO returns directly with equities without adjusting for risk. Analysts said the wider access and attractive returns could intensify competition for funds between fixed-income instruments and equities. OMO bills are lower risk than stocks, but they also lack capital appreciation potential.
What the CBN is saying about rates
The CBN clarified that its recent adjustment of the Monetary Policy Rate was not an easing of monetary policy. The MPC cut the MPR by 350 basis points from 26.5 per cent to 23 per cent in September.
Mr. Mayokun Ajibade, Special Adviser to the CBN Governor on Financial Markets and Economic Policy, said the policy stance remains “very, very restrictive.” He explained that the move was a reset to close the gap between the benchmark rate and actual money-market conditions.
Ajibade noteed that while the MPR stood at 26.5 per cent, the SDF rate was around 22 per cent, and the market yield curve had already moved lower. The divergence sent mixed signals. The reset aims to align the official framework with market reality.
For OMO investors, this means rates may continue to adjust. Do not lock in based on a single auction result.
The result you want
If you follow these steps, you can add OMO bills to your fixed-income portfolio. You get a known tenor, a rate set at auction, and the backing of the CBN. For investors seeking naira-denominated returns with lower volatility than equities, OMO bills are worth considering.
The growth in CBN OMO subscriptions to N20.6 trillion shows that institutions and now individuals are taking advantage of the widened access. The N1.88 trillion increase from August to September signals strong demand.
Your first step today
Call your bank and ask for the OMO desk. Ask two questions: What is the minimum for OMO participation, and when is the next auction? That call costs you nothing and gives you the information you need to decide if OMO bills belong in your portfolio.
Frequently Asked Questions
Can individuals invest in CBN OMO bills directly?
No. Individuals must participate through deposit money banks. The CBN widened access in August 2026 to allow individuals, companies, and non-bank financial institutions to participate in primary and secondary OMO markets through banks.
What was the OMO stop rate in September 2026?
At the September 24, 2026 auction, the stop rate on a 152-day OMO bill was about 17.29 per cent. Rates vary by tenor and auction.
What is the minimum amount to invest in CBN OMO bills?
The minimum varies by bank. Some banks require N10 million or more, while others may have different thresholds. Confirm with your bank’s OMO desk before committing funds.
Related Articles

Banking
OPay Marks Eight Years in Nigeria: What Changed
OPay marks eight years in Nigeria with transfers, bills, cards and savings. Here’s what changed, what it costs you, and what to watch next.

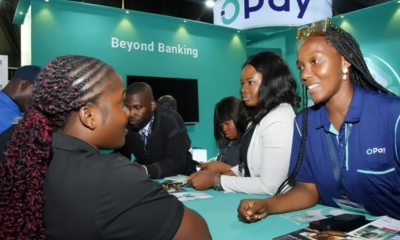
OPay marks eight years in Nigeria this year. It started in 2018 after the company acquired Paycom, a Central Bank of Nigeria-licensed Mobile Money Operator, and it now also holds a National MFB licence. In that time it moved from transfers and airtime to bill payments, cards, savings, merchant services and security tools.
If you use OPay, the practical question is not the anniversary. It is what the app actually does for your money today, where it still falls short, and what to watch next.
What OPay Actually Offers You After Eight Years
The app covers the basics most Nigerians touch weekly: transfers, airtime and data, bill payments, cards, savings and merchant collection. That list matters because it is the difference between a wallet you top up and a wallet you run your week from.
Mrs. Saliu Oluwabukola’s story is the common one. She downloaded the app in 2019, made a first transfer, then moved the money to her commercial bank account and was struck by how fast it landed. From there she added airtime, data and electricity bills.
She recalls electricity officials arriving to disconnect her property over an unpaid bill. With OPay she paid, sent the receipt, and closed the issue. “I trust OPay now with any amount,” she says.
Latifat Muftau’s case shows the same thing from the other direction. An ATM debited her without dispensing cash, and it was the only money she had. A neighbour showed her OPay. She registered with her phone number and received money almost immediately. “Money just entered. I was like, ah. This is easy.”
That speed is the product. Not the logo.
The Trend Behind the Anniversary
OPay’s growth tracks a wider shift in how Nigerians hold and move money. Smartphone adoption is a big part of it. Nigeria’s smartphone shipments surged 25 percent in the fourth quarter of 2025, according to Omdia research covered by BusinessDay.
Device financing did much of that work. Instead of paying full price upfront, buyers spread the cost through instalment plans from fintechs, mobile operators and retailers. Cheaper phones plus instalments equals more people able to run an app-based wallet.
That is the mechanism. A phone you can afford, a licence that lets a company hold and move your money, and a network of agents and merchants that makes the balance useful. Remove any one and the app becomes a place your money sits.
OPay’s own expansion follows the same logic. Transfers alone do not keep a user. Bills, cards, savings and merchant payments do, because each one gives you a reason to leave money in the app rather than sweep it out.
Who This Actually Helps, and Who It Doesn’t
The clearest winners are people the formal banking system served badly. Corps member Dahiru Haruna tried ORide in 2020 while travelling back to Lagos. The ride ended, the payment was deducted through OPay, and his reaction was: “Wow, we are progressing. Nigeria is moving with OPay.”
Small traders get the same benefit. A payment that lands instantly at a market stall is working capital. A bill paid from the same app is one less trip.
But be honest about the limits. OPay is not a bank, and the protections you get from a commercial bank are not identical. Your balance is not insured the way a deposit in a licensed deposit money bank is. For day-to-day spending money, that is a manageable trade-off. For your entire savings, think carefully.
There is also the cost question. OPay’s transfer and transaction fees are not disclosed in the source material for this article, so check the current fee schedule inside the app before you rely on it for large or frequent transfers. Fees on wallets change, and the number that applied last year may not apply now.
And watch the security basics. Keep your PIN to yourself, confirm the name on every transfer before you send, and treat any message asking you to re-register or verify your account through a link as suspect.
The Bigger Picture for Nigerian Fintech
OPay’s eight years sit inside a startup market that is still Nigeria’s strongest. Nigeria raised $254 million in startup funding in the first half of 2026, second only to Egypt’s $327 million, according to the Africa: The Big Deal report. On equity investment alone, Nigeria led with $214 million, ahead of Egypt’s $183 million.
Nigeria also leads Africa in the number of startups securing investment. That depth is why consumer fintech products keep launching here, and why the competition for your transaction is only getting harder.
That competition is good for you. It pushes down friction, forces better uptime, and makes customer support a selling point rather than an afterthought. OPay says it has kept investing in technology, customer support and security as more Nigerians adopt digital finance.
Outside the app, the company has committed ₦1.2 billion over 10 years to scholarships, alongside programmes in youth development, women’s empowerment and skills.
What to Watch Next
Three things will decide whether the next eight years look like the last eight.
First, whether wallet balances get stronger protection. If you are keeping real savings in an app, the rules around what happens if something goes wrong matter more than any cashback.
Second, pricing. As competition tightens, watch whether transfer and withdrawal fees fall or get bundled into other products. The current fee structure was not disclosed in the source material, so verify it yourself before you commit to a pattern of use.
Third, whether the app stays useful beyond payments. Savings, cards and merchant tools are where the relationship deepens. If those work well, the app becomes infrastructure. If they don’t, users will keep it for transfers and move their savings elsewhere.
For now, the honest summary is simple. OPay marks eight years in Nigeria as one of the apps that changed how ordinary people move money, pay bills and get paid. Use it for what it does well, keep your large balances where they are protected, and read the fees before you assume they are zero.
Frequently Asked Questions
Is OPay a bank in Nigeria?
No. OPay began in Nigeria in 2018 after acquiring Paycom, a Central Bank of Nigeria-licensed Mobile Money Operator, and it also holds a National MFB licence. That is not the same as a commercial bank licence, so the protection around your balance differs. Keep large savings in a licensed deposit money bank and use OPay for everyday transactions.
What can I do on OPay today?
Based on the company’s eight-year update, the app covers transfers, airtime and data, bill payments, cards, savings, merchant services and security features. It started as a payment app and expanded into a wider digital financial services platform.
Does OPay charge transfer fees?
The current fee schedule was not disclosed in the source material for this article. Check the fee page inside the app before you rely on it for frequent or large transfers, because wallet pricing changes and old numbers may no longer apply.
Related Articles
- OPay Investing in People to Build a Better Nigeria
- OPay No Dey Comot Nigeria: How to Verify Fintech News
-

 Startups3 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Trending Entertainment News7 days ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News3 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Fintech3 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News
-
Football3 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
Nigerian Business3 weeks ago
Moniepoint POS Network: How to Buy Dangote Shares
-
Fintech3 weeks ago
OPay Investing in People to Build a Better Nigeria
-
Black Celebrities3 weeks ago
Brandi Carlile: Rock Star in Her Prime, On Tour Now