Fintech
OPay Earns More From Lending Than Payments: What It Means for You
OPay earns more from lending than payments. Learn how this shift affects your wallet, your savings, and your loan options as a Nigerian user.

OPay earns more from lending than payments, and that changes how you should use the app. If you are one of the millions of Nigerians who open OPay for transfers, airtime, or bills, you are now using a lending company that happens to offer payments. That is not a bad thing. But it means your loan offers, your savings rates, and even your transaction limits are being shaped by a business that makes its real money when you borrow.
Here is how to read the shift, protect your wallet, and decide whether OPay’s credit products deserve a place in your financial life.
Why OPay’s Lending Business Matters To You
When a fintech makes more from lending than payments, it stops being a neutral pipe for your money. It becomes a bank in everything but name, minus the deposit insurance.
That matters because lending is where the profit is. Payment fees are thin. Interest on loans is fat. So the company’s incentives change: it wants you to borrow, repay on time, and borrow again.
For you, the upside is real. OPay and similar apps can offer small, fast loans that traditional banks will not give a trader in Onitsha or a salary earner in Ibadan. The downside is also real. Easy credit can trap you in a cycle of repayment that eats your monthly income.
Step 1: Check Your OPay Loan Offer Before You Tap It
Open the OPay app and look at the loan section. You will typically see a credit limit, a tenor, and a repayment amount. Before you accept, write down three numbers: how much you are borrowing, how much you will repay in total, and how many days you have.
If the total repayment is more than 20 percent above the principal for a 30-day loan, that is expensive money. Compare that to what a friend or a cooperative would charge you. If OPay is cheaper and you can repay from confirmed income, it can work. If you are borrowing to pay another loan, stop.
Step 2: Separate Your Payments Wallet From Your Borrowing Wallet
Use one OPay wallet for daily transactions and never keep a loan balance sitting there. If your loan disburses into the same wallet you use for transfers, you will spend it before the repayment date.
Move the loan money to the specific purpose immediately. Pay the supplier. Buy the stock. Settle the school fee. Then delete the temptation to redraw.
Step 3: Watch The Interest And Fees On Rollovers
Many digital lenders in Nigeria make their margin when you roll over a loan. The current rollover fee structure for OPay was not disclosed in the source material, so check your own app for the exact charge.
As a rule, if you roll over twice, you are likely paying more in fees than the original loan was worth. That is how people end up owing N80,000 on a N50,000 loan.
Step 4: Use OPay Savings Only For Short-Term Goals
OPay offers savings products, but remember that a lending-led business is not a licensed deposit bank in the same way your commercial bank is. Keep only money you will need within three to six months there. Your rent savings, your emergency fund, and your children’s school fees belong in a bank or a treasury bill.
The BNPL Warning Every OPay User Should Read
Buy now, pay later is growing fast. According to LendingTree, 35 percent of consumers were considering a BNPL loan in December 2024, and 47 percent of BNPL users had made a late payment. That is a warning, not a statistic.
OPay’s lending push follows the same playbook. Small loans feel painless until the repayment date. If you cannot pay cash for it today, a BNPL plan does not make it affordable. It makes it delayed.
What To Do When You Cannot Repay On Time
Call or chat with OPay support before the due date, not after. Ask for a restructuring or an extension in writing. Do not ignore the messages. Default on a digital loan can affect your ability to borrow elsewhere and may lead to aggressive recovery calls.
The student loan crisis in the United States, covered by PBS News, shows what happens when borrowers take on debt they cannot service. The lesson for Nigerians is simple: do not let a small loan become a long-term problem.
How To Compare OPay Loans With Other Options
Before you borrow, compare three things: total cost, speed, and flexibility. A bank overdraft may be cheaper but slower. A cooperative loan may be cheaper but requires savings history. A friend may be free but carries social risk.
OPay wins on speed and access. It rarely wins on price. Use it for emergencies and short gaps, not for funding a lifestyle.
A Simple Rule For Every OPay User
If OPay earns more from lending than payments, then your job is to make sure you earn more from using OPay than OPay earns from you. That means borrowing only when the return is clear, repaying early when you can, and keeping your savings where they are protected.
The first step to take today: open your OPay app, check your current loan offer and any active repayment, and write down the exact total cost. If it does not make sense, close the app and walk away. Your future self will thank you.
Frequently Asked Questions
Does OPay make more money from loans than from transfers?
Yes. OPay earns more from lending than payments, meaning interest and fees on loans now drive more revenue than transaction charges.
Are OPay loans safe to take?
OPay loans are safe if you can repay from confirmed income and the total cost is clear. Avoid rollovers, and never borrow to pay another loan.
Should I keep my savings in OPay?
Keep only short-term money in OPay savings. Long-term savings belong in a licensed bank or treasury bills for better protection.
Related Articles
- Fontaines D.C. Recruit Rosalía for ‘Where Is Gone?’
- Selma Blair Arrest: What Happened on Delta Flight 938
- 113 Million Nigerians Deprived of Health: What You Can Do
- Herbal Remedies: Aishat Alagbo’s Safe Use Guide
- 29MB AI Model Runs on a $10 Chip: Here’s How
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – OPay Earns More From Lending Than Payments: What It Means for You, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:





Fintech
OPay Files for $500M NYSE IPO: What Nigerian Investors Should Do
OPay files for $500m NYSE IPO and plans a secondary listing on NGX. Here’s what Nigerian investors should know and do next.

OPay files for $500m NYSE IPO, and that single filing changes how you should think about the fintech apps on your phone. The company wants to raise up to $500 million in the United States and has also secured board and shareholder approval to pursue a secondary listing on the Nigerian Exchange Limited (NGX).
This guide walks you through what the filing actually says, what it means for your money, and the concrete steps you can take now.
What The Filing Actually Says
OPay filed with the United States Securities and Exchange Commission (SEC) for an initial public offering estimated to raise up to $500 million, according to Independent Newspapers. The company plans to list on the NYSE under the ticker symbol OPAY.
The numbers behind the filing are the interesting part. First-half revenue more than doubled to $467.1 million, and net income rose to $90.9 million. For the 12 months ended June 30, 2026, OPay booked $806 million in revenue.
That is not small money for a company founded in 2017 in Singapore with its biggest market in Nigeria.
Where The Revenue Comes From
OPay does not make money from one source. It earns from transaction-based services (payments and acquiring), loan financing services (interest on self-originated loans), loan facilitation services (fees net of lender and insurance costs), and interest income from short-term investments supporting its savings products.
If you use OPay for transfers, savings, or loans, you are part of that revenue mix. The company also applies AI-driven risk analytics for fraud prevention and underwriting, which it cites as a key competitive strength.
How Big Is OPay In Nigeria
The filing states OPay was the number one finance app in Africa and the Middle East, with a 9.9 per cent market share based on monthly active users in the six months ended June 30, 2026. As of July 31, 2026, it was the country’s number two app across all categories based on daily active users.
Beyond Nigeria, OPay operates in Indonesia (loan facilitation), Egypt (merchant acquiring services), and Pakistan (merchant acquiring and consumer wallet services).
Step 1: Understand The Two Listings
There are two separate events here, and confusing them will cost you.
First is the primary listing on the NYSE. That is where the estimated $500 million raise happens. No pricing terms were disclosed, and the preliminary prospectus has not specified the offer price, number of securities to be sold, or expected proceeds.
Second is the secondary listing on the NGX. OPay obtained board and shareholder approval to pursue this after the NYSE listing completes, according to Nigeria Communications Week.
Step 2: Know What The NGX Listing Does Not Mean
The approval does not mean the Nigerian listing has been completed or that trading will begin immediately. OPay itself stated that the proposed Nigerian listing would depend on market conditions, regulatory approvals, and compliance with applicable Nigerian securities laws and NGX requirements.
The company has not disclosed the proposed size of the Nigerian offering or the percentage of its shares it intends to make available on the NGX. That matters because the scale of the opportunity for domestic investors depends on the number of shares available, the eventual pricing, the listing timetable, and the level of trading activity after admission.
Step 3: Watch The Valuation Gap
Reports surrounding the US IPO point to a valuation of approximately $4 billion. The joint bookrunners on the deal include Citi, Deutsche Bank, Standard Bank, and CICC. Other reporting names Citigroup, Deutsche Bank, and JPMorgan Chase as managing the US offering.
A $4 billion valuation on $806 million in trailing 12-month revenue is a specific multiple. Whether that holds at pricing depends on market conditions between now and the actual listing date.
Step 4: Decide How You Want Exposure
If you want OPay exposure, you have two potential routes.
Route one is buying OPAY shares on the NYSE after listing. That requires a broker with US market access, dollar funding, and tolerance for currency risk if you earn naira.
Route two is waiting for the NGX secondary listing. That keeps you in naira and inside a market you already understand. The trade-off is that you do not yet know how many shares will be available locally or at what price.
Step 5: Do Not Front-Run The Listing
There is no OPay stock to buy today. Anyone offering you pre-IPO OPay shares outside a registered platform is a red flag. The company has not priced the offering, and the preliminary prospectus has not specified the number of securities to be sold.
Mistakes To Avoid
Mistake one: assuming the NGX listing is guaranteed. OPay’s own filing cautions that even if the secondary listing proceeds, there is no guarantee it will generate an active trading market or achieve the anticipated expansion of its investor base and improvement in liquidity.
Mistake two: treating a $500 million raise as a $500 million valuation. Those are different numbers. The raise is the money coming in. The valuation is what the whole company is judged to be worth.
Mistake three: ignoring the concentration risk. OPay’s operations are heavily concentrated in Nigeria. That is a strength when Nigeria’s digital payments market grows and a vulnerability when regulation, currency, or consumer spending shifts.
Why This Matters Beyond OPay
The NGX has traditionally offered limited access to fast-growing private fintech companies. In August, Temi Popoola, chief executive of the Nigerian Exchange, urged the government to encourage major businesses generating substantial revenues in Nigeria to list locally, citing fintech companies including OPay and PalmPay.
The argument is straightforward: domestic investors should have an opportunity to participate in the financial value created by companies serving millions of Nigerians, rather than being excluded when those businesses seek public-market funding abroad. If OPay’s NGX listing proceeds, it could expand the range of technology-related investment opportunities on the exchange.
Your First Step Today
Open your broker app or call your stockbroker and ask two questions: do you offer access to NYSE-listed stocks, and will you support the OPay NGX listing when it opens? If the answer to both is no, start looking for a broker that does.
OPay files for $500m NYSE IPO, but the money decision is yours. Get your brokerage access sorted now, before the pricing terms drop and the queue forms.
Frequently Asked Questions
Can I buy OPay shares right now?
No. OPay has filed for an IPO but no pricing terms were disclosed. There is no OPAY stock trading yet on the NYSE or the NGX. Anyone offering you pre-IPO OPay shares outside a registered platform should be treated with suspicion.
When will OPay list on the Nigerian Exchange?
OPay has board and shareholder approval to pursue an NGX secondary listing after its NYSE primary listing, but no date has been disclosed. The company stated the listing depends on market conditions, regulatory approvals, and compliance with Nigerian securities laws and NGX requirements.
How much is OPay trying to raise?
The IPO is estimated to raise up to $500 million. Reports surrounding the US offering point to a target valuation of approximately $4 billion. The preliminary prospectus has not specified the offer price, number of securities to be sold, or expected proceeds.
Related Articles
- 113 Million Nigerians Deprived of Health: What You Can Do
- Herbal Remedies: Aishat Alagbo’s Safe Use Guide
- 29MB AI Model Runs on a $10 Chip: Here’s How
- Health Workers to Sue 20 Varsities Over Unpaid Allowance
- Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
Receive alerts for OPay files for $500m NYSE IPO and more like it.
FIRST TIME REACTIONS:
Be the first to leave us a comment – OPay Files for $500M NYSE IPO: What Nigerian Investors Should Do, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
Fintech
OPay Files for US IPO with 50 Million Users: What You Need to Know
OPay files for US IPO with 50.1 million monthly users and $806 million revenue. Learn what this means for Nigerian users and investors.
OPay has filed for a US initial public offering, and if you use the app for daily payments, savings, or credit, this is the moment to understand what changes and what stays the same.
The company filed a registration statement with the Securities and Exchange Commission for a proposed IPO. It reported 50.1 million monthly active users and revenue of $806 million for the 12 months ended June 30. Year-over-year revenue growth in the first half was 137%.
That is not small money. Here is how to read the move, what it means for your wallet, and what to watch before you get excited.
What OPay Actually Disclosed
OPay is a digital financial platform built for emerging markets. It offers consumer services from digital payments to savings, merchant tools for customer acquisition, acceptance and analytics, and credit services for both consumerrs and merchants. The credit side uses transaction data and artificial intelligence-powered credit decisioning.
The filing says the company sees an addressable opportunity across billions of users and millions of merchants. It operates in Nigeria, Egypt, Pakistan and Indonesia. The bulk of revenue comes from Nigeria, Africa’s most populous nation.
OPay plans to list on the New York Stock Exchange, with a later listing on the Nigerian Exchange. Citigroup Inc., Deutsche Bank AG and Standard Bank are working on the listing.
Why This Matters for Nigerian Users
If you send money, pay bills, or save on OPay, the IPO does not change your daily experience immediately. But it does change the company’s incentives.
Public companies answer to shareholders. That means more pressure to grow revenue, cut costs, and show consistent profit. For users, that can mean better products or higher fees, depending on how management plays it.
The filing says OPay aims to grow by expanding its range of products and services, continuing to invest in infrastructure that supports long-term scalability, and entering new markets where there is a clear, unmet need.
Translation: expect more features, more markets, and more competition with traditional banks.
The Standard Bank Deal
Before the IPO, OPay secured about $185 million in a private placement with Standard Bank Group Ltd., Africa’s biggest bank. The agreements include a stake sale through the private placement and Standard Bank’s Africa head, Lungisa Fuzile, serving on the board of directors.
The final size of the placement hinges on currency fluctuations. Standard Bank’s holding won’t exceed 4.99%.
OPay and Standard Bank plan to work on services includiing merchant acquisition, distribution of wealth products and foreign exchange. This is a non-binding memorandum between the parties.
What This Means for You: A bank and a fintech working together usually means more products in one place. It could also mean your OPay wallet becomes more integrated with traditional banking services.
How to Position Yourself as a User
Step 1: Know what you use OPay for. If it is only payments, the IPO is mostly noise. If you hold savings or use credit, pay attention to fee changes and terms.
Step 2: Watch for new product announcements. OPay said it will expand its range of products and services. New savings rates or credit terms could be better or worse than what you have now.
Step 3: Do not treat the IPO as a reason to change your habits. An IPO is a fundraising event for the company. It does not automatically make your wallet safer or your money more valuable.
Step 4: If you are considering buying the stock, remember that IPO shares are not available to everyone. You will likely need a broker with access to US markets. The filing does not disclose a share price range or the number of shares to be offered.
What the Numbers Say
Revenue of $806 million for the year through June is real. Growth of 137% year-over-year in the first half is strong. But the filing does not disclose profitability. That is a key detail missing from the public record.
Bloomberg reported in May that OPay was seeking a $4 billion valuation in its IPO. That would double the $2 billion valuation it achieved in a 2021 funding round led by SoftBank’s Vision Fund 2.
A $4 billion valuation on $806 million revenue is roughly 5 times sales. For a high-growth fintech, that is not crazy. But without profit numbers, it is hard to call it cheap or expensive.
Mistakes to Avoid
Do not assume the IPO means OPay is now safe as a bank. It is not a bank. It is a fintech. Your deposits are not covered by NDIC insurance the way bank deposits are.
Do not chase the IPO stock if you do not understand the b usiness. The filing is public. Read it. If you cannot explain how OPay makes money, do not buy the shares.
Do not ignore the risks. Currency fluctuations affect the Standard Bank placement. Regulatory changes in Nigeria, Egypt, Pakistan or Indonesia could hit revenue. Competition from other fintechs and banks is real.
What Happens Next
OPay’s planned stock-market debut adds to a growing pipeline of African financial-technology businesses going public. Airtel Money also listed on the London Stock Exchange at about $7 billion in value.
The company said in the filing: “OPay is uniquely positioned to capture this opportunity. As a comprehensive FinTech platform integrating payments, savings, credit and lifestyle solutions, OPay reimagines financial access through mobile-native, data-driven solutions designed to serve users across all socioeconomic segments.”
That is the pitch. Whether it works depends on execution, regulation, and how well OPay converts its 50.1 million users into profitable customers.
Your First Step Today
If you use OPay, open the app and check your current fees, savings rates, and any credit terms you have. Write them down. When the IPO closes and new products launch, compare. If you are an investor, read the SEC filing directly. Do not rely on headlines. The OPay files for US IPO story is a signal to pay closer attention to where your money sits and what it costs you.
Frequently Asked Questions
What does OPay filing for a US IPO mean for my OPay wallet?
In the short term, nothing changes. Your wallet, fees, and services stay the same. Over time, as a public company, OPay will face pressure to grow revenue, which could mean new products or fee changes. Watch for announcements.
Can Nigerians buy OPay shares when it lists on the NYSE?
You will likely need a broker with access to US markets. The filing does not dis,close a share price range or number of shares. The company also plans a later listing on the Nigerian Exchange, which may be easier for local investors.
Is OPay profitable?
The filing does not disclose profitability. It reported $806 million revenue for the 12 months ended June 30 and 137% year-over-year growth in the first half. Profit numbers were not included in the source material.
Related Articles
- Natanael Cano Postpones Mexico Tour: Refunds & Health Focus
- Quartz Countertops Banned in California: What You Must Know
- Pixel 11 owners still waiting on Android 17 QPR1
- Apple Watch and AirPods Fall Deals: Save $120 Today
- Prime Big Deal Days Fitness Deals: 50% Off Top Gear
FIRST TIME REACTIONS:
Be the first to leave us a comment – OPay Files for US IPO with 50 Million Users: What You Need to Know, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
Fintech
OPay Tackles Fraud With 5 Free Tools You Can Activate Today
OPay tackles fraud with free in-app tools: Emergency Lock, Night Guard, and more. Here is how to activate each one and protect your naira today.
You want your money to stay in your account. Not in a fraudster’s wallet. OPays tackles fraud with a set of free tools you can switch on yourself, and the company says its transaction fraud rate sits below 0.001 per cent. Here is how to use each one, what it actually does, and where the limits are.
Why This Matters Now
Nigeria moved from cash to digiital payments faster than almost anywhere in Africa. Mobile wallets now handle market purchases, bus fares, and supplier payments for small businesses. Criminals moved with the money. SIM-swap fraud, identity theft, account takeovers, and scam transfers are all live threats.
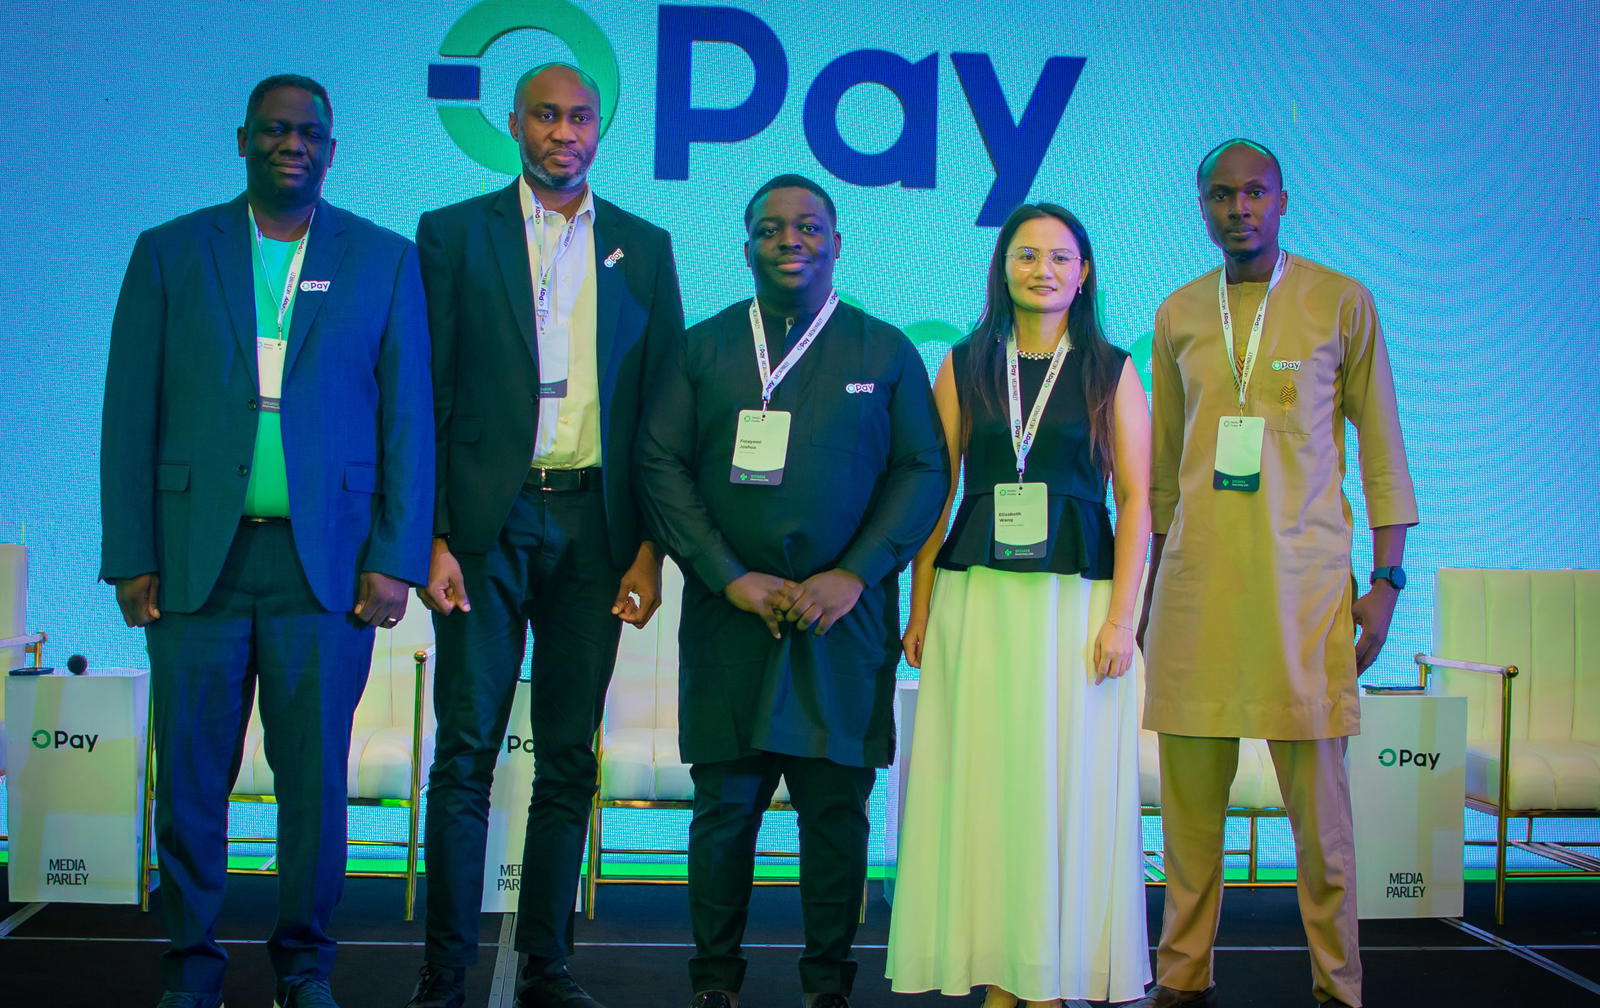
Elizabeth Wang, OPays Chief Commercial Officer, put the question bluntly at a Lagos media parley: consumers no longer judge platforms only by speed. They ask whether their money will remain safe. That is the shift.
OPay says it has blocked more than one million fake identities and runs over 5,000 monitoring and blocking rules with more than 10,000 risk-feature profiles. Its facial live-detection system blocks tens of thousands of attack attempts daily. But none of that helps you if you have not activated the customer-facing controls.
Step 1: Turn On Emergency Lock Before You Need It
Emergency Lock freezes your account instantly if your phone is lost, stolen, or you suspect someone has access.
The mistake most people make is waiting until the phone is already gone. Set it up now, while you can still log in. Know where it sits in your app menu before you need it in a panic.
Step 2: Activate Night Guard for Late Transfers
Night Guard requires facial verification for high-value transactions made late at night. Fraudsters target odd hours because victims are asleep and unlikely to notice alerts.
If you regularly send money at 2 a.m., expect a face scan. That is the point. Dotun Adekunle, OPay’s COO and CTO, described it simply: your face is the final lock on risky transactions, invisible when things are normal, immovable when they are not.
Step 3: Set Your Large Transaction Shield Limit
This one is personal. Large Transaction Shield lets you set your own threshold. Any transfer above it triggers extra verification.
Pick a number tha t matches your real spending. If your biggest monthly transfer is N200,000, a N500,000 limit gives you little protection. Set it lower. The friction is the feature.
Step 4: Let Anti-Scam Shield Work in the Background
Anti-Scam Shield uses machine learning and behavioral analytics to spot suspicious transfer patterns and block them before funds leave the network. You do not configure this one. It runs on its own.
Adekunle framed the logic: modern fraud prevention should happen before money leaves an account. AI and behavioural analysis catch patterns humans cannot see, in milliseconds.
Step 5: Save the USSD Codes on Any Phone
This is the step people skip, and it is the most useful when your phone is stolen. Dial 955131 to block your OPay account, or 955132 to block your card. Both work from any Nigerian phone line, not just your own.
Chukwudinma Okafor, OPay’s Chief Compliance Officer, confirmed these codes let customers stop transactions independently without contacting OPay first. If your phone and card are gone together, you do not need internet or app access to act.
What Happens When You Report Fraud
When you report an unauthorised transaction, OPay investigates jointly with the bank that received the funds. The company says it attempts to recover the money and takes punitive action against recipients of unauthorised transfers.
One honest caveat from Okarfor: a compliance alert does not automatically mean criminal activity. Flagged transactions are investigated, and alerts are closed when no suspicion is found. Do not assume a freeze equals an accusation.
How OPay Tackles Fraud Behind the Scenes
The customer-facing tools sit on top of a compliance system OPay says it spent three years building independently, with full intellectual property rights. It combines AI, big data, and real-time transaction monitoring to flag suspicious activity within milliseconds.
On identity, OPay integrates directly with issuers of identity documents to verify BVN and NIN data. Liveness checks confirm a real person, not a still image, is opening an account. KYC analysts review documents before approval.
Adekunle also noted that speed itself is a security feature. With 99.9 per cent of transactions completing successfully and average processing under one second, the window for doubt, disputes, and social engineering shrinks.
Mistakes That Cost Nigerians Money
First, ignoring alerts. If your bank or OPay messages you about a login you did not make, act immediately. Second, reusing one PIN across apps. Third, sharing your OTP with anyone who calls claiming to be support. No legitimate institution needs your OTP.
Fourth, keeping your Large Transaction Shield limit too high. 5th, not saving the USSD codes somewhere offline. The moment you need them is the moment you cannot search for them.
Where the Risk Still Lives
OPay’s controls only cover activity inside its network. Fraudsters increasingly target retail apps and stored card details on platforms with weaker security than banks, according to CNBC’s reporting on tap-to-pay fraud. If your card is saved in a shopping app, that is a separate door.
Okafor also flagged two industry-wide issues: greater regulatory scrutiny as fintechs become core payment channels, and the need to modernise anti-money-laundering systems as AI creates new risks. OPay says it engages the Central Bank of Nigeria and obtains approvals before launching new products.
The result you want is simple: a fraudster gets nothing, and you lose no sleep. You cannot control what criminals try. You can control whether Emergency Lock, Night Guard, Large Transaction Shield, and your USSD codes are active before they try.
Your First Step Today
Open your OPay app now. Activate Emergency Lock, set a realistic Large Transaction Shield limit, and save 955131 and 955132 in your phone contacts under a name you will find fast. That takes under 5 minutes. OPay tackles fraud with technology, but the last lock is you.
Frequently Asked Questions
How do I block my OPay account if my phone is stolen?
Dial 955131 from any Nigerian phone line to block your OPay account, or 955132 to block your card. These USSD codes work without internet or app access, so you do not need your stolen phone.
What is OPay Night Guard and when does it trigger?
Night Guard requires facial verification for high-value transactions made late at night. Fraudsters target odd hours because victims are asleep, so the extra face scan adds a lock when risk is highest.
Does a compliance alert on my OPay account mean I am accused of fraud?
No. OPay’s Chief Compliance Officer Chukwudinma Okafor stated that a compliance alert does not immediately imply a transaction is linked to criminal activity. Flagged transactions are investigated, and alerts are closed when no suspicion is found.
What is OPay’s transaction fraud rate?
OPay says its controls have kept its transaction fraud rate below 0.001 per cent, supported by more than 5,000 monitoring and blocking rules and over 10,000 risk-feature profiles.
Related Articles
- Best iPhone 18 Pro Cases: 5 Picks Under $30 Tested
- Nigeria’s Economy Grows Over 4% in 2026: What It Means for You
- Shot on iPhone Duo Campaign: What Apple Isn’t Telling You
- Trump $500 Check Hits Mailboxes: Who Qualifies
- Honda Labour Dispute: What Nigerian Car Owners Must Know
FIRST TIME REACTIONS:
Be the first to leave us a comment – OPay Tackles Fraud With 5 Free Tools You Can Activate Today, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
-

 Trending Entertainment News4 days ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News3 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Startups3 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Nigerian Business2 weeks ago
Moniepoint POS Network: How to Buy Dangote Shares
-
Fintech3 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News
-
Fintech3 weeks ago
OPay Investing in People to Build a Better Nigeria
-
Football3 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
Black Celebrities3 weeks ago
Brandi Carlile: Rock Star in Her Prime, On Tour Now