Savings & Investing
Global X Russell 2000 Covered Call ETF Declares $0.21
Global X Russell 2000 Covered Call ETF declares CAD $0.21 per unit for an Oct 30 record date. What the filing says — and what it does not.


Global X Investments Canada Inc. put a number on the table: CAD $0.21000 per security for the Global X Russell 2000 Covered Call ETF, ticker RSCC on CBOE. The ex-date and record date are 30 October 2026. The pay date is 6 November 2026. Holders take cash, or reinvested units if they are enrolled in the fund’s distribution reinvestment plan.
The number is precise. Its meaning is narrower than it looks.
A distribution declaration is an administrative event. It tells a holder how much cash leaves the fund per unit on a set date. It says nothing about whether the fund made money, nothing about the yield a new buyer would earn over the next twelve months, and nothing about the direction of the unit price.
Nothing moved on this news, and that is the correct reaction. The same October 2026 notice carries dozens of tickers, many declaring identical amounts on identical dates across monthly and semi-monthly schedules. It is a calendar release, not a market event.
Why the Global X Russell 2000 Covered Call ETF Payout Is Not a Yield
RSCC sits inside a suite that Global X markets as solutions for a range of market conditions. The mechanical part is the covered call structure. The fund holds a portfolio tied to the Russell 2000 small-cap universe and writes call options against it. Option premiums arrive as cash. In exchange, the fund surrenders part of the upside when small caps rally hard.
That trade has a signature. Income is steadier than the underlying index. Appreciation is capped in strong markets. Downside is not removed — a fall in small caps still flows into the unit price, less whatever premium was collected.
When the ex-date passes, the distribution is typically reflected as a reduction in net asset value per unit. A holder who receives CAD $0.21000 and watches the price fall by a comparable amount has gained nothing that day. Total return, price change plus distributions, is the measure that matters. The notice does not supply it.
The filing also discloses no net asset value, no assets under management for this specific fund, and no yield figure. Anyone quoting a yield from this press release is calculating it off an outside price source, not off the filing.
Why the Enhanced Line Pays More Per Unit
The same table carries RSCL, the Global X Enhanced Russell 2000 Covered Call ETF, at CAD $0.34000 per security, on the same dates and the same exchange.
The higher figure invites an obvious but wrong conclusion: that the enhanced version is the better product. Global X’s own cautionary language covers the gap. The company states that certain funds may use leveraged investment techniques that magnify gains and losses, producing greater volatility, and that those risks are described in the prospectus.
Leverage applied to a covered call strategy on small-cap equities does two things at once. It lifts the cash distribution per unit. It also enlarges the drawdown when the trade turns. The distance between $0.34 and $0.21 is compensation for risk, not a free upgrade.
Two further details sit in the filing. Global X states plainly that distributions for the ETFs will vary from period to period. And the table lists both RSCC and its RSCC.U line at CAD $0.21000, with currency shown as CAD on both rows — a designation holders should confirm against the fund’s own documents before assuming what settles in the account.
What the Filing Leaves Out, and Where Nigeria Fits
Two structural differences separate a Canadian listed fund from what a Lagos-based investor can reach.
The first is product availability. The Nigerian Exchange listed ETF range remains built around index trackers and commodity funds. A covered call wrapper, which depends on a functioning listed options market underneath it, is not part of that line-up. A Nigerian investor seeking this exposure is buying a foreign-listed security, which brings a brokerage with CBOE access, foreign currency funding, and the naira-to-funding-currency spread into the return calculation.
The second is currency. These distributions are declared in CAD. Naira outcomes depend on the exchange rate on the conversion date, and that rate can move further in a month than a monthly distribution pays.
Minimum investment amounts follow from the same set of facts. The notice gives no unit price, so the cash outlay for a single unit cannot be computed from the release. One unit is the practical minimum on an exchange, and a reinvestment plan only helps holders who already own enough for it to matter. For a Nigerian buyer, the effective minimum is set as much by brokerage floors and conversion costs as by the unit price. Small positions get eaten by friction before they compound.
Scale is worth noting but proves nothing about safety. Global X reports more than $55 billion in assets under management and more than 160 ETFs listed on major Canadian exchanges, and is a wholly-owned subsidiary of Mirae Asset Financial Group, which manages over $1 trillion across 21 countries. Size does not underwrite a small-cap option overlay.
The Dates That Actually Bind
Trading on or after the ex-date of 30 October 2026 does not carry the October distribution. Payment follows on 6 November. The November declaration, the next real data point, is not in this release.
For a holder, the framework is rolling. A monthly distribution means monthly re-pricing of income. One CAD $0.21000 figure says nothing about twelve months of cash flow, which is why the variation clause carries more weight than the headline number.
Investor Takeaway
The Global X Russell 2000 Covered Call ETF declaration is verifiable and specific: CAD $0.21000 per unit, ex-date 30 October 2026, pay date 6 November 2026, CBOE. Everything an investor actually needs — yield, NAV behaviour, total return, the effect of the option overlay on a small-cap drawdown — sits outside the notice, in the prospectus and the fund’s financial reporting. Treat the announcement as a calendar entry. Size positions against total return rather than against the distribution, and read the $0.21 and the $0.34 as amounts declared for one period, not promises about the next.
Nothing here is personalized financial advice. Global X states that the funds are not guaranteed, their values change frequently, and past performance may not be repeated. Covered call and leveraged strategies can lose money.
Frequently Asked Questions About Global X Russell 2000 Covered Call ETF
How much is the Global X Russell 2000 Covered Call ETF distribution for October 2026?
The notice declares CAD $0.21000 per security for RSCC, with an ex-date and record date of 30 October 2026 and a pay date of 6 November 2026. Payment is in cash, or reinvested units for holders enrolled in the fund’s distribution reinvestment plan.
Is RSCL the same fund as RSCC?
No. RSCL is the Global X Enhanced Russell 2000 Covered Call ETF, declared at CAD $0.34000 per security on the same ex-date and pay date. Global X states that certain funds may use leveraged investment techniques that magnify gains and losses, which increases volatility. The higher distribution per unit is not evidence of a better return.
Does the distribution notice tell me the fund’s yield?
No. The release discloses the cash amount per security, the ex-date and record date, the pay date, the currency and the exchange. It does not state the fund’s net asset value, its assets under management, or a yield. Global X notes that distributions will vary from period to period, so a single month cannot be annualised into a reliable income figure.
Can a Nigerian investor buy this ETF directly on the NGX?
No. The security is listed on CBOE in Canada. Reaching it from Nigeria requires a brokerage with access to that exchange plus foreign currency funding, which introduces conversion costs and exchange-rate risk into the return. A covered call structure of this kind is not part of the Nigerian Exchange’s listed ETF range.
Receive alerts for Global X Russell 2000 Covered Call ETF and more like it.
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – Global X Russell 2000 Covered Call ETF Declares $0.21, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:

About Paul Nwogo
Paul Nwogo is an engineer, published author, and the Head Manager at AfriLatest. He has written numerous books available on Amazon covering a diverse range of topics, including health, personal finance, relationships, work ethics, and scam survival. With his technical background and passion for writing, Paul now oversees the editorial direction of AfriLatest, delivering practical, accurate, and engaging content on trending news, music, and global lifestyle topics.
View all articles by Paul Nwogo

Savings & Investing
PiggyVest Shifts Focus to Income Growth as Inflation Bites
PiggyVest shifts focus to income growth as inflation hits savings. Learn how to earn more, invest smarter, and protect your naira.
You want your money to grow, not shrink. But with inflation at 15.91% in June 2026, every naira you keep in a traditional savings account is losing value. That’s why PiggyVest shifts focus to income growth as inflation hits savings. The company announced this at its 2026 Open House in Lagos, themed ‘The Future of Wealth is Here’. Co-founder Joshua Chibueze said user numbers are still rising, but the rate at which customers save is falling. The fix? Help you earn more.
This guide shows you how to follow PiggyVest’s ne w direction. You’ll learn why saving alone won’t cut it, how to boost your incom, and the mistakes to avoid. By the end, you’ll have a clear plan to protect your naira and grow your wealth.
Why PiggyVest Shifts Focus to Income Growth (And Why You Should Too)
Saviing becomes harder when your disposable income is squeezed. Chibueze said exactly that: “Saving becomes more difficult when disposable income is under pressure.” PiggyVest’s own savings report found that only 6% of respondents were satisfied with their financial situation. That’s a shocking number.
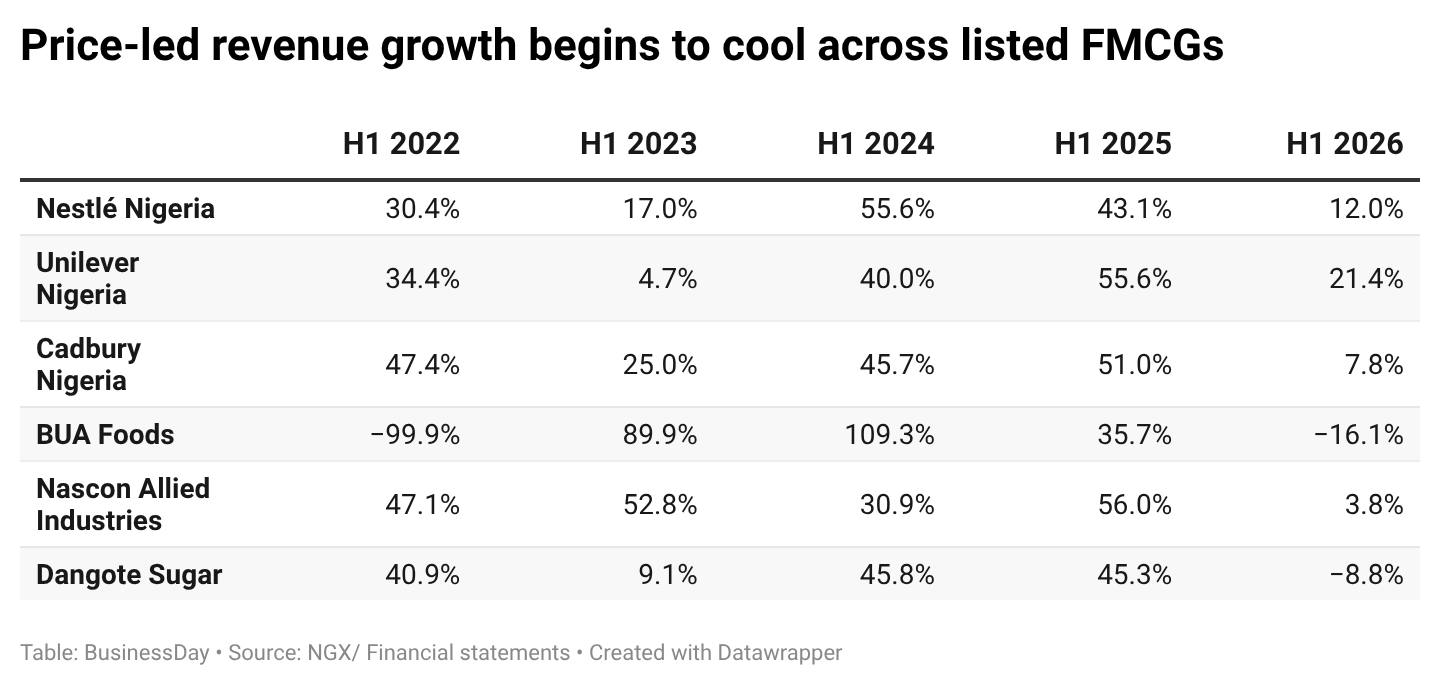
Inflation is the culprit. At 15.91% year-on-year in June 2026, prices are still rising, though slower than the 22.2% in July 2025. According to BusinessDay, consumer goods companies are losing pricing power as inflation eases. But for you, the damage is done: your salary buys less.
If you keep N100,000 in a savings account earning 4% interest, you’re losing about 12% in real terms every year. That’s N12,000 gone. No wonder only 6% are satisfied. The solution isn’t to save harder; it’s to earn more.
Step 1: Track Your Income and Expenses Honestly
You can’t grow what you don’t measure. for one month, write down every naira that comes in and goes out. Use a notebook or a free app. Most people underestimate their spending by 20-30%.
Look for leaks: unused subscriptions, impulse buys, transport you could avoid. But don’t just cut. The goal is to see how much room you have to invest in income-generating activities.
Step 2: Build an Emergency Fund First
Before you chase income growth, secure a base. PiggyVest co-founder Odunayo Eweniyi urged Nigerians to save consistently, regardless of the amount. Aim for at least three months of living expenses in a easy-to-access savings account.
If you spend N150,000 monthly, that’s N450,000. Yes, it’s a lot. But it stops you from dipping into investments when life happens. Start small: N10,000 weekly. In 45 weeks, you’re there.
Step 3: Use PiggyVest’s New Tools to Invest in Income-Generating Assets
PiggyVest CEO Somtochukwu Ifezue said the company rebuilt its app with new features: joint accounts, children’s accounts, and a revamped investment offering. The platform now lets you invest in commercial papers and debt notes issued by local companies. These are not hype; they’re real instruments.
Commercial papers are short-term loans companies use to fund operations. They typically offer higher returns than savings accounts. But they carry risk: if the company defaults, you could lose money. Only invest what you can afford to lose.
According to FSDH Asset Management, mutual fuds offer structured risk management and often inflation-beating returns. PiggyVest’s investment products are a step in that direction, but they are not a magic bullet. Do your research.
Step 4: Increase Your Earning Capacity
PiggyVest’s new focus is on connecting users to opportunities that improve earnings. That means you need to actively seek higher income. Here’s how:
– Ask for a raise. If you haven’t had one in 12 months, prepare a case. Show your value. Inflation means your real pay has dropped.
– Start a side hustle. Use skills you already have: writing, design, tutoring, coding. Even N50,000 extra monthly can change your savings game.
– Sell unused items. That old phone, clothes, or furniture can become cash.
– Learn a high-income skill. Digital marketing, data analysis, or project management. Free resources exist on YouTube and Coursera.
Remember, income growth isn’t about overnight riches. It’s about consistent effort. Chibueze said PiggyVest will increase financial education and expose users to opportunities. Take advantage.
Step 5: Automate Your Savings and Investments
Willpower fails. Automation works. Set up autopmatic transfers from your salary account to PiggyVest on payday. Even N5,000 weekly adds up to N260,000 in a year, plus interest.
For investments, use PiggyVest’s revamped platform to schedule recurring buys into commercial papers or other instruments. This removes emotion and builds discipline.
Common Mistakes to Avoid
– Saving without investing. Inflation will eat your savings. You need returns above 15.91% to break even. Most savings accounts pay 4-6%.
– **Chasing high returns without understanding risk.** Commercial papers and debt notes are not risk-free. Read the fine print.
– Ignoring small amounts. Eweniyi said to save consistently, regardless of amount. N1,000 weekly is better than nothing.
– Not tracking progress. Review your net worth quarterly. Adjust as needed.
The Result: A Clearer Path to Wealth
When you follow these steps, you stop being a passive saver and become an active wealth builder. PiggyVest shifts focus to income growth because it knows savings alone can’t outpace inflation. You should do the same.
Start by tracking your expenses this week. Then open a PiggyVest account if you don’t have one, and explore the investment options. Set a goal: increase your income by 20% in six months. It’s possible.
Inflation will not wait. Your naira loses value every day. But with the right actions, you can protect it and grow it. PiggyVest shifts focus to income growth as inflation hits savings. Now it’s your turn.
Your first step today: write down one way you can earn an extra N20,000 this month. Then take action.
Frequently Asked Questions
What is PiggyVest’s new focus?
PiggyVest is shifting focus to income growth, helping users increase their earning capacity as inflation makes saving harder. They announced this at their 2026 Open House.
Why is saving alone not enough in Nigeria?
With inflation at 15.91% (June 2026), savings accounts paying 4-6% interest lose value in real terms. You need investments that beat inflation.
What investmeent options does PiggyVest now offer?
PiggyVest has revamped its investment offering to include commercial papers and debt notes issued by local companies. These carry risk, so invest wisely.
Related Articles
- Tecno Camon 50 Ultra vs Camon 50 Pro: Full Review
- Gabriel Ezenri Foundation Scholarship 2026 Guide for Nigerian Students
- Tecno Camon 50 Review: 5G Power at a Mid-Range Price
- Iran Insists on Diplomatic Solution After Trump Rejects Peace Plan
- iPhone 18 Pro Review: Worth the Upgrade?
-

 Startups4 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Health and Fitness1 week ago
Curly Hair Hydration: 5 Proven Steps That Actually Work
-
Trending Entertainment News2 weeks ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News4 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Tech & Gadgets2 weeks ago
Apple Watch and AirPods Fall Deals: Save $120 Today
-
Football4 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
University Admissions4 weeks ago
UNILAG 2026/2027 Admission: Direct Entry & Post-UTME Guide
-
Fintech4 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News