Insurance today
Car Insurance Myths: 4.5M Drivers Risk Fines
Car insurance myths cost drivers real money. 4.5M UK drivers risk fines believing comprehensive covers any car. Here’s the truth.


Car insurance myths are not harmless trivia. They are the reason 4.5 million UK drivers got behind the wheel of a car they did not own without checking whether their policy actually covered them, according to research by Tempcover. Nearly four in 10 motorists still believe their comprehensive insurance automatically lets them drive someone else’s car. It does not.
That single misunderstanding has turned borrowed cars into a legal trap. Here is what the data actually says, which tools fix the problem, and how to avoid becoming what Tempcover calls the Accidental Outlaw.
What The Driving Other Cars Myth Gets Wrong
The Driving Other Cars (DOC) extension was once a common feature of fully comprehensive policies. Insurers started phasing it out as standard around 2005, with Norwich Union, RAC, and Asda among the first to drop it.
Today, 51% of UK motorists still think comprehensive cover lets them drive any car, according to research from short-term insurer Dayinsure. The Tempcover study found 47% of drivers believe the DOC extension still exists.
Here is the reality. Most comprehensive policies only cover the vehicle named on the policy unless a specific DOC extension is included. Even where DOC cover exists, it is typically limited to third-party protection only. That means damage to the borrowed car may not be covered at all.
Chris Bibby, CEO of Dayinsure, put it plainly: many people only discover they are not covered after police stop them or after an accident.
How To Check If You Are Actually Covered
Step one: read your insurance certificate and policy wording. Not the summary email. The actual document.
Step two: search for the phrase Driving Other Cars. If it is not specifically listed, assume you are not insured to drive another vehicle.
Step three: if you borrow a car regularly, buy standalone temporary car insurance. Tempcover’s Jake Lambert notes this can be arranged in minutes and ensures legal cover for the journey.
Step four: if your car has already been seized, a standard policy will not get it back. More than a quarter of motorists wrongly believe it will. Release from a police compound requires specialist impound insurance.
The Costs Of Getting This Wrong
Driving without insurance carries an automatic fixed penalty of £300 and six penalty points. Police can seize and impound the vehicle on the spot.
Initial release fees run £160 to £200, and daily storage charges exceed £20. More than a third of drivers do not know about the release fee. Nearly half are unaware of the storage charges.
The wider picture is worse. The Motor Insurers’ Bureau estimates 300,000 uninsured vehicles are on UK roads every day, costing the economy £1 billion annually. Last year, police seized nearly 160,000 vehicles, the highest figure in 17 years. Someone is affected by an uninsured or hit-and-run driver every 20 minutes.
Fronting: The Myth That Becomes Fraud
Nearly one in three drivers, and almost half of Gen Z drivers, believe it is legal to list a parent as the main driver of a car primarily used by their child.
This is called fronting. It is insurance fraud. It invalidates the policy and can result in an IN10 conviction, policy cancellation, and full personal liability in a collision.
There is no emergency exemption either. Among Gen Z drivers, 69% believe genuine emergencies should exempt motorists from insurance penalties. No such exemption exists under the Road Traffic Act.
What California And Ethanol Tell Us About Insurance Myths
The problem is not uniquely British. In California, auto insurance premiums rank among the highest in the nation, yet many residents still assume insurance issues only matter to homeowners.
According to CalMatters, about 44% of the state’s residents do not own their homes. But everyone who wants to drive is legally required to have insurance. The health of the insurance market affects whether people can drive to work at all.
Another myth travels faster than facts: that using E20 ethanol-blended petrol could invalidate vehicle insurance. India’s Ministry of Petroleum and Natural Gas debunked this directly, stating that consumers using E20 fuel have no reason to fear adverse insurance consequences because of ethanol blending. Brazil uses E27 as standard, a higher blend than India’s E20.
The pattern repeats everywhere. Viral claims about insurance spread faster than policy documents get read.
Which Tools Actually Solve This
Tempcover and Dayinsure both sell standalone temporary car insurance. You enter the vehicle registration, your details, and the cover period. Policies can be arranged in minutes.
This is the practical fix for borrowing a friend’s car, sharing holiday driving, or running an errand in a partner’s vehicle. The Tempcover study found 44% of drivers used a vehicle they did not own in the past year, with 23% doing so every week.
Reasons included errands (13%), emergencies (11%), and sharing holiday driving (10%). Motorists most often borrowed from friends (33%), partners (24%), or parents (11%).
For impounded vehicles, you need specialist impound insurance, not a standard policy. That distinction matters because 28% of motorists get it wrong.
Who Should Use This And Who Should Not
If you borrow a car even occasionally, buy temporary cover before you drive. It takes minutes and costs far less than a £300 fine plus six points.
If you own a car and never drive anyone else’s, you do not need temporary insurance. But you should still check whether your policy includes a DOC extension, because 51% of drivers assume it does when it often does not.
If you are a parent thinking about listing yourself as the main driver on your child’s car, do not. That is fronting, and it is fraud.
The truth about car insurance myths is simple: the policy document is the only source that matters. Read it before you drive, not after you are stopped.
Frequently Asked Questions
Does comprehensive car insurance let me drive any car?
No. Most comprehensive policies only cover the vehicle named on the policy unless a specific Driving Other Cars extension is included. Even where DOC cover exists, it is usually third-party only, so damage to the borrowed car may not be covered.
What happens if I drive without insurance in the UK?
Driving without insurance carries an automatic fixed penalty of £300 and six penalty points. Police can seize and impound the vehicle on the spot. Release fees run £160 to £200, plus daily storage charges over £20.
Is fronting car insurance legal?
No. Fronting is insurance fraud. Listing a parent as the main driver of a car primarily used by their child invalidates the policy and can lead to an IN10 conviction, policy cancellation, and full personal liability in a collision.
Related Articles
- Nigeria US Health Compact: 5 Steps to Demand Transparency
- Deli Meat Health Risks: How to Limit It to Once a Week
- The Cold Song: Nordic Noir Gets an Emotional Twist
- AI in Africa: 5 Takeaways From the 11th Nigeria Innovation Summit
- Herbal Remedies: Aishat Alagbo’s Safety Warning for Nigerians
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – Car Insurance Myths: 4.5M Drivers Risk Fines, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:

Insurance today
10 Insurance Simulation Examples You Can Run Today
Insurance simulation examples you can use today: how GM, Allstate, Covered California and others test risk with AI, quantum and synthetic drivers.
You want to test a risk model without waiting three years for real-world claims data to catch up. Insurance simulation is how you do it. The technique is already running inside carmakers, health exchanges, and quantum labs. Here are 10 working examples you can copy or adapt, drawn from documented deployments.
Before You Start: What You Need
You need three things. First, a data source that represents the risk you care about: telematics, claims history, census data, or synthetic scenarios. Second, a compute environment. A laptop handles small Monte Carlo runs; rack-scale GPU systems handle the heavy versions. Third, a validation loop. Every example below pairs simulation with a real-world check, because a simulated result nobody verifies is just a guess.
If you are building on NVIDIA infrastructure, note that cuDF and cuVS now accelerate structured and unstructured data pipelines for platforms including Apache Spark, Presto, DuckDB, Polars, and Velox, with up to 5x faster processing than CPU-only deployments, according to NVIDIA. That matters because most insurance simulation work stalls on data prep, not math.
10 Insurance Simulation Examples You Can Use
1. Driver Attention Testing With Candy Crush
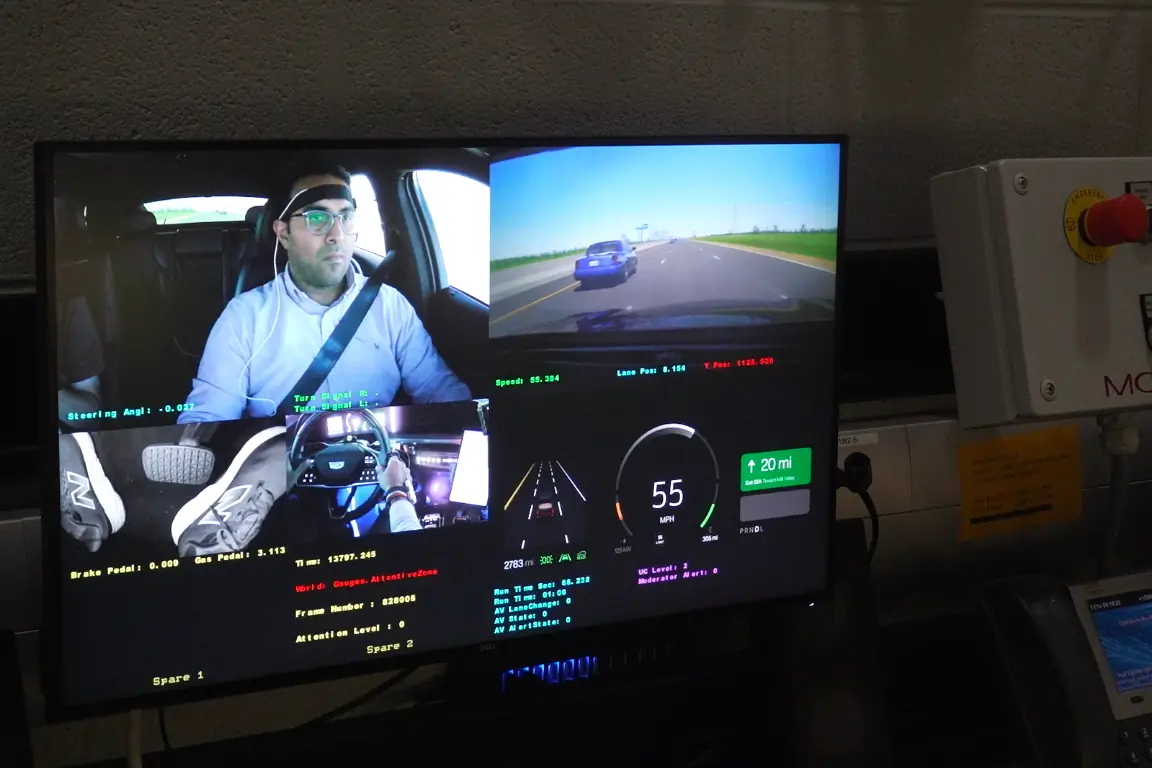
General Motors runs hundreds of volunteer drivers inside a 360-degree simulator at its Global Technical Center in Warren, Michigan. Participants sit in a real Cadillac Lyriq or other GM model while the world outside is computer-generated. GM measures heart rate, stress, sweating, and eye movement from a nearby control room.
The clever part: GM asks drivers to play Candy Crush on a tablet mounted in the cabin. It is a controlled distraction that tells researchers how long it takes a person to disengage and re-engage with the road. If you are testing any human-in-the-loop system, steal this. Pick a task people actually want to finish, then measure the handoff time.
2. Scenario Libraries For Unexpected Road Events
GM’s simulator throws in a dog, deer, or child sprinting onto the road, plus construction zones and detours that navigation apps have not flagged. Maureen August, senior manager at GM Research & Development, said the goal is to take anything customers could experience on the road.
Build the same library for your own risk model. List the 50 events that would hurt you most, then simulate each one a thousand times. The value is in the tail, not the average.
3. Eyes-Off Readiness Testing
GM plans to launch its next Super Cruise on the Cadillac Escalade IQ by 2028, moving from hands-free to eyes-off driving. The company has sold Super Cruise since 2017 across more than 630,000 roads in the U.S. and Canada, with over 20 models across Cadillac, GMC, Buick, and Chevrolet.
For insurers, this is a product question: what does liability look like when the driver is watching a movie? Simulation lets you price that transition before regulators finish writing rules. Telemetry’s Sam Abuelsamid noted there is little real regulation governing these systems today, and automakers are going state by state for approvals.
4. Hands-Off Comparison Baselines
Ford’s BlueCruise is available on more than 130,000 miles of certain North American roads. Tesla labels its system Full Self-Driving but still requires human oversight. Running the same simulated scenario across these systems gives you a comparison baseline.
If you underwrite auto risk, this is how you build differentiated pricing by ADAS capability instead of treating every car with lane-centering as identical.
5. Quantum Underwriting For Correlated Risk
Allstate uses quantum computing for stochastic optimization in underwriting. Eric Huls, chief analytics and data officer, said classical methods struggle with highly correlated, large-scale decisions, while quantum allows the company to address the joint decision space more directly.
For a provider underwriting more than 7 million homes, small accuracy gains compound. Allstate is still breaking problems into pieces to fit current hardware, but the direction is clear. Details of the full production stack were not fully confirmed.
6. Protein And Molecular Simulation For Life Risk
Cleveland Clinic, RIKEN, and IBM simulated protein complexes spanning up to 12,635 atoms using IBM quantum computers plus the Fugaku and Miyabi-G supercomputers. This is a hybrid quantum-classical approach.
Life and health insurers care because drug development usually takes more than 10 years. If simulation shortens that, morbidity assumptions shift. Gartner’s report on the breakthrough noted it could accelerate time-to-market for biopharma.
7. Materials Corrosion Modeling
Boeing is developing corrosion-resistant materials and coatings with quantum methods. Marna Kagele, a technical fellow at Boeing, said an estimated $20 billion is spent annually on corrosion mitigation or prevention.
Property insurers with industrial books can use the same modeling to refine wear-and-tear assumptions on commercial buildings, pipelines, and infrastructure.
8. Portfolio And Asset Risk Simulation
At IBM Think 2026, Vanguard presented portfolio optimization for fixed-income assets, HSBC covered trade execution for corporate bonds, and E.ON worked on decentralized energy system optimization. Moderna used quantum optimization to predict mRNA secondary structures.
Insurers hold large fixed-income portfolios. Any of these workflows can be adapted to test duration risk, liquidity stress, or counterparty exposure under conditions your historical data has never seen.
9. Health Coverage Take-Up Modeling
Covered California uses the California Simulation of Insurance Markets (CalSIM) model, developed by UCLA’s Center for Health Policy Research. It estimates that nearly 1.2 million Californians remain uninsured and eligible for coverage in 2026, split between 508,000 eligible for Covered California subsidies and 682,000 for Medi-Cal.
The model also breaks down who they are: among the 508,000, 57 percent are Latino and 50 percent are between 45 and 64. That is insurance simulation doing enrollment targeting, not just pricing.
10. Catastrophe And Geopolitical Shock Modeling
Bloomberg Economics modeled five Taiwan Strait scenarios. In the most extreme, a US-China conflict would cost the global economy about $10.6 trillion in the first year, roughly 9.6 percent of global GDP. Taiwan makes 62 percent of the world’s most advanced logic semiconductors, and TSMC accounts for 70 percent of global foundry revenue.
For insurers, this is a supply-chain and business-interruption stress test. Run your book against a scenario where semiconductor access stops for 12 months. Most carriers have not.
How To Run Your First Simulation This Week
Pick one risk you already track. Define 20 scenarios, including three that have never happened to you. Pull your data into a GPU-accelerated pipeline if volume is the bottleneck. Run the scenarios, then compare outputs against your last 24 months of actual claims.
The gap between simulated and actual is your model error. That number is more useful than any single scenario result.
One practical note: Snap cut daily data processing costs by 76 percent using NVIDIA cuDF on Google Kubernetes Engine, analyzing 10 petabytes within a three-hour window. You do not need that scale to start, but the cost curve is real.
What To Try Next
Start with example one. Build a distraction test for whatever human decision sits inside your process, whether that is a claims adjuster, an underwriter, or a driver. Measure the handoff time. Then expand to example ten and stress your book against a shock you have never priced.
Insurance simulation is not a research project anymore. GM, Allstate, Covered California, and Boeing are all running it in production or close to it. The teams that build scenario libraries now will price risk better than the teams still waiting for enough historical data.
Frequently Asked Questions
What is insurance simulation in simple terms?
It is using computer-generated scenarios, real driver or customer behavior, and measured data to test how a risk will behave before it shows up in claims. GM does it with drivers in a 360-degree simulator; Covered California does it with the CalSIM model to estimate who remains uninsured.
Do I need quantum computing to run insurance simulation?
No. Most examples here run on standard GPU-accelerated infrastructure. Allstate uses quantum for correlated underwriting decisions, and Boeing uses it for materials modeling, but both are still breaking problems into pieces to fit current hardware. Start with Monte Carlo on GPUs.
How long does it take to build a useful simulation model?
You can run a first scenario set in a week if you already have claims or telematics data. The harder part is validation. Compare simulated outputs against your last 24 months of actual results and treat the gap as model error. That loop is what makes the simulation trustworthy.
Related Articles
- Nigeria US Health Compact: 5 Steps to Demand Transparency
- Deli Meat Health Risks: How to Limit It to Once a Week
- The Cold Song: Nordic Noir Gets an Emotional Twist
- AI in Africa: 5 Takeaways From the 11th Nigeria Innovation Summit
- Herbal Remedies: Aishat Alagbo’s Safety Warning for Nigerians
FIRST TIME REACTIONS:
Be the first to leave us a comment – 10 Insurance Simulation Examples You Can Run Today, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
Insurance today
Insurance Company Differences: Float Strategy vs. Direct Premiums
Insurance company differences come down to how they use float, handle no-exam policies, and manage risk. Compare Ethos, Ladder, and Berkshire here.

Insurance company differences come down to two things: how they write policies profitably and how they invest the money before claims are paid. That second part, called the float, separates a boring insurer from a compounding machine.
For anyone buying coverage, the practical split is simpler. You are choosing between a fully online no-exam insurer like Ethos or Ladder and a traditional agent-led carrier like New York Life or Nationwide. For investors, the split is between companies that keep float in bonds and those that swing for equity gains.
This comparison breaks down both sides using current data.
Direct-to-Consumer vs. Agent-Led Insurance Companies
Ethos and Ladder represent the fast end of the market. Ethos offers same-day coverage for most approved applicants, with term life for ages 20 to 65, coverage from $20,000 to $3 million, and no medical exam for most people. Ladder goes further on flexibility: you can increase or decrease coverage over time, access up to $3 million with no exam, and get a 30-day free look period instead of the typical 10 days.
Lantern is the quote-first option. It sells term life only, from $100,000 to $1.5 million, for ages 18 to 60, with monthly premiums as low as $10. No riders. No permanent policies. If you want add-ons, look elsewhere.
New York Life and Nationwide sit on the other side. New York Life holds an A++ AM Best rating and offers term, whole, universal, and variable universal policies. You cannot get an online quote. You must work with an agent. Nationwide is the bundling play: combine life with auto, home, renters, or pet insurance for discounts, and choose from 12 riders including long-term care and critical illness.
The trade-off is speed versus customization. Ethos and Ladder win on convenience. New York Life and Nationwide win if you need whole life, dividends, or complex riders.
Price Differences Across Policy Types
Term life is the cheapest entry point. According to U.S. News & World Report, Corebridge offers the lowest average 10-year term rates for a healthy 25-year-old female at $10.56 per month and a male at $12.67 per month for $500,000 in coverage.
Whole life costs dramatically more. Nationwide’s average sample rate for a healthy applicant seeking $500,000 in whole life coverage starts around $211.75 per month for females and $236.69 for males. That is the price of lifelong coverage plus a guaranteed cash value component.
Universal life sits in between. Protective offers the most affordable universal life sample rates at roughly $139 per month for females and $151.50 for males. Indexed universal life, which ties cash value to an index like the S&P 500 with a floor against losses, starts around $96.43 per month through Lincoln.
Final expense insurance, designed for seniors to cover funeral costs, is the smallest ticket. Transamerica offers the lowest sample rates at about $44.86 per month for females and $57.48 for males.
How Insurance Company Differences Show Up in Float Management
This is where the investor conversation gets interesting. Every insurer tries to collect more in premiums than it pays in claims. The combined ratio measures that: below 100% means underwriting profit. But the real compounding power comes from investing the float.
At one extreme, Berkshire Hathaway invests float aggressively in stocks and buys entire companies. Cincinnati Financial takes a similar but less aggressive approach, with equities at roughly 39% of its investment portfolio at the end of Q1 2026. It does not buy whole companies.
At the other extreme, Progressive holds only about 4.5% of its portfolio in equities. Chubb sits around 16.5%, including private equity. Most of their float goes into bonds to generate reliable income and stay available for large claims.
The risk difference matters. Heavy equity exposure can force asset sales at a loss if a major catastrophe hits during a bear market. Bond-heavy portfolios are less volatile but offer no capital gains upside. Cincinnati Financial is the middle ground and has raised dividends for over 50 years.
Regulatory Differences That Affect Commercial Coverage
Life insurance is not the only place where insurance company differences matter. Commercial property and casualty insurers operate under the Terrorism Risk Insurance Act, or TRIA, enacted in 2002 after the September 11 attacks.
TRIA requires commercial insurers to offer terrorism coverage, with the federal government reimbursing insured losses once thresholds are crossed. The program expires December 31, 2027. Both the House and Senate have passed seven-year extensions through 2034, but they differ on one key point.
The House bill raises the minimum loss threshold for certifying an event as terrorism from $5 million to $10 million starting in 2029. The Senate bill is a clean extension with no change. That gap matters for brokers placing coverage for commercial real estate and construction clients whose loans require terrorism insurance.
As Jimi Grande of the National Association of Mutual Insurance Companies told Insurance Business Magazine, coverage is sold on a forward-looking basis, so uncertainty reaches brokers before any lapse does.
The 2014 lapse proved the point. Terrorism coverage effectively disappeared from the standard market until Congress acted in January 2015.
Which Insurance Company Wins for Your Use Case
If you want coverage today with no medical exam, Ethos or Ladder is your pick. Ethos for same-day approval and a free will. Ladder if you expect your coverage needs to change and want to adjust without canceling.
If you want the cheapest term policy and you are healthy, get quotes from Corebridge first. Its sample rates beat the field for 10, 20, and 30-year terms.
If you need whole life, dividends, or complex riders, go agent-led. New York Life for whole life and mutual dividends. Nationwide if you want to bundle life with auto or home and save.
If you are investing, the insurance company differences that matter are float strategy and risk tolerance. Berkshire Hathaway for maximum compounding and no dividend. Cincinnati Financial for a Dividend King with moderate equity exposure. Progressive and Chubb for lower-risk bond-heavy float and consistent dividends.
Start with a quote for your coverage needs. Then check the combined ratio and equity allocation before you buy the stock.
Frequently Asked Questions
What is the main difference between an online insurance company and a traditional one?
Online insurers like Ethos and Ladder let you apply and get approved without a medical exam, often the same day. Traditional carriers like New York Life and Nationwide require an agent, may require a medical exam, and offer more complex products like whole life and universal life with riders.
How does float management create insurance company differences for investors?
Insurers invest premiums while waiting to pay claims. Berkshire Hathaway and Cincinnati Financial put significant float into equities for higher returns. Progressive and Chubb keep most float in bonds for stability. Equity-heavy float offers more upside but risks selling at a loss during a bear market if a major claim event hits.
What happens if TRIA expires before Congress resolves the House-Senate differences?
The program expires December 31, 2027. If Congress fails to reauthorize, terrorism coverage could become unavailable in the standard market, as happened in 2014 when the program lapsed until January 2015. Commercial real estate and construction clients with loan requirements for terrorism coverage are most exposed.
Related Articles
- Nigeria US Health Compact: 5 Steps to Demand Transparency
- Deli Meat Health Risks: How to Limit It to Once a Week
- The Cold Song: Nordic Noir Gets an Emotional Twist
- AI in Africa: 5 Takeaways From the 11th Nigeria Innovation Summit
- Herbal Remedies: Aishat Alagbo’s Safety Warning for Nigerians
FIRST TIME REACTIONS:
Be the first to leave us a comment – Insurance Company Differences: Float Strategy vs. Direct Premiums, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
Maintenance Tips
New Car Insurance? 7 Hidden Costs to Check Before You Buy
New car insurance can cost more than you think. See how data tracking, credit scores, and coverage changes affect your premium before you sign.

You just bought a new car. Now you need new car insurance, and the quote you get in the next 30 minutes will shape what you pay for years. The average annual premium in New York is $3,253, and your actual rate depends on factors most buyers never check.
This is a step-by-step walkthrough. You will see what to pull together before you get quotes, how to read a quote properly, and which traps to avoid. By the end, you will know exactly what to ask and what to refuse.
Step 1: Know What Your State or Province Actually Requires
Before you compare prices, confirm the legal minimum. In New York, drivers must carry personal injury protection, bodily injury and property damage liability, and uninsured motorist coverage. New York is a no-fault state, so you file a claim with your own insurer no matter who caused the accident.
The minimum PIP limit in New York is $50,000. That covers you and your passengers’ medical and rehabilitation expenses, lost wages, a death benefit, and necessary expenses like transport to treatment.
Minimum coverage in New York averages $1,246 a year. Full coverage averages $3,253. That gap is the first decision you make, and it is not always worth taking the cheaper option. If you carry the minimum $10,000 property damage liability and cause a serious accident, repairs to the other driver’s car can exceed that. You pay the difference yourself.
Step 2: Pull Your Driving Record and Credit Score
Insurers price risk. Two numbers drive that pricing more than anything else.
Your driving record first. A clean record keeps premiums down. Tickets, violations, and accidents push them up. In New York, average rates for drivers with a blemish sit well above the statewide average, though the exact penalty varies by insurer.
Your credit-based insurance score second. In New York, the statewide average for drivers with poor credit is $6,788 a year. For drivers with good credit, it is $3,253. That is more than double. New York requires insurers to send you a notice if they use your credit information to set your rate.
Step 3: Check Whether Your Car Is Sending Data to Insurers
This is the step most buyers skip, and it is the one changing fastest.
Modern cars are computers on wheels. They collect precise location data, who is in the car, what is on the radio, whether you buckle your seatbelt, how fast you drive, and how hard you brake. Some gather your weight, age, race, and facial expressions. According to the BBC, most cars have internet connections that ship that data off as you drive.
Insurance companies are among the biggest buyers. One driver told the New York Times that after his insurance costs jumped 21%, an agent told him data held by the broker LexisNexis was a factor. That file reportedly ran 130 pages, detailing every trip he and his wife took over six months.
The US Federal Trade Commission has barred General Motors from selling vehicle data for five years, but GM can resume afterwards with express consent. LexisNexis and other companies still sell vehicle data from other manufacturers and driving apps.
What to do: when you set up your infotainment system, read the data-sharing screens. Decline optional data sharing where the option exists. If you use an insurer’s telematics app for a discount, understand that you are trading driving data for that discount.
Step 4: Get Quotes From at Least Three Insurers
Rates vary wildly by company. In New York, American Family has the lowest average annual rate at $1,824, and Kemper is second at $1,842, according to US News. Both sit far below the $3,253 statewide average.
Get quotes from at least three companies. An independent agent can run several at once. Ask specifically about discounts for a clean accident record, good student status, and customer loyalty.
If you cannot get coverage through private companies, New York offers the New York Automobile Insurance Plan, or NYAIP. Every insurer in the state must participate, so high-risk drivers get assigned to one. Expect to pay more, but a clean record for at least four years may qualify you for a careful driver discount.
Step 5: Understand What You Are Giving Up If You Cut Coverage
Some markets are making coverage optional that used to be standard. Ontario changed its rules on July 1 so drivers can opt out of accident benefits including income replacement, lost educational expenses, death benefits, and funeral expenses. Only medical care, rehabilitation, and attendant care remain mandatory.
Broker Lance Miller told CBC that the average customer saves $100 to $200 a year by taking the most basic coverage. But he points out that opting out of funeral expenses might save $30 to $50 a year, while an actual funeral costs tens of thousands.
There is a second trap. The change only applies to new or updated policies, and only the driver, the driver’s spouse, and dependents are covered under optional benefits. If you lend your car to someone not on your policy, that person is covered only up to the mandatory minimum. Pedestrians and cyclists injured in a crash cannot claim the newly optional benefits tied to the driver’s policy unless specifically stipulated.
Insurance expert Daniel Ivans of rates.ca put it plainly: reducing coverage is usually not the best way to get prices down. Shop first, cut second.
Step 6: Compare Like for Like
When quotes land, line them up on the same coverage levels, the same deductible, and the same optional add-ons. A cheaper quote with lower limits is not cheaper.
If you raise your deductible, confirm you can actually pay it if you file a claim. A higher deductible lowers your premium, but only if the money is there when you need it.
Mileage matters too. In New York, low-mileage drivers averaging 7,000 miles a year pay about $3,031, while high-mileage drivers at 14,000 miles pay around $3,253. If you drive less than you estimated, tell your insurer.
Step 7: Recheck at Every Renewal
Rates are not fixed. Vehicle theft and climate change have pushed auto insurance to new heights over the past decade, according to Ivans. Your premium will move even if nothing about you changes.
At each renewal, rerun quotes from at least three insurers. If your credit score improved or a violation dropped off your record, you may be overpaying on autopilot.
What to Do Next
Today, open your current policy or the quote you were just given. Find the coverage limits, the deductible, and any data-sharing or telematics consent you signed. Then get two more quotes on identical coverage.
If you drive a car built in the last few years, spend ten minutes in your infotainment settings and turn off optional data sharing. That single step costs nothing and limits what insurers and data brokers can learn about how you drive.
Frequently Asked Questions
Does my car really send data to insurance companies?
It can. Modern cars collect location, speed, braking, seatbelt use, and in some cases facial expressions and weight. Insurance companies are among the biggest buyers of that data. Some car companies admit they sell it but do not have to disclose who buys it. You can limit this by declining optional data sharing when you set up your infotainment system.
How much can I save by dropping optional coverage in Ontario?
Broker Lance Miller estimates the average customer saves $100 to $200 a year by choosing the most basic coverage. But individual items save very little. Opting out of funeral expenses might save $30 to $50 a year, while an actual funeral costs tens of thousands of dollars.
What is the cheapest car insurance in New York?
US News research found American Family has the lowest average annual rate at $1,824, followed by Kemper at $1,842. The statewide average is $3,253. Rates vary by driver profile, so get quotes from at least three insurers before deciding.
Related Articles
- Nigeria US Health Compact: 5 Steps to Demand Transparency
- Deli Meat Health Risks: How to Limit It to Once a Week
- The Cold Song: Nordic Noir Gets an Emotional Twist
- AI in Africa: 5 Takeaways From the 11th Nigeria Innovation Summit
- Herbal Remedies: Aishat Alagbo’s Safety Warning for Nigerians
FIRST TIME REACTIONS:
Be the first to leave us a comment – New Car Insurance? 7 Hidden Costs to Check Before You Buy, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
-

 Trending Entertainment News4 days ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News3 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Startups3 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Nigerian Business2 weeks ago
Moniepoint POS Network: How to Buy Dangote Shares
-
Fintech3 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News
-
Fintech3 weeks ago
OPay Investing in People to Build a Better Nigeria
-
Football3 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
Black Celebrities3 weeks ago
Brandi Carlile: Rock Star in Her Prime, On Tour Now