World News
Table Energy: J.J. Martin’s Book On Italian Hosting
J.J. Martin’s Table Energy, from Vendome Press, turns Italian hosting into a $50 book and a La DoubleJ product line, with global release dates.


J.J. Martin, the Los Angeles-born editor turned entrepreneur who founded the Milan label La DoubleJ, has published her second book with Vendome Press: Table Energy: Entertaining With Italian Spirit. The 208-page coffee-table volume launched in the United States this week and is scheduled to reach the rest of the world from Nov. 5, beginning with Europe, at $50.
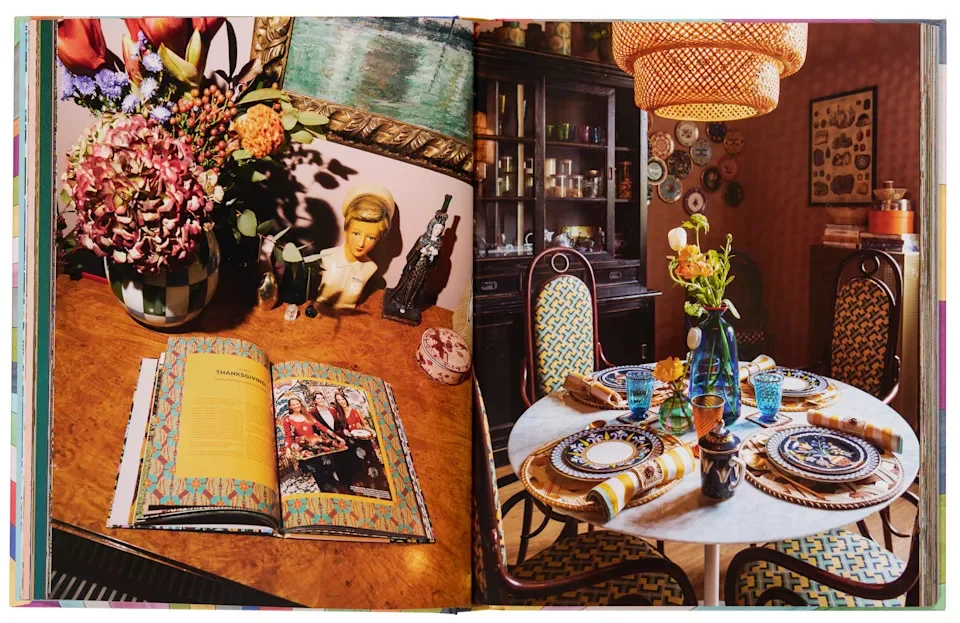
The book is a photographic record of Martin’s own hosting — Milanese aperitivos, alfresco lunches in Portofino and Taormina, weekend gatherings on Lake Como — built around an argument she sets out in the introduction: that in Italy the table is ‘never just a table.’
That is the thesis. What follows separates what the record confirms from what the publisher and the brand have so far only announced.
From A New York Ad Agency To A Label Called La DoubleJ
Martin’s route into Italian hospitality was not direct. She started as an account executive at an advertising agency in New York and San Francisco, then moved into marketing at Calvin Klein in New York. She relocated to Milan in 2001 and wrote for Harper’s Bazaar and Wallpaper before launching La DoubleJ in 2015 as a shoppable magazine that sold clothing and jewelry.
La DoubleJ has since expanded into tabletop collections, which appear throughout the book’s photographs. Martin describes the look as a blend of her California upbringing and a growing spiritual practice — ‘an unapologetically bold way of mixing and layering vivid color and swirling print,’ as she writes in the introduction.
What Table Energy Confirms, And What It Merely Announces
Confirmed: the book runs 208 pages, carries a foreword by Leandra Medine Cohen, retails at $50 and is sold through La DoubleJ stores and e-commerce, Vendome Press‘s online store, Amazon, and selected international bookshops — via Abrams in North America and Thames & Hudson in the rest of the world.
Scheduled but not yet delivered: a Power of Light candle collection set to debut Oct. 29, a capsule collection developed with Carolyn Murphy dropping Nov. 5, an event in Paris on Nov. 24, and a book signing at the brand’s Milan store on Dec. 1. Each of those is a plan on a calendar, not an accomplished fact, and the reporting around the title gives no confirmed sales, print-run or revenue figures.
That distinction matters for anyone reading Table Energy as a business story rather than a lifestyle one. The volume’s commercial logic — a $50 object that showcases tabletop products the reader can then buy — is a strategy, not a result. Claims about how well it works remain untested until the publisher or the brand releases numbers.
The Distribution Map Stops Short Of African Retail
The named channels are precise about North America and Europe and silent on most of the Global South. No African stockists, no local-currency pricing and no regional distribution partner appear in the release details. Readers in Lagos, Nairobi or Accra are pointed to Amazon or Vendome’s own online store, with shipping and import duty left unaddressed.
That is a gap in disclosure, not a controversy. It does, however, place the book in a familiar category: a European luxury-lifestyle imprint whose ‘rest of world’ agreement with Thames & Hudson is effectively an Anglo-American and Commonwealth arrangement rather than a genuinely global shelf presence.
Why The Second Book Carries More Commercial Weight Than The First
Table Energy follows Mamma Milano: Lessons From the Motherland, Martin’s 2023 debut with Vendome, which traced her early years in the city and profiled Italian tastemakers including Angela Missoni, Max Mara’s Laura Lusuardi, Rossella Jardini, Rossana Orlandi, Patricia Urquiola, Nina Yashar, Marie-Louise Sciò and Molly Molloy.
The first book was biography and scene-portrait. The second is instruction plus catalogue — tips, personal reflections and anecdotes, among them Martin’s first attempt at hosting in Milan after leaving Manhattan in 2001, when she accidentally set a Thanksgiving turkey on fire in a cramped ’70s oven. Her stated takeaway: ‘The more experience I got, the more I relaxed: less fancy food, less pomp, less formal help or service.’
Medine Cohen’s foreword describes the gatherings as ‘Thrilling and tender, bright and joyful. Full to the brim with taste,’ and recounts Martin calling this ‘the easiest book she’s ever created.’ That is a friend’s characterization, offered in a foreword, and should be read as such rather than as independent editorial judgment.
What The Book Says About Where La DoubleJ Goes Next
Martin’s framing is deliberately portable. My hope is that this book gives you permission to play,’ she writes, adding that readers should let ‘nothing but your own intuition and delight guide you in the creation of your own table energy back home.‘ The lowercase phrasing is a hint at intent: the title is meant to function as a concept the brand can keep selling, through candles, ceramics and capsule drops, long after the first print run clears.
Whether Table Energy becomes a durable franchise or a well-photographed seasonal title will be settled by figures neither Vendome Press nor La DoubleJ has published. Until then, the verifiable record is short and firm: a 208-page book, a $50 price, a U.S. launch this week, a European release on Nov. 5, and four dated promotional events stretching to Dec. 1. Everything past that is forecast.
Frequently Asked Questions
When is J.J. Martin’s Table Energy released?
Table Energy: Entertaining With Italian Spirit launched in the United States this week. Release in the rest of the world begins with Europe on Nov. 5, according to the publisher’s stated schedule.
How much does Table Energy cost and where is it sold?
The 208-page book retails at $50. It is available at La DoubleJ stores and e-commerce, on Vendome Press’s online store, on Amazon, and at selected international bookshops distributed by Abrams in North America and Thames & Hudson elsewhere.
Is Table Energy J.J. Martin’s first book?
No. It is her second publication with Vendome Press, following Mamma Milano: Lessons From the Motherland, released in 2023.
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – Table Energy: J.J. Martin’s Book On Italian Hosting, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:

About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare Dominic

World News
Oura Sues Ultrahuman Again: Inside the Ring Pro Patent Fight
Oura sues Ultrahuman again over Ring Pro patents in a Texas federal court, threatening the Indian startup’s US market comeback.
Mohit Kumar spent most of this year making an engineering argument. On Thursday, a federal court in Texas turned it into a legal one.
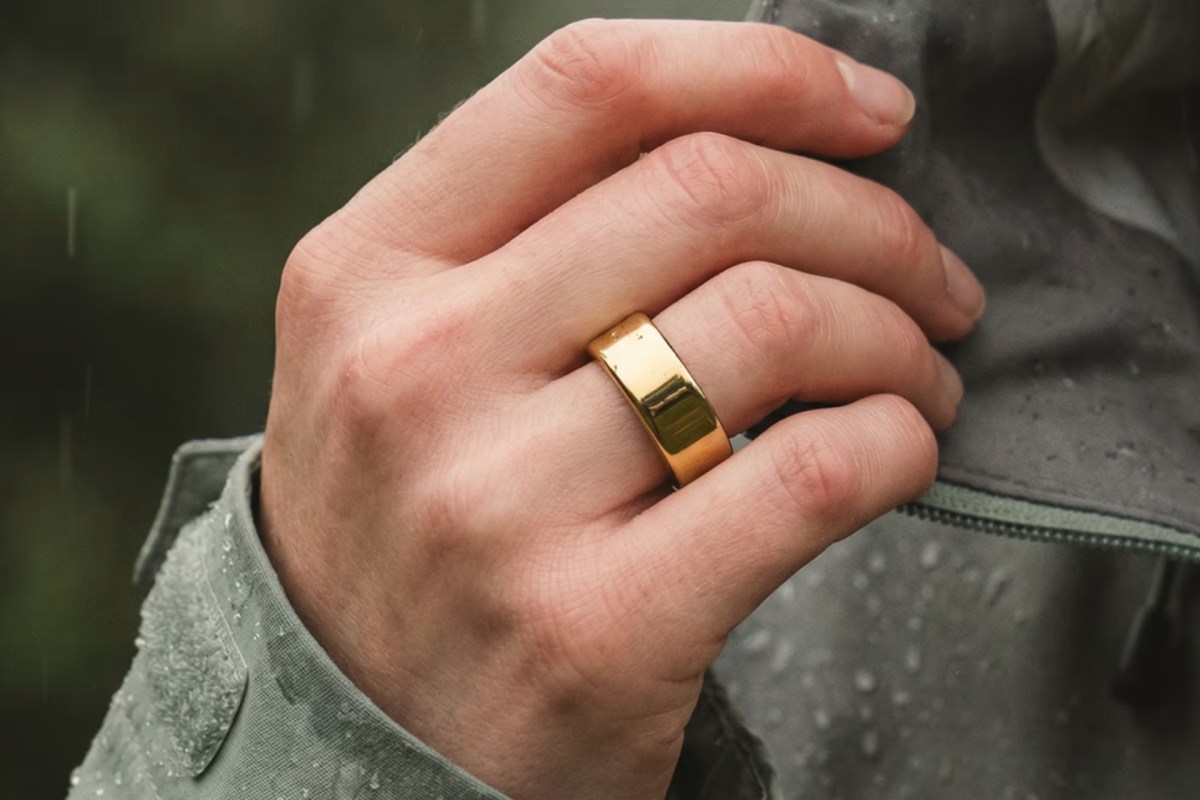
Oura filed a patent infringement complaint seeking to block US sales of Ultrahuman’s Ring Pro, the redesigned ring that carried Kumar’s Bengaluru company back into the American market only months after an import ban pushed it out. It is the second time Oura sues Ultrahuman in a US court, and the first aimed at the device the startup built specifically to get back in.
The complaint names Ultrahuman and SVTronics, a Plano, Texas electronics manufacturer that Oura says builds the Ring Pro under Ultrahuman’s direction and control. Oura is seeking monetary damages and a permanent injunction.
Kumar’s position is now double-edged. He runs a company valued at about $365 million after a $70 million raise in September that drew Qualcomm Ventures and Labcorp. He is also the defendant in a case that could remove his flagship product from the largest smart-ring market outside his home base.
Why Oura Sues Ultrahuman Again, Two Days After A New Patent
The timing is the detail worth pausing on. The complaint cites two Oura patents: D804,471, a design patent, and 12,769,363, which covers a ring architecture built around a curved battery, circuit board, magnets and sensors. The second was issued to Oura on 20 October, two days before the company filed suit.
Oura argues that the Customs decision which let the Ring Pro into the US covered only the patent at issue in the earlier dispute, not these two. “Ultrahuman has a history of copying Oura’s innovations, as demonstrated by the 2025 ITC ruling against the company,” an Oura spokesperson told TechCrunch. “Ultrahuman introduced a redesigned ring but failed to address continued infringement of Oura’s patents.”
Ultrahuman did not respond to TechCrunch’s request for comment. The company has not publicly answered the new filing.
From The Ring Air Ban To Ring Pro Clearance
The dispute dates to 2023, when Oura first sued Ultrahuman over the Ring Air. Oura then brought a case at the US International Trade Commission in 2024 and won a ruling in August 2025, which blocked imports of the Ring Air and its components. Wired reported that the ITC finding rested on a hardware patent covering layered internal and external components, a description broad enough to reach most rings on the market.
Ultrahuman’s answer was a redesign. It unveiled the Ring Pro in February, began selling globally, and in March received a favourable ruling from US Customs and Border Protection. CNET reported the clearance opened preorders at $349 for the first 1,000 buyers and $399 afterwards, with a charging case at $100 or $479 as a bundle. The ring claims 15 days of battery life, 45 with the case, and unlike Oura charges no subscription for core sleep, recovery and stress data.
“We’re delighted to be back in the US with Ring Pro,” Kumar said at the time. “Ultrahuman is an engineering company, and we believe that the company that leads with engineering will ultimately win in this space.”
The Delhi Counterclaim That Did Not Survive
Kumar’s company has fought back in court before, without success. In 2025 Ultrahuman filed its own infringement suit against Oura in the Delhi High Court, alleging Oura copied women’s health features, circadian tools and its glucose monitoring platform. The court dismissed the case on 1 September 2025, with Justice Manmeet Pritam Singh Arora presiding, Mashable reported. Ultrahuman said it would clarify and re-file.
Oura called that action meritless at the time and described the ITC outcome as decisive. Ultrahuman’s public case has rested on patent age rather than patent absence. “This isn’t a dispute over years of secret R&D,” the company wrote in a blog post about the litigation. “It’s about a very recent patent purchase now being wielded to limit the choices ring-wearers like you have.”
The pattern is now established: Oura sues Ultrahuman in US courts, and Ultrahuman counters where jurisdiction allows.
What The Ring Fight Means For Buyers Outside America
IDC expects global smart-ring shipments to rise 12.8% this year to 4.9 million units and reach about 6.3 million by 2030. Neither company breaks out Africa figures in the filings and statements described here, and that gap matters. Distributors and buyers on the continent sit at the end of an import chain that reacts to US legal outcomes: a permanent injunction would not simply shift American pricing, it would reshape which devices reach secondary markets and at what cost.
The commercial asymmetry is stark. Research firm Omnia put Oura at roughly 74% of the smart ring market last November and Ultrahuman at about 9%. Oura has converted several rivals into licensees, with RingConn and Circular agreeing to pay royalties, while cases against Samsung and Zepp Health continue. It has also shelved a $2.2 billion IPO, citing market “uncertainty,” just weeks before filing this complaint.
That context cuts both ways. A company preparing to return to public markets has reason to defend its patent portfolio loudly. A challenger that just raised $70 million and is co-developing a Qualcomm-powered ring has reason to keep selling.
Kumar’s wager, that engineering beats litigation, now waits on a judge in Texas. Whether Oura sues Ultrahuman again after this complaint, or settles into another royalty arrangement, will say more about the structure of the smart-ring market than any product launch. For buyers in Lagos, Nairobi or Johannesburg, the practical question is narrower: which ring, and at what price, survives the injunction stage.
Frequently Asked Questions
What patents does Oura say the Ultrahuman Ring Pro infringes?
Oura’s complaint cites two: design patent D804,471 and patent 12,769,363, which covers a ring design using a curved battery, circuit board, magnets and sensors. The second patent was issued to Oura on 20 October, two days before the suit was filed.
Why is SVTronics named in the lawsuit?
Oura alleges that SVTronics, a Plano, Texas electronics manufacturer, builds the Ring Pro under Ultrahuman’s direction and control, and that both companies infringe its patents through manufacture, importation and sale of the device in the US.
How did Ultrahuman return to the US market before this suit?
After the ITC import ban on its Ring Air, Ultrahuman redesigned the hardware as the Ring Pro, launched it in February, and received a favourable ruling from US Customs and Border Protection in March, which cleared it for US preorders.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Oura Sues Ultrahuman Again: Inside the Ring Pro Patent Fight, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare DominicWorld News
Lunai Bioworks Nasdaq Delisting Ends A Bid-Price Illusion
Lunai Bioworks Nasdaq delisting: LNAI exits on Nov 12 with a $9.02M equity deficit, two reverse splits and no OTC quoting plan.
The Lunai Bioworks Nasdaq delisting is no longer a risk disclosure. It is a calendar entry. On 21 October 2026 the Sacramento-based company received a letter from the Listing Qualifications Department of Nasdaq stating that it no longer complies with Listing Rule 5550(b)(1), which requires minimum stockholders’ equity of $2,500,000. Trading in LNAI is expected to be suspended at the opening of business on 30 October 2026. A Form 25 is due on or about 2 November 2026, with the delisting effective on or about 12 November 2026, followed by a Form 15 intended to suspend SEC reporting obligations.
The company did not contest the finding. Its board voted on 22 October 2026 to withdraw the common stock from Nasdaq voluntarily under Rule 12d2-2(c) of the Securities Exchange Act of 1934. The reason given was the staff determination and the company’s financial condition, with the board concluding that the cost of continued listing and SEC reporting is no longer justified.
Why The Lunai Bioworks Nasdaq Delisting Was Never A Bid-Price Story
The failure was on equity, not price. Lunai’s Annual Report on Form 10-K for the fiscal year ended 30 June 2026 reported a stockholders’ deficit of $(9,024,946). Against a $2.5 million minimum, that is a shortfall of roughly $11.5 million by simple arithmetic. The release also states the company does not meet Nasdaq’s alternative tests based on market value of listed securities or net income.
That detail matters because the public record around this ticker over the past year pointed the other way. In a separate SEC filing, Lunai disclosed that Nasdaq had confirmed it regained compliance with the exchange’s $1 minimum bid price requirement, following an initial notice on 20 April and extension letters on 12 May. Stocktwits reported that shares rose more than 100% in pre-market trading on a Wednesday after that disclosure, with retail sentiment flipping to “extremely bullish” and message volume up sharply.
Two Reverse Splits Did Not Build Equity
That bid-price compliance was manufactured, not earned. Shareholders at a special meeting on 8 May approved a reverse split within a 1-for-3 to 1-for-30 range, and the board settled on 1-for-8, effective 22 May. Outstanding shares fell from about 36.3 million to about 4.5 million. The company had already executed a 1-for-10 reverse split on 30 September 2025.
Stacked, those two actions mean an investor holding 80 shares before September 2025 would hold one share after May 2026, absent other issuance. A reverse split raises the quoted price arithmetically while leaving market capitalisation and stockholders’ equity unchanged. It cannot close a $9 million deficit. Nasdaq also placed Lunai under a one-year monitoring period, under which a renewed bid-price failure would not qualify for a standard compliance plan or extension.
Then came the procedural trap. Because Lunai was subject to a mandatory Hearings Panel Monitor under Nasdaq Listing Rule 5815(d)(4)(B), the release states that Nasdaq staff determined to delist rather than route the company through a fresh cure period. Lunai declined to request a hearing. The release does not itemise the listing and reporting costs the board weighed, and it does not give a figure for them.
An Exit With No Secondary Venue
What follows the delisting is unusually bare. Lunai says it does not intend to arrange for quotation of its common stock on any over-the-counter market, and cannot assure that any trading market will exist once Nasdaq trading stops. Its SEC reporting obligations continue unless and until they are terminated or suspended under SEC rules, and the company describes its own filings as forward-looking intentions subject to Nasdaq and SEC procedures.
This is not an isolated pattern. In the same month, SITE Centers Corp. (NYSE: SITC), a self-managed REIT based in Beachwood, Ohio, announced its intention to notify the New York Stock Exchange of a voluntary delisting, anticipating that a special distribution declared on 15 October 2026 would push its share price and market capitalisation toward levels triggering involuntary removal. Per the SITE Centers announcement, the delisting is expected before trading begins on 4 December 2026, and no listing, registration or Rule 15c2-11 quotation arrangement has been made elsewhere.
Set the two side by side and the contrast is instructive. One company is leaving to distribute capital; the other is leaving with negative equity. The mechanics are identical: a Form 25, an exchange exit, and no regulated venue for holders afterwards. The Lunai Bioworks press release makes no mention of its research programmes, headcount, financing plans or operations, so the effect of the exit on the underlying business cannot be assessed from the primary document.
What African And Global Issuers Should Read In It
For founders and investors in Africa and other emerging markets who treat a US exchange listing as a badge of maturity, the case separates two things that get conflated in headlines: listing compliance and financial health. A company can pass the price test, issue a triumphant press release about compliance, and fail the equity test months later without any change in its underlying position.
It also clarifies who carries the residual risk. Under the announced plan, the last regulated price becomes the last price. Holders using mobile brokerage apps in Lagos, Nairobi or London face the same outcome as institutional shareholders, with no OTC quotation to exit through, and no assurance from the company that any market will exist.
All of this is confirmed in the company’s own 22 October 2026 statement, corroborated by its earlier bid-price filing and by the parallel SITE Centers exit. What remains allegation or forecast: nothing in the record suggests misconduct, and none should be inferred. What remains unknown is the company’s post-delisting strategy, which the release does not address.
The big picture is a reminder that the Nasdaq floor is a compliance floor, not a solvency floor. The Lunai Bioworks Nasdaq delisting was scheduled within nine days of the Nasdaq letter, executed by board vote, and leaves no backstop market behind it. Read the equity line of a 10-K before the pre-market headline.
Frequently Asked Questions
Why is Lunai Bioworks delisting from Nasdaq?
Nasdaq’s Listing Qualifications Department notified the company on 21 October 2026 that it no longer complies with Listing Rule 5550(b)(1), which requires minimum stockholders’ equity of $2,500,000. Lunai reported a stockholders’ deficit of $(9,024,946) for the fiscal year ended 30 June 2026 and did not meet alternative market value or net income standards. Because the company was under a mandatory Hearings Panel Monitor, Nasdaq staff determined to delist.
When will LNAI stop trading on Nasdaq?
Trading is expected to be suspended at the opening of business on 30 October 2026. The company intends to file a Form 25 on or about 2 November 2026, with the delisting effective on or about 12 November 2026. It then intends to file a Form 15 to suspend SEC reporting obligations, to the extent it is eligible.
Will Lunai Bioworks shares trade over the counter after delisting?
No. The company stated it does not intend to arrange for quotation of its common stock on any over-the-counter market and cannot assure that any trading market will exist after Nasdaq trading is suspended. A comparable October 2026 announcement from SITE Centers Corp. also confirmed no alternative listing or Rule 15c2-11 quotation arrangement.
Did reverse stock splits cause the delisting?
They did not cause it, and they could not have prevented it. Lunai executed a 1-for-10 reverse split on 30 September 2025 and a 1-for-8 split effective 22 May 2026, reducing outstanding shares from roughly 36.3 million to about 4.5 million. A reverse split lifts the quoted share price arithmetically but leaves stockholders’ equity unchanged, so it addresses the $1 bid price rule rather than the $2.5 million equity requirement.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Lunai Bioworks Nasdaq Delisting Ends A Bid-Price Illusion, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare DominicWorld News
Trump Says Musk Restored Starlink Access For Ukraine
Trump says Musk restored Starlink access for Ukraine’s military, but no public record shows who ordered the speed caps or on what authority.

Elon Musk has restored Starlink access for Ukraine’s armed forces after speed caps degraded Kyiv’s ability to fly attack drones and intercept Russian strikes, US President Donald Trump said on Thursday. Trump declined to confirm whether he was the one who asked.
“Bottom line, he put it back,” Trump told reporters when asked about a Wall Street Journal report that he had phoned Musk to demand the limits be lifted. “I don’t want to comment on it, whether I called or whether somebody else called, doesn’t make any difference.”
The remark is the first on-the-record confirmation from the administration that restrictions existed at all. For the previous eight days, officials in Washington had said no such order was given.
What Is Confirmed About The Starlink Access Dispute
Two documented dates anchor the timeline. On 13 October, Ukrainian officials announced that sudden restrictions on the service had left the military scrambling, Al Jazeera reported. The BBC places Ukraine’s first report of an interruption to US intelligence sharing at 14 October.
Speaking before Trump’s remarks, President Volodymyr Zelensky said the speed available to Ukrainian forces “has not been restored to 400 [km/h; 250mph] yet”. He added: “We are working on it,” and said he was waiting on US Secretary of State Marco Rubio, who had promised information within 48 hours.
The Wall Street Journal then reported that Trump had called Musk and told him he was frustrated that speeds were still capped at around 160km/h, a limit that left Ukrainian offensive drones and interceptors unable to function against Russian attacks. The paper said the system was working more normally on Thursday, shortly after the conversation. The BBC has not verified that account and has contacted the White House and SpaceX.
Ukraine uses the civilian Starlink network and the more secure Starshield system. Both draw on roughly 10,000 satellites in low Earth orbit. Drone warfare depends on high-speed links, which is why a speed cap functions as a battlefield decision rather than a commercial one.
Two Parties, Two Accounts, No Paper Trail
The two parties closest to the switch have given accounts that do not fit together. Musk wrote on 14 October that Starshield is “owned and controlled by the US government” and that “any limits on speed or usage are decided by the US military and ultimately POTUS”.
Rubio said on Wednesday that neither the president nor anyone in the administration “ever requested that any changes to that system be made”. He said decisions about Starlink access are “governed by a private commercial contract as to how their stuff can be used and what speeds they’ll allow it to be used at”, adding that “the president has nothing to do with the decisions that are made by Starlink and Starshield and by Mr Musk”.
Each statement can be read as technically accurate, and that is the difficulty. No contract clause, Pentagon order or company statement has been published that establishes which party held the switch, or on what authority it was turned. The public record contains a denial, a social media post, a reported phone call and a one-line confirmation. It contains no decision trail.
John Cornyn, the Republican in his final weeks as US senator for Texas, told US media he did not believe Musk would have acted “without at least the acquiescence of the White House”. That is an assessment offered without documentation, not evidence.
The Diesel Rationale Has Not Been Shown To Hold
Trump’s pressure on Kyiv has been tied publicly to fuel prices. He has accused Ukraine of driving up diesel costs for Americans through its attacks on Russian refineries, and he faces midterm elections next month. His administration has waived some sanctions on Russia and agreed a deal to import Russian diesel, a move Ukraine and its European allies criticised.
The causal claim is thinner than the policy built on it. Analysis by the BBC, cited by the Guardian, found that the US-Israeli war on Iran and the resulting restrictions on oil exports from the Gulf likely had a greater effect on global diesel supplies than Ukrainian strikes did. No published US data has been presented to show that refinery attacks were the dominant driver of American pump prices.
What The Episode Reveals Beyond The Battlefield
Governments and humanitarian agencies outside the US alliance structure buy satellite connectivity as commercial customers. The dispute shows where their risk actually sits: not in the vendor’s goodwill, but in what a contract specifies about speed, uptime and grounds for interruption. Neither SpaceX nor the White House has disclosed those terms in this case.
That is the transferable lesson for markets in Africa and elsewhere where satellite internet is bought rather than built. A customer who is not party to the arrangement between a company and the Pentagon has no lever except escalation, and escalation requires a head of state willing to make a call. Ukraine had one. Most buyers do not.
The episode also sets a precedent that cuts both ways. If a speed cap can be applied and removed within eight days without a published order, the capability remains available for future use, and the absence of documentation makes it harder to establish accountability either way.
What To Watch
Zelensky said he expects Rubio’s answer within roughly 48 hours; whether that answer confirms or contradicts the Wall Street Journal account is the next verifiable data point. Watch also for any statement from the Pentagon, which Musk’s version of events places at the centre of the decision, and from SpaceX, which has so far said nothing publicly.
The durability of the restoration is untested. Zelensky’s own measure was a speed figure, not a press statement, and no independent monitoring of Starlink access in Ukrainian combat zones has been published. Until it is, the confirmed facts are narrow: restrictions were reported on 13 October, Trump says they are lifted, and the only documented explanation for either decision is a conversation nobody in the room will describe in full.
Frequently Asked Questions
Did Trump order the Starlink speed restrictions on Ukraine?
Trump has denied it, saying on Friday: “I don’t know if it was anybody, but it wasn’t me, and I don’t think it was Elon.” Secretary of State Marco Rubio said neither the president nor anyone in the administration requested changes. Musk said limits are decided by the US military and ultimately the president. No contract clause, Pentagon order or company statement has been published to settle the question.
What is the difference between Starlink and Starshield?
Starlink is the civilian satellite internet service. Starshield is the more secure, military-grade version designed for the Pentagon. Ukraine uses both depending on what communications are needed. Both networks rely on roughly 10,000 satellites in low Earth orbit.
Has Ukraine’s Starlink access been fully restored?
Trump said on Thursday that Musk “put it back”. Earlier the same day, Zelensky said the speed used by Ukraine’s military had not yet returned to 400 km/h and that he was waiting for information from Rubio. The Wall Street Journal reported service was closer to normal after Trump’s reported call to Musk, but the BBC has not verified that account.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Trump Says Musk Restored Starlink Access For Ukraine, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare Dominic-

 Startups4 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Health and Fitness1 week ago
Curly Hair Hydration: 5 Proven Steps That Actually Work
-
Trending Entertainment News2 weeks ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News4 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Tech & Gadgets2 weeks ago
Apple Watch and AirPods Fall Deals: Save $120 Today
-
Football4 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
University Admissions4 weeks ago
UNILAG 2026/2027 Admission: Direct Entry & Post-UTME Guide
-
Fintech4 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News