World News
SON Urges Manufacturers to Sustain Product Quality Standards
SON marked 20 years of MANCAP by urging manufacturers to sustain product quality standards, but its own published figures disagree on the scheme’s record.

Nigeria’s standards regulator has told manufacturers that product quality standards must survive the certificate, not just the inspection that precedes it. The call came at an awards ceremony built to celebrate two decades of mandatory certification, and the record behind it shows real growth alongside gaps the agency has not closed.
The Director-General of the Standards Organisation of Nigeria (SON), Dr Ifeanyi Okeke, used the 2026 National Mandatory Conformity Assessment Programme (MANCAP) Quality Award Ceremony in Lagos to set out a three-part bargain. Manufacturers must stay committed to standards, regulators must enforce fairly and consistently, and consumers must demand quality and make informed choices, he said, according to Punch.
The event marked 20 years of MANCAP, SON’s flagship mandatory certification scheme for goods manufactured inside Nigeria. The scheme exists to stop substandard and unsafe products reaching shelves, to promote fair competition, and to support economic diversification.
Two Accounts Of The Same Twenty Years
The published records of the ceremony do not agree on the scheme’s headline numbers. Punch reported that certifications and revalidations rose from 1,930 products made by 458 companies in MANCAP’s first year to 17,866 products from 8,634 companies. The Sun reported from the same Lagos event that Okeke disclosed growth to “between 7,000 and 8,000 products certified from 8,634 companies.”
The start date is also given two ways. Punch said the scheme took effect on January 1, 2006. The Sun said it was introduced on February 1, 2006. Neither difference changes the substance of a 20-year anniversary. Both show why announcements of this kind are best read against documents rather than coverage alone.
What is not disputed is the direction of travel. A scheme that certified fewer than 2,000 products in its first year now reports certifications in the thousands, spread across more than 8,600 companies. The Permanent Secretary of the Federal Ministry of Industry, Trade and Investment, Dr Chris Isokpunwu, said the anniversary represented a milestone in Nigeria’s quality infrastructure and that government policy was to make quality a driver of industrial growth rather than a compliance chore. The theme was “Building Trust in Quality and Safety Ecosystems.”
How Product Quality Standards Are Tested Before A Certificate Issues
MANCAP certification is not a paperwork exercise, at least on paper. Okeke said it involves factory inspections, product sampling, laboratory testing, compliance reviews and certification. Certificates are renewable every three years, with annual surveillance inspections and testing in between.
Engr Ayodele Akinware, who heads the MANCAP Division, said the scheme now covers six sectors: food; chemicals; electrical and electronics; mechanical products; civil and construction materials; and textiles and leather. The SON Act 2015 strengthened its legal framework, and SON introduced a new MANCAP logo in March 2025 to improve consumer recognition.
The agency has also built export-facing routes around the scheme, including the SON Export Conformity Assessment Programme (SONEXCAP), the Special Economic Zones Conformity Assessment Programme (SEZCAP) and the Product Identification Scheme. At a separate Lagos ceremony presenting SEZCAP certificates, the Director of SON’s Lagos Region, Mrs Theresa Ojomo, said certification “is not the end of the compliance process, but the beginning of a continuous partnership,” Realnews reported.
The Enforcement Gap SON Named Itself
The sharpest evidence of the distance between certification and compliance came from Ilorin, not Lagos. Presenting MANCAP certificates to two concrete electric pole manufacturers, Omo’ya Concrete Electric Poles Industries Ltd and Jofco Concrete Industries, Okeke expressed displeasure over block manufacturers in Kwara State that were not meeting SON’s requirements for construction materials, the News Agency of Nigeria reported.
That is a regulator describing non-compliance inside a building-materials supply chain, in public, at its own certification event. It is more informative than any award handed out that week. Okeke said the organisation would continue to enforce standards.
SON officials have been explicit that certification carries ongoing obligations. The Assistant Director of MANCAP, Mr Ekokeme Prete, said recipients must maintain consistency in quality throughout the three-year validity period to qualify for renewal. The State Coordinator for SON Lagos Office II, Mrs Maryrose Ugwueche, put it plainly: “Once we issue your certificate, our eyes will be seriously on you. Please, there is no shortcut to certification.”
What The Public Record Does Not Show
SON did not disclose, in any of the published accounts, how many manufacturers currently hold valid MANCAP certificates. The 8,634 figure is cumulative over two decades, not a count of active certifications. Nor did the agency release figures on market surveillance findings, product recalls, certificate withdrawals or prosecutions arising from the scheme.
Without those figures, growth in certifications measures participation, not compliance. A rising total tells a reader how many companies entered the system. It does not say how many stayed, how many were sanctioned, or how much uncertified product still reaches Nigerian buyers.
Ojomo said manufacturers could pursue harmonised certification schemes to ease access to markets across Africa and beyond. That is a testable claim, but the case for it rests, so far, on assertion rather than published outcomes.
Where This Leaves Manufacturers And Buyers
MANCAP’s logic depends on consumers using the certificate. SON says certified products carry unique identification numbers that buyers can check, and the 2025 logo change was aimed at making that easier. That places the scheme’s credibility partly in the hands of shoppers who rarely inspect labels at the point of sale.
The manufacturing side faces a different pressure. Certification costs time and money, and companies that invest in it compete against producers who skip the process. Okeke’s framing acknowledges the tension: enforcement must be fair and consistent, or the compliant manufacturer carries a penalty for complying.
Isokpunwu argued that quality and safety should not be treated as optional by anyone in what he called the quality ecosystem. “Every participant in the quality ecosystem has a responsibility to ensure that standards are respected and that the safety and performance of products are not compromised,” he said. Mr Uchendu Okuwa, chairman of Eagle Industry, urged certified companies to run their own self-inspections rather than wait for external ones.
That advice reveals the scheme’s real dependency. Regulators inspect periodically. Factories produce daily. The gap between those two rhythms is where product quality standards are either held or quietly abandoned, and it is the gap that no award ceremony can close on its own. SON has now spent 20 years building the certification architecture to support product quality standards in Nigeria. The next phase depends on evidence it has not yet published: what happens to a certificate after the ceremony ends.
Frequently Asked Questions
What did SON ask manufacturers to do at the 2026 MANCAP Quality Award Ceremony?
Director-General Dr Ifeanyi Okeke urged manufacturers to remain committed to standards, regulators to enforce fairly and consistently, and consumers to demand quality and make informed choices. The ceremony in Lagos also marked 20 years of the MANCAP scheme.
How large is MANCAP after 20 years?
Published accounts of the ceremony give different figures. Punch reported growth to 17,866 products from 8,634 companies, up from 1,930 products by 458 companies in the first year. The Sun reported the same 8,634 company figure but described certified products as between 7,000 and 8,000.
How long does a MANCAP certificate last and what does certification involve?
SON says MANCAP certificates are renewable every three years, with annual surveillance inspections and testing. Certification involves factory inspections, product sampling, laboratory testing, compliance reviews and certification against Nigerian Industrial Standards.
Which sectors does MANCAP cover?
According to the head of SON’s MANCAP Division, Engr Ayodele Akinware, the scheme covers six sectors: food; chemicals; electrical and electronics; mechanical products; civil and construction materials; and textiles and leather products.
Receive alerts for product quality standards and more like it.
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – SON Urges Manufacturers to Sustain Product Quality Standards, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:

About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare Dominic

World News
U.S. Sporting Goods Retailers Stack Up: JD, Dick’s, Academy
JD Sports, Dick’s and Academy are the big U.S. sporting goods retailers. Promotions, thin inventory on new styles and a soft consumer define 2026.
Three of the biggest U.S. sporting goods retailers have now described the same trading environment, and the picture is less about demand collapsing than about inventory arriving in the wrong shapes. JD Sports, Dick’s Sporting Goods and Academy Sports + Outdoors each disclosed conditions in recent results and analyst calls, compiled in a WWD industry report. The pressures facing these U.S. sporting goods retailers are expected to persist through the rest of 2026, a forecast rather than a settled outcome.
The distinction matters. Company results and executive statements are confirmed records. Analyst commentary is interpretation. Guidance about the balance of 2026 is projection. This account keeps the three apart.
What JD Sports Confirmed About Running
At JD Sports, the U.S. business absorbed what chief executive Régis Schultz called “weaker core consumer sentiment” on a first-half results call, alongside July back-to-school demand that slipped into the first half of August. Sales of high-heat product slowed and end-of-cycle shoe lines stayed soft.
Two offsets appear in the company’s own account: performance running and new footwear styles. Schultz said running has split into retro running and new running, with On, Hoka, Salomon and the Vomero Plus growing quickly. He also said running clubs and gyms are “becoming the new nightclubs” as health and fitness climb the priority list for JD’s core customer. That is an executive’s characterization, not a measured figure.
Growth in running and related sneaker purchases has offset declines in retro basketball and retro football. JD skews toward footwear with a heavy lifestyle concentration, which is precisely the exposure that turns into a liability when legacy silhouettes stall.
Telsey Advisory Group analyst Cristina Fernández supplied the structural detail. Nike is the number one brand at JD and is expected to remain so, she said, on strength with male shoppers and children. The banner mix does different work: Finish Line reaches women through shop-in-shops at Macy’s, Shoe Palace targets a large Hispanic audience, DTLR posted $875 million in fiscal 2026 sales with footwear at 70 percent, and Hibbett recorded $1.4 billion in 2025, also 70 percent footwear, serving secondary and tertiary markets.
JD is the most premium banner in the group, sited in key cities and A-malls, and its core shopper is the 18-to-24-year-old male. Fernández’s caution is the sharpest line in the material: that consumer “prioritizes fashion and sneakers” but “is under pressure given rising costs.” She also noted JD is New Balance’s biggest wholesale partner globally, with the brand at $9.2 billion in 2025 sales against $3.3 billion in 2020, and lifestyle at 35 percent of its business.
Why U.S. Sporting Goods Retailers Are Split On Footwear
Dick’s Sporting Goods reported second-quarter net income of $315 million, or $3.50 a diluted share, down from $381 million, or $4.71 a share, a year earlier. Net sales rose 53.4 percent to $5.59 billion from $3.65 billion, short of Wall Street’s $5.64 billion expectation. The company also lowered its yearly guidance for Foot Locker.
The report gives no like-for-like breakdown behind that 53.4 percent sales increase and does not detail the Foot Locker guidance cut, so the revenue figure cannot be read as comparable-store growth on this evidence alone.
Executive chairman Ed Stack said at a Goldman Sachs Global Consumer and Retail Conference that conditions across parts of the athletic footwear and apparel market grew increasingly promotional as the quarter progressed, and he expects promotions to continue through the balance of 2026. That is a chairman’s forecast, and it should be treated as one.
Stack’s diagnosis is narrower than “weak demand.” He said Dick’s footwear business is “really very good” and placed the difficulty in the specialty channel, the mall business represented by Foot Locker, which depends more heavily on retro shoe launches. The industry, he argued, holds too much capacity in some legacy product and too little in the new styles consumers want, an imbalance that leaves retailers unable to stock what sells. Nike’s Mind sensory shoe, he said, drew a “terrific” response.
Academy’s Performance Skew And The Hyrox Bet
Academy Sports + Outdoors is the outlier on the evidence. Outdoor is its largest category at 30 percent of sales, and Fernández cited localization, shop-in-shops and assortment mix, Nike, Jordan Brand and Ariat among them, as differentiators. She flagged Ariat’s rise as workwear turned into lifestyle wear, plus a strong performance running mix from Adidas, Nike and Brooks including price points above $200.
Its second-quarter report showed gains in both profit and sales, meeting Wall Street expectations that it would outrun Dick’s and JD Sports. The reason is structural rather than tactical: Academy carries less footwear exposure, and what it sells leans toward performance, running and cleats, rather than the retro lifestyle lines now sitting in oversupply. The network totals 327 stores, with 11 more due to open in the third quarter of fiscal 2026.
On Wednesday, Academy said it would become Hyrox’s official North American partner, activating in Tampa, Dallas, Nashville, Atlanta and Houston ahead of title-sponsoring Hyrox Houston in 2027. This is an announced plan. Commercial terms were not disclosed in the material reviewed.
The Bigger Picture For Global Buyers
For readers outside the United States, the scope of this evidence is narrow. Nothing in the disclosed material covers African retail, sourcing, currency exposure or pricing; the record is three U.S. chains plus one analyst’s coverage. The transferable lesson is about inventory discipline, not about any single brand’s momentum.
The confirmed facts: Dick’s net income fell year on year, Academy posted profit and sales gains, JD grew running while retro basketball and football declined, and promotional intensity increased across parts of the market. The forecasts: an extended promotional cycle into 2026 and Nike holding its position at JD. The capacity imbalance between legacy and new silhouettes is neither confirmed nor forecast. It is a diagnosis offered by a retailer with an interest in the outcome.
For U.S. sporting goods retailers, the 2026 question is not whether shoppers will buy running shoes. It is whether supply can deliver the models they want before the promotional cycle takes the margin.
Frequently Asked Questions
Which three retailers does the report cover?
JD Sports, Dick’s Sporting Goods and Academy Sports + Outdoors, described in the source material as the big box outdoor specialists in the U.S. market.
What did Dick’s Sporting Goods report for the second quarter?
Net income of $315 million, or $3.50 a diluted share, down from $381 million, or $4.71 a share, a year earlier. Net sales rose 53.4 percent to $5.59 billion from $3.65 billion, below Wall Street’s $5.64 billion expectation. The company also lowered its yearly guidance for Foot Locker.
Why is Academy Sports + Outdoors described as the outlier?
According to Telsey Advisory Group analyst Cristina Fernández, Academy has less exposure to footwear than its peers and what it does sell skews toward performance styles such as running and cleats. Its second-quarter report showed gains in both profit and sales, meeting Wall Street expectations that it would outperform Dick’s and JD Sports.
Receive alerts for sporting goods retailers and more like it.
FIRST TIME REACTIONS:
Be the first to leave us a comment – U.S. Sporting Goods Retailers Stack Up: JD, Dick’s, Academy, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare DominicWorld News
DC’s Villainous Green Lantern Sinestro Takes Center Stage
DC’s Lanterns finale trailer puts a villainous Green Lantern, Sinestro, at the centre of the DCU’s cosmic future. What is confirmed, what is forecast.

Sinestro has been placed at the centre of DC’s television universe, and the company is doing it with the closest thing its catalogue offers to a villainous Green Lantern. The trailer for the Lanterns finale, posted on September 28, 2026, sets Aaron Pierre’s John Stewart against Ulrich Thomsen’s Sinestro on an alien planet. The episode airs October 4 on HBO Max.
The confirmed evidence is narrow, and the narrowness is the story. GamesRadar reports the trailer gives Sinestro two lines of dialogue: “The Lantern Corps thinks that fear makes you weak. They couldn’t be more wrong,” and “Fear can be the most powerful force in the universe.”
Earlier official material, catalogued by The Direct, showed Sinestro in a confined prison setting, confronted by Kyle Chandler’s Hal Jordan. Flashbacks tie the two men together as mentor and protege. Thomsen’s casting was confirmed before the show launched; Mark Strong played the same character in the 2011 Green Lantern film.
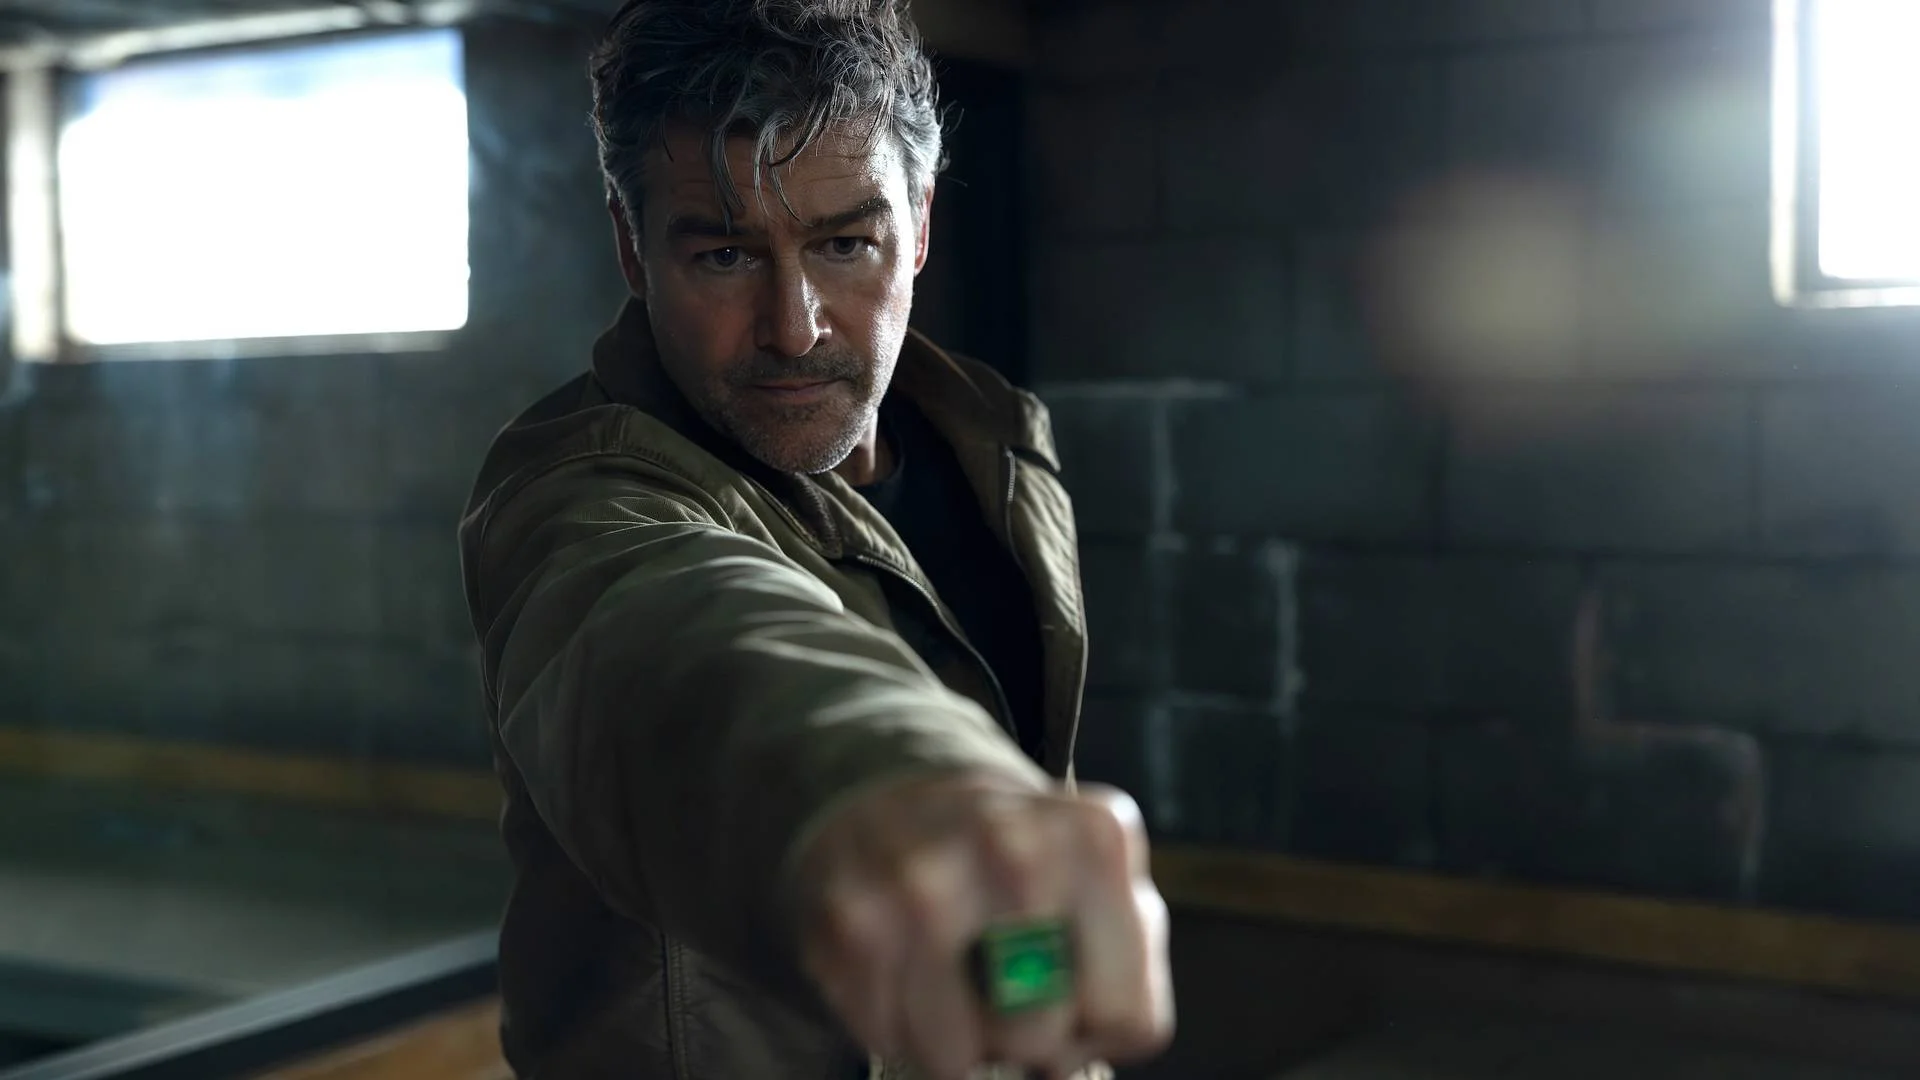
Beyond those frames, almost everything in circulation is forecast. A Sinestro Corps, a Parallax possession, a Legion of Doom: each is extrapolation from comic precedent, not something the show has aired. The distinction matters because the finale trailer resolves a murder mystery — who killed Hal Jordan — and a solved mystery is not the same thing as an announced cosmic antagonist.
How The Villainous Green Lantern Reached The Finale
The timeline is short and checkable. Lanterns premiered on August 16, 2026, according to The Direct, and has run weekly on HBO Max. The finale trailer landed September 28. The finale airs October 4. Between those dates, the only new narrative information released is a conversation on an alien planet and a stated doctrine about fear.
Season two is not confirmed, but it is being built. Showrunner Chris Mundy told The Hollywood Reporter he is several weeks into mapping the next season: “The question is whether [season 2] is a story people are interested in. If that’s the case, then we’ll get to do another one. We’ll tell it in a slightly different way, so that it feels fresh, with characters you know and care about.”
Fear, Succession And The Manhunters Rivalry
Sinestro’s comic history explains why the character reads as a villainous Green Lantern rather than a conventional foe. He became a Yellow Lantern after wielding a power ring that tapped fear, and the fear entity known as Parallax later took over Hal Jordan’s body, causing destruction and death across the galaxy, per GamesRadar.
A competing threat exists. Polygon notes the Manhunters have appeared in Green Lantern comics since the 1970s as the precursors to the Corps, replaced after they rebelled against the Guardians of the Universe. The latest Lanterns episode teased them, and Polygon describes them as “a season-spanning threat” fitting the show’s themes of replacement and succession.
Both candidates are succession stories. Neither has been confirmed as the settled big bad. DC has, in effect, released two competing signals and left the hierarchy unresolved: a villainous Green Lantern in a prison cell and a machine army referenced but not yet shown in full.
What Absolute Green Lantern Says About A Villainous Green Lantern Turn
The comics side offers a cautionary parallel. Bam Smack Pow reports that Absolute Green Lantern No. 16 ended with the debut of Absolute Jessica Cruz, who appeared to side with Mogo, a living planet being used to destroy worlds. It read as a villainous Green Lantern origin.
Issue 17 reversed the reading. Cruz wanted to free Mogo from Thaal’s control, and after Jo Mullein and Tomar-Re destroyed his machine, she touched a dead animal bone on the planet’s surface. Plant life grew, a blue atmosphere formed, and Mogo resembled a planet rather than an instrument of destruction. The apparent turn was a misdirect.
Issue 18 then introduced the Manhunters to that series, written by Al Ewing. The Absolute Universe is built on Darkseid’s design, which is why those antagonists carry different weight there than in the main DC continuity.
That continuity is separate from the HBO show. No verified link joins the Absolute comics line to the screen universe, and treating the two as one storyline is a reader’s assumption, not a studio statement.
For audiences outside the United States, the practical question is distribution rather than lore. HBO Max carriage varies by market, and in territories without the service, the finale’s reach depends on local licensing arrangements that DC has not detailed publicly.
Pierre’s future is clearer than Sinestro’s. He appears in the Superman sequel Man of Tomorrow, and told GamesRadar+ that filming Lanterns first was decisive: “He was like, ‘Congratulations, man. You filmed for 106 days out of 112.’ Just on that note, to have 106 days with a character before going on in the DC cinematic universe is a gift.”
What remains is a company betting that a villainous Green Lantern can carry a franchise without yet showing what he does. The trailer sells a philosophy of fear and a face in a cell. Whether Sinestro becomes the DCU’s defining antagonist, or shares that role with the Manhunters, will be settled by episodes that have not aired.
Frequently Asked Questions
Who plays Sinestro in DC’s Lanterns?
Danish actor Ulrich Thomsen plays Sinestro, per The Direct. Mark Strong played the character in the 2011 Green Lantern film. The finale airs October 4, 2026 on HBO Max.
Has DC confirmed Sinestro as the main villain of the DCU?
No. The finale trailer shows Sinestro confronting John Stewart and stating that fear is the most powerful force in the universe. A Sinestro Corps, Parallax or Legion of Doom storyline has not been announced. Those are forecasts drawn from comic precedent.
What are the Manhunters and why do they matter to Lanterns?
The Manhunters are the precursors to the Green Lantern Corps in DC comics, replaced after rebelling against the Guardians of the Universe. Polygon reports the latest Lanterns episode teased them as a season-spanning threat, and they appeared in the 2011 tie-in game Green Lantern: Rise of the Manhunters.
FIRST TIME REACTIONS:
Be the first to leave us a comment – DC’s Villainous Green Lantern Sinestro Takes Center Stage, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare DominicWorld News
Sunshine Biopharma Reverse Stock Split Set for October 26
Sunshine Biopharma reverse stock split cuts shares 1-for-20 on October 26, 2026, to regain Nasdaq bid compliance. What changes, what does not.
Sunshine Biopharma Inc. will cut its issued share count by 95 percent at the market open on Monday, October 26, 2026, when a one-for-twenty Sunshine Biopharma reverse stock split takes effect.
The Fort Lauderdale, Florida pharmaceutical company, which trades on Nasdaq under the ticker SBFM, announced the move on October 22, 2026. Issued and outstanding common stock falls from 15,219,383 shares to approximately 760,969 shares.
The company gave one reason: to regain compliance with Nasdaq’s minimum bid price requirement for continued listing. That rule sets the price floor a stock must hold to stay on the exchange.
The announcement does not state the share price before or after the split, the date Nasdaq notified the company of any deficiency, or whether a cure period or hearings process came first. Those details are absent from the source material.
What The Sunshine Biopharma Reverse Stock Split Actually Changes
Fifteen million two hundred nineteen thousand three hundred eighty-three divided by twenty is 760,969.15. The company’s stated figure of approximately 760,969 matches that arithmetic, which points to rounding rather than any new issuance of stock.
A reverse split reprices existing equity; it does not raise capital. The share count falls by the same factor the price per share rises, so market value is unchanged by the mechanics alone. What moves is the nominal price Nasdaq measures against its listing standard.
A TradingView summary of the announcement, produced by its automated analyst tool, calls the move a late-stage step to address ongoing bid-price noncompliance and notes that a smaller float can increase price volatility and widen trading spreads. It adds that the outcome depends on the post-split price holding.
That framing is consistent with the company’s own description. It is also a forecast, not a result. No post-split trading data exists yet, and none is contained in either document.
The Evidence Trail Is Short, And That Matters
Two documents describe this corporate action. One is the company’s press release, carried by Yahoo Finance and distributed through ACCESS Newswire. The other is the TradingView summary, which states plainly that it is based on the original press release from Sunshine Biopharma distributed by the same wire.
That means the share figures, the effective date and the compliance rationale trace back to a single disclosure. This report could not verify from the available material whether a separate U.S. Securities and Exchange Commission filing restates the same numbers. Until such a document is examined, the split details rest on the company’s own account.
The release also carries standard safe harbor language covering forward-looking statements about drug development activities, financial performance and future growth, with the company cautioning that actual results could differ materially. That caution applies to the growth claims made in the same release.
The Drug Portfolio Behind The Ticker
According to the announcement, Sunshine Biopharma has 60 generic prescription drugs on the market in Canada and approximately 12 additional drugs scheduled for launch in the remainder of 2026.
The company also describes a proprietary development program with two parts. K1.1 mRNA is an mRNA-lipid nanoparticle targeted at liver cancer. PLpro is a protease inhibitor, described as a small molecule for treating SARS Coronavirus infections.
The release gives no trial phase, enrollment figure, regulatory status or timeline for either program. That gap is significant: the two development candidates are the part of the business most likely to move the share price over time, and the disclosure offers no milestone a reader can date.
For a company whose near-term commercial activity sits in Canadian generics, the split leaves the portfolio, the launch schedule and the development programs untouched. It changes the ticker’s arithmetic only.
What Holders Outside The United States Should Note
For investors in Africa and other regions holding Nasdaq-listed microcaps, a split of this kind is a mechanical adjustment applied to the position and the quoted price at the open, not a change in the underlying security. Access to U.S. microcaps from most African markets runs through brokers offering American market execution.
This report could not verify how individual brokers in the region handle notification or any fractional residue from a one-for-twenty adjustment. Holders should confirm the treatment with their own custodian rather than assume a standard process. The company’s own contact for investor enquiries is its chief financial officer, Camille Sebaaly, listed in the release.
What To Watch After October 26
Three checkpoints sit ahead. The first is whether the post-split price holds above Nasdaq’s minimum bid threshold long enough to satisfy the exchange. The second is whether Nasdaq issues a written compliance determination; the release does not say how or when the company would announce one.
The third is operational. Roughly 12 generic launches are scheduled for the rest of 2026, and the company has flagged no timeline for K1.1 mRNA or the PLpro program. Any disclosure on either front would carry more weight than the share-count change.
Investors can also track the company’s own materials at sunshinebiopharma.com.
The Sunshine Biopharma reverse stock split settles a listing question. It does not settle a revenue question. Only the generic launch cadence and the development milestones can do that, and neither is dated in this announcement.
Frequently Asked Questions
When does the Sunshine Biopharma reverse stock split take effect?
At the market open on Monday, October 26, 2026, according to the company’s announcement of October 22, 2026. The ratio is one new share for every twenty existing shares.
How many shares will Sunshine Biopharma have after the split?
Issued and outstanding common stock falls from 15,219,383 shares to approximately 760,969 shares. That figure is consistent with dividing the existing count by twenty and rounding.
Why is Sunshine Biopharma doing the split?
The company states the split was undertaken to regain compliance with Nasdaq’s minimum bid price requirement for continued listing. The release does not disclose the share price, the date of any Nasdaq deficiency notice, or whether a cure period preceded the decision.
Does the split change the value of the company or its drug business?
No. A reverse split lowers the share count while raising the price per share, so market value is unchanged by the mechanics. The 60 generic prescription drugs on the Canadian market, the approximately 12 planned launches for the rest of 2026, and the K1.1 mRNA and PLpro development programs are unaffected.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Sunshine Biopharma Reverse Stock Split Set for October 26, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare Dominic-

 Startups4 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Health and Fitness1 week ago
Curly Hair Hydration: 5 Proven Steps That Actually Work
-
Trending Entertainment News2 weeks ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News4 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Tech & Gadgets2 weeks ago
Apple Watch and AirPods Fall Deals: Save $120 Today
-
Football4 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
Fintech4 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News
-
Phone Reviews4 weeks ago
iPhone 18 Pro Max Review: Price, Specs, Verdict