Savings & Investing
Nigeria’s Fragmented Crypto Regulation Raises Investment Fears
Nigeria’s fragmented crypto regulation now has a coordinating council. What the filings, flows and gaps mean for investors in 2026.

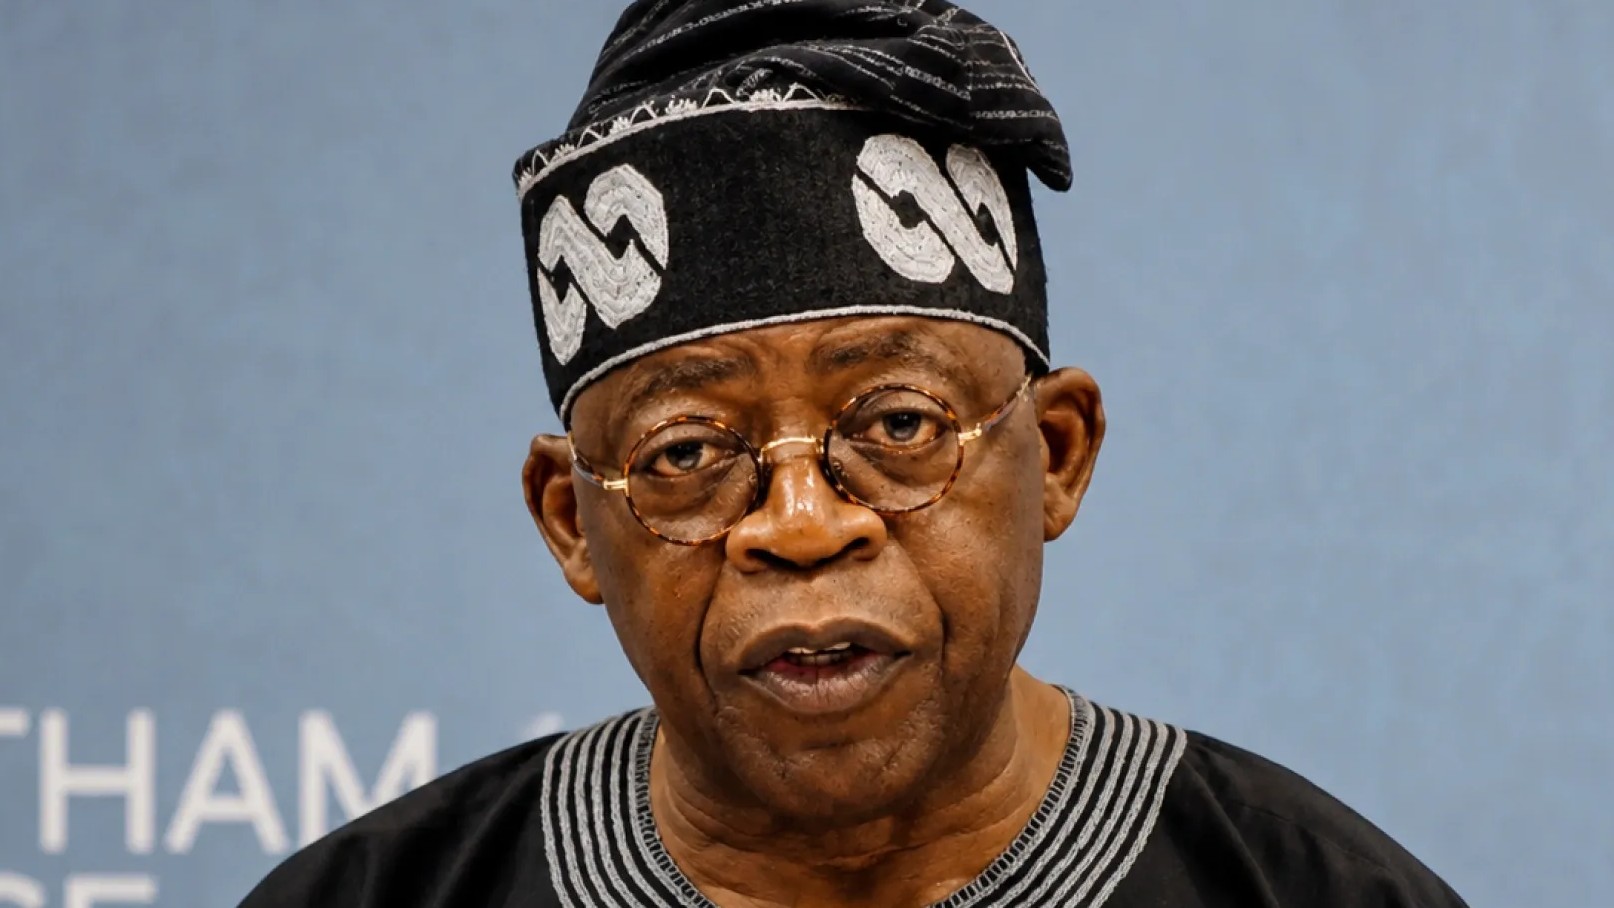
On 17 July 2026, President Bola Ahmed Tinubu signed the Presidential Executive Order on Virtual Assets Coordination, 2026. The order creates a Virtual Asset Council and places the Central Bank of Nigeria, the Securities and Exchange Commission, the Federal Inland Revenue Service and other institutions inside one framework covering the issuance, trading and taxation of virtual assets. Nigeria’s fragmented crypto regulation is the specific problem the order was written to address.
Read it as a coordination document. It changes which agency talks to which, and under what heading. It does not set a price, a yield, or a floor beneath any token.
What The 2026 Executive Order Actually Changes
The council holds a mandate covering strategic policy direction, coordination among the agencies, and work with the Attorney-General on a harmonised legal and institutional framework. Capmad reports that federal authorities frame the goal as closing loopholes used by fraudulent operators. A parallel set of measures applies Nigeria’s tax laws to virtual assets, so gains and income from crypto are treated with more certainty for taxpayers and service providers.
The history explains the urgency. The CBN instructed banks in 2021 to close accounts linked to crypto platforms. In 2023 it shifted towards oversight, issuing a framework for virtual asset service providers. Between those two positions, activity moved to peer-to-peer platforms that no comprehensive rule covered, a sequence Guardian Nigeria traces through successive CBN and SEC circulars dating to 2017.
The IMF had already recommended a joint monitoring framework across monetary, market and anti-money-laundering authorities. Its staff noted that supervision remained fragmented and that information sharing between agencies was limited.
Risk, Diversification, Liquidity And Minimum Ticket Sizes
Risk sorts into four buckets, and it belongs before any discussion of upside.
Issuer and credit risk. A tokenised bond is still a promise from a borrower. Recording that promise on a blockchain does not make the borrower solvent.
Technology and settlement risk. Nigeria’s digital securities platform runs issuance, trading, clearing and settlement on infrastructure supplied by Canadian firm Blockstation. Cutting days out of settlement cuts counterparty exposure. It does not cut the possibility of an operational failure.
Regulatory risk. Nigeria’s recent record includes a directive that closed bank accounts. An executive order can be revised, and the Virtual Assets White Paper meant to fix the long-term trajectory is still in preparation.
Diversification. One tokenised instrument from one SME is a single credit, not a portfolio. Fractional ownership widens access to a holding; it does not spread default risk across issuers.
Liquidity. Near-instant settlement is not a deep order book. NASD listed 46 securities as of May. Thin trading means an exit can move the price.
Minimum investment. The source material does not publish minimum ticket sizes for the September digital securities offering. Fractional ownership is described as lowering entry barriers, which implies small units, but no figure has been disclosed. Until an offer document states a minimum, treat ‘low minimum’ as unverified.
Nigeria’s Fragmented Crypto Regulation Meets A Tokenised Market
The SEC has approved trading of tokenised shares and bonds on the NASD OTC Securities Exchange, with a first public offering of digital securities scheduled for early September. Licensed brokers continue to execute trades under SEC supervision, and the exchange says SMEs are the primary audience. Acting CEO Chinwendu Ekeh calls the platform a faster, lower-cost pathway to market financing.
Why SMEs. A May 2025 Stears study found that only about 4% of Nigeria’s estimated 40 million MSMEs have access to formal bank credit. Tokenised issuance offers a route for companies too small or too early-stage for a main listing.
The scale question. NASD’s market capitalisation more than doubled in 2025 to ₦2.12 trillion, roughly $1.56 billion, from ₦1.03 trillion the year before. That is real growth from a small base.
The legal perimeter. The Investments and Securities Act 2025 gives the SEC authority over digital assets that qualify as securities, while the CBN keeps oversight of payment systems. cNGN, a naira-backed stablecoin, was issued under that Act. Financial Nigeria reports the Virtual Assets Council is chaired by the CBN.
What The Verified Figures Show, And What They Omit
Nigeria ranks among the world’s largest digital-asset markets by volume, with annual flows estimated at around $59 billion over a recent period, according to IMF staff cited in the presidential communication.
Ivorypay reported processing more than $80 million in cryptocurrency payments over the preceding year and onboarding over 9,000 merchants across several African markets by the time its Duffle app launched in Nigeria in April 2025. Those are volume and merchant counts. They are not revenue, margin or default figures, and none were disclosed.
Charles Olanrewaju, head of operations at Ivorypay, described the operational constraint plainly: ‘The product can be shared, but the operation underneath it cannot.’ On automation his rule is: ‘automate the rule, keep a person on the exception.’ The Guardian Nigeria account of his work makes the same point about licensing and settlement differences across borders.
Continental direction. The Nairobi Securities Exchange signed a memorandum with Tether in July to pilot tokenisation and instant settlement. The Central Bank of West African States convened regulators, bankers and academics in Dakar in May. South Africa’s Financial Sector Conduct Authority has been reviewing tokenised-asset frameworks.
What is missing. For all the coordination, Nigeria’s fragmented crypto regulation still lacks a published fee schedule for tokenised trades, a date for the White Paper, and an enforcement record for the Council. Days before the executive order, the communications minister suspended new cross-cutting rules from the NCC, NITDA and NDPC pending a consolidated digital governance framework, a reminder that the wider rulebook is also in motion.
Verdict: A Framework, Not A Recommendation
The order removes one category of risk: the chance that two regulators issue conflicting instructions to the same business. Market, credit, technology and liquidity risk sit exactly where they were.
Nigeria’s fragmented crypto regulation is being assembled into something with an address and a chair. That is progress for disclosure. It is not evidence of a return, and no agency statement reviewed here promises one. The documents worth watching are the September NASD offer document, the Virtual Assets White Paper, and the Council’s first enforcement actions.
This article is information, not personal financial advice. Any position in digital assets or tokenised securities should follow independent reading of the offer document, an honest assessment of your time horizon and capacity to absorb loss, and, where appropriate, guidance from a licensed professional.
Frequently Asked Questions
Does the 2026 executive order make crypto investing in Nigeria safe?
No. It creates a Virtual Asset Council to coordinate the CBN, SEC, FIRS and other agencies, and it adds tax clarity. Market volatility, issuer default, technology failure and thin liquidity are unchanged. Coordination reduces one kind of regulatory risk, not investment risk.
What is the minimum amount needed to buy tokenised securities on NASD?
No minimum has been published in the source material. Fractional ownership is described as lowering entry barriers, which suggests small units, but investors should wait for the September offer document before assuming any figure.
How liquid is the NASD digital securities market?
Settlement is near-instant on the blockchain platform, but settlement speed and liquidity are different things. NASD listed 46 securities as of May, a small universe where an exit can move prices.
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – Nigeria’s Fragmented Crypto Regulation Raises Investment Fears, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:

About Paul Nwogo
Paul Nwogo is an engineer, published author, and the Head Manager at AfriLatest. He has written numerous books available on Amazon covering a diverse range of topics, including health, personal finance, relationships, work ethics, and scam survival. With his technical background and passion for writing, Paul now oversees the editorial direction of AfriLatest, delivering practical, accurate, and engaging content on trending news, music, and global lifestyle topics.
View all articles by Paul Nwogo

Savings & Investing
NGX Tech Stocks: eTranzact’s 10% Jump Versus MTN
NGX tech stocks: eTranzact rose 10% on N18.67m turnover while MTN traded N1.01bn flat. A comparison of risk, ticket size and exit.
Two choices sat on the same board on the same afternoon, and they tell opposite stories about ngx tech stocks.
eTranzact International closed Thursday, October 29, 2026 at N17.60, up 10 percent, adding N1.60 to a previous close of N16. It traded 1.07 million shares worth about N18.67 million. MTN Nigeria closed flat at N825 on 1.24 million shares worth roughly N1.01 billion, the highest transaction value among the eight technology and telecommunications companies reviewed that session, according to Nairametrics.
One stock moved a lot on little money. The other moved nowhere on a great deal of money. That gap is the real subject of this comparison, not the 10 percent in the headline.
Four Things To Settle Before Any Return Talk
Risk is the chance of losing part of your capital permanently, not the size of a single day’s price move. A stock that rises 10 percent on thin turnover can fall the same way next week.
Diversification means spreading money so that one company’s failure does not decide your outcome. Holding one small-cap technology name is not diversification, however promising the sector looks.
Liquidity is how much you can sell without pushing the price down. It is measurable. eTranzact’s N18.67 million of turnover against MTN’s N1.01 billion is a liquidity comparison, not a popularity contest.
Minimum investment is the price per share multiplied by whatever lot or broker minimum applies. One eTranzact share cost N17.60 that day. One MTN Nigeria share cost N825. One Airtel Africa share cost N6,300. A fixed budget therefore buys very different share counts, and any fixed per-trade charge eats a larger slice of a small ticket than a large one.
Why The NGX Tech Stocks Board Looks Uneven Over One Session
Eight stocks were tracked. eTranzact led with 10 percent, Legend Internet added 1.47 percent to N3.45, Chams rose 0.30 percent to N3.33 on 6.41 million shares, and Omatek fell 0.74 percent to N1.35. MTN Nigeria, Airtel Africa, Computer Warehouse Group and NCR Nigeria all closed unchanged.
The All-Share Index rose 1,200.24 points, or 0.47 percent, to 254,083.02, with N57.36 billion traded across 35,821 deals. eTranzact’s N18.67 million was roughly 0.03 percent of that value. A 10 percent gain on a rounding error of market turnover is what thin trading produces; it is not a verdict on the business.
The session before had gone the other way. The index fell 0.44 percent to 252,882.78 on Wednesday, October 28, wiping N718.95 billion off market capitalisation. Two consecutive sessions, two opposite headlines, no new information about any company’s earnings.
Reading eTranzact Against MTN Nigeria On Fundamentals
eTranzact recently changed hands at the top. Trademarks Global Concepts Limited acquired a 56.18 percent stake, and board changes followed. No 2026 earnings figures appear in the trading report, so the 10 percent move cannot be tied to any disclosed result in the material reviewed.
The last detailed numbers in that body of coverage are older. Technext recorded a half-year 2023 profit of N1.01 billion, up 149 percent from N408 million, on revenue of N17.37 billion, itself up 49.37 percent. The share price moved from N3.50 to N7.40 between the start of that year and November 22, 2023. On quoted figures, without adjusting for corporate actions the sources do not mention, that N7.40 compares with N17.60 on October 29, 2026.
The longer record carries a warning. A 2019 company profile documented a N3.1 billion loss after tax for full-year 2018 against a N208 million profit in 2017, after First Bank of Nigeria reported an N11.49 billion fraud on the Fundgate platform on March 8, 2018. The Central Bank of Nigeria later directed that the net liability be split equally at N5.75 billion each, with N5.95 billion recovered from Smart Micro Systems shared the same way. The CBN also ordered the removal of the chief executive and two directors. Free float stood at 10.06 percent then, below the 20 percent main-board requirement. The trading report does not give a current free-float figure.
MTN Nigeria’s session data says only that buyers and sellers met at N825 in size. A dated description in the same coverage notes more than 70 million subscribers, which speaks to scale rather than to valuation. Nothing in the source material supports a claim that either stock is cheap or expensive.
Legend Internet shows why price and profit diverge. Its results for the year ended July 2026 put profit down 90.73 percent to N13.21 million and revenue down 7.44 percent to N1.10 billion, with borrowings up to N1.14 billion from N75.23 million. Its shares still gained 1.47 percent on October 29 and lost 5.80 percent in an earlier session reported by Investors King.
Costs, Exit And Who Each Stock Suits
Brokerage commission, exchange and clearing charges, and the spread between bid and offer all apply. On a N20,000 position, a minimum fee is a larger percentage drag than on a N2 million position. That arithmetic favours larger tickets and penalises small, frequent trades in any ngx tech stocks holding.
Exit is the second cost. Selling N18.67 million worth of eTranzact in a day took a full session. Selling N1.01 billion of MTN Nigeria also took a session, but at far greater depth. An investor who may need the money within a year is exposed to whatever price the order book offers on the day.
A small saver putting in irregular amounts should weigh ticket size and exit before a leaderboard. A shareholder who can hold through drawdowns and read filings should weigh ownership concentration, governance history and disclosed profit. Neither path is free of risk, and past price movement does not predict the next one.
For a first-time buyer with limited capital, the flat, heavily traded stock is the easier instrument to enter and leave, at the cost of a high price per share. For a buyer already diversified and willing to accept wide price swings, the smaller payments company is a concentrated bet whose case must rest on dated filings, not on a single 10 percent Thursday.
This article is general information, not financial advice. It does not recommend buying or selling any security. Prices and figures are as reported for the dates cited and change daily. Consult a licensed stockbroker or adviser before investing.
Frequently Asked Questions
Does a 10 percent one-day gain mean eTranzact is a good investment?
No. The 10 percent figure describes one closing price against the previous close on October 29, 2026. It does not measure the company’s profit, its cash flow or its valuation, and no 2026 earnings were cited in the trading report. A single session’s move is a price event, not a return.
Why does liquidity matter more than the percentage gain for small investors?
Liquidity determines whether you can sell at a fair price when you need the money. eTranzact traded about N18.67 million of value that day; MTN Nigeria traded about N1.01 billion. A thin order book means a sell order can move the price against you, which turns a paper gain into a smaller realised one.
What is the minimum amount needed to buy these NGX tech stocks?
The source material gives share prices, not broker minimums. One eTranzact share closed at N17.60 and one MTN Nigeria share at N825 on October 29, 2026, with Airtel Africa at N6,300. Actual minimums depend on your broker’s board lot and fee schedule, so the cash outlay must be confirmed with a licensed dealer.
FIRST TIME REACTIONS:
Be the first to leave us a comment – NGX Tech Stocks: eTranzact’s 10% Jump Versus MTN, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Paul Nwogo
Paul Nwogo is an engineer, published author, and the Head Manager at AfriLatest. He has written numerous books available on Amazon covering a diverse range of topics, including health, personal finance, relationships, work ethics, and scam survival. With his technical background and passion for writing, Paul now oversees the editorial direction of AfriLatest, delivering practical, accurate, and engaging content on trending news, music, and global lifestyle topics.
View all articles by Paul NwogoSavings & Investing
Hidden Medicare Fees Draining Your Retirement Savings
Hidden Medicare fees, IRMAA surcharges and tax drag quietly drain retirement savings. See the 2026 figures and the steps that limit the damage.

The goal is to find the money that leaves a retirement account every month without ever appearing on a household budget line, and to price it before it compounds. In the United States the largest of those leaks are hidden Medicare fees: income-linked surcharges bolted onto Part B and Part D premiums, plus a tax drag that bills investment returns before they can compound. The arithmetic is unforgiving, and it is not purely American. A household planning in Lagos or London meets the same structure, a health cost rising faster than the income that must pay for it.
The figures are now specific enough to audit. The 2026 standard Medicare Part B premium is $202.90 a month, confirmed by the Centers for Medicare & Medicaid Services in November 2025. The surcharge that sits on top of that number is where most retirement budgets break.
Where The Hidden Medicare Fees Hide
The Income-Related Monthly Adjustment Amount behaves as a cliff, not a slope. In 2026, single filers whose 2024 income exceeded $109,000, and married couples above $218,000, fall subject to the surcharge. A single filer one dollar over that line moves from $202.90 to $284.10 a month for Part B, an extra $974.40 a year on the published figures, which the reporting rounds to nearly $1,000. At the top income tier the same premium reaches $689.90 a month.
The mechanism runs on a two-year look-back, and that is the detail retirees most often miss. Someone enrolling at 65 has premiums set by income earned at 63, a period when a salary, a bonus or a business sale may still have been running. The floor is equally unforgiving in the other direction: a married couple drawing $200,000 in retirement income pays nothing extra until one spouse dies, at which point the survivor is assessed against the single threshold of $109,000 and can be pushed into a surcharge by the same income that was previously exempt.
The Lifetime Bill That Sits Beside The Nest Egg
Premiums are only the visible layer. The HealthView Services 2026 Retirement Healthcare Costs Data Report projects that an average 65-year-old couple retiring in 2026 will pay $688,996 in Medicare premiums across their lifetimes. Add hearing care, vision care, copays, deductibles and dental care, and the total averages $955,411. That is a second retirement to fund, and it is usually absent from the balance sheet households build around their savings.
The escalation rate explains why. Health-related cost inflation is projected at 5.6% long term, while Social Security cost-of-living adjustments have run at 2.8% for 2026, with a 3.6% adjustment determined for 2027 on 14 October 2026. Healthcare costs are therefore climbing at roughly twice the rate of the benefit index meant to keep pace with them, a gap that widens every year of a twenty-year retirement.
Scale sharpens the point. In a 2025 BlackRock survey, Americans put the figure needed for a comfortable retirement at $2.09 million on average, a target the firm’s chief executive, Larry Fink, noted was higher than expected and beyond almost everyone’s reach. Roughly 51% of Americans expect to outlive their savings, according to Northwestern Mutual research, while life expectancy is projected to reach 80.4 years for all sexes by 2050. A longer life against a faster-inflating health cost is the whole problem in one sentence.
Where The Tax Drag Quietly Compounds
A taxable brokerage account is billed whenever a dividend or a capital gains distribution arrives, even if no share is ever sold. Each payment interrupts compounding, and over decades the interruption matters more than the tax rate. For older investors the drag is smaller in absolute terms but lands at the exact moment withdrawals begin.
Roth accounts change the equation twice over. Qualified withdrawals from a Roth IRA or Roth 401(k) are free of tax, including tax on dividends and capital gains distributions, and they are excluded from the income calculation that sets the surcharge. Health savings accounts are treated similarly when withdrawals cover qualified medical expenses, which makes them the only account type that is tax-free going in, tax-free growing and tax-free coming out for care.
There is a trap attached to the HSA. Contributions must stop once enrolment in Medicare begins, and where enrolment is delayed past 65, contributions must cease up to six months before enrolling in Part A or claiming Social Security.
Roth conversions carry a matching trade-off. Moving money from a traditional IRA to a Roth raises income in the year of conversion, which lifts that year’s tax bill and can trigger a surcharge two years later. The manoeuvre can be correct for some households and wrong for others, which is why the source material directs the undecided to a tax professional or financial adviser rather than to a rule of thumb.
Reading A $1,500,000 Plan As A Fee Audit
The clearest evidence of how fees carve up a withdrawal comes from a worked case. A single 64-year-old holding $1.5 million across a traditional 401(k), a taxable account and a Roth IRA applies the 4% guideline and draws roughly $60,000 gross in year one. Federal and state tax on a pretax withdrawal of that size lands near $8,000, against a 2026 single-filer standard deduction of $16,100 and a 12% bracket running to $50,400.
Pre-Medicare coverage then takes its cut. Marketplace premiums plus out-of-pocket costs commonly reach $11,000 for a single 64-year-old in the year before eligibility, compared with the $202.90 monthly Part B standard once Medicare begins. Inflation erodes roughly $4,000 of the fixed portion. What remains is about $37,000 of real discretionary spending, which is a long way from what $1.5 million appears to promise on paper.
At 67 the mathematics softens. A Social Security benefit of about $36,000 a year arrives, carrying a built-in inflation adjustment the portfolio cannot replicate, and the 4% draw problem becomes roughly a 2% draw problem.
A Naira Household Faces The Same Shape
Nigeria operates no equivalent of the surcharge table, since there is no national Medicare premium to which an income test could be attached. The structural leak is different, but its direction is identical. Private cover, renewals and out-of-pocket hospital bills are paid from income that does not carry an indexation mechanism, while medical inflation keeps climbing at the pace described above.
A purely illustrative naira calculation shows the scale without asserting any market figure. If a retirement health plan rises by ₦8,000 a month, ₦96,000 a year leaves the drawdown budget before a single hospital bill arrives, and that sum is removed from capital that would otherwise compound.
Relocation does not solve it either. A retiring household trading one tax regime for another can still lose the difference to housing and care costs, as the Florida case shows: owners of a $425,000 Miami home pay $617 a month in association fees, property tax assessments reset to market rate on purchase, and the state records just 17 personal care and home health aides per 1,000 adults aged 65 and older against a national average of 65. A tax advantage is one line of a budget, not the budget itself.
Steps For Plugging The Leaks
The first step is reconstruction. A household approaching 65 should pull the tax return filed two years earlier and write the modified adjusted gross income figure next to the published surcharge thresholds. That single comparison reveals whether a premium is being set by the current budget or by an old pay slip.
The second step is placement. Income-generating holdings belong in accounts whose distributions and qualified withdrawals stay outside the surcharge calculation, which is where the Roth and the health savings account earn their keep. The third is a cash buffer of two to three years of planned spending, held in short-dated instruments so that equities are never sold into a downturn to fund a premium.
Fourth, conversions belong in the bridge years, when wages have stopped and Social Security has not started, and they must be sized against the surcharge threshold rather than the tax bracket alone. Fifth, ask for a lifetime health cost projection rather than an annual premium quote, because a single year of premium tells a household almost nothing about a twenty-year liability.
The pitfalls are consistent. Treating the first premium as permanent, contributing to a health savings account after Medicare enrolment, and modelling only the married scenario all produce budgets that fail in year three rather than year one.
What To Do This Week
One action step matters more than the rest. Before the next enrolment window closes, a household should write its two-year-old income, its projected health costs to age 90 and its current premium on one page, then compare that page with the plan it is actually funding. Most hidden Medicare fees are legal, disclosed and avoidable in part, but only for households that have priced them in advance. Nothing here is individualized advice; it is general education, and any conversion, withdrawal or account decision should be checked with a licensed tax professional or adviser against a reader’s own numbers.
Frequently Asked Questions
What is the IRMAA surcharge and how large is it in 2026?
The Income-Related Monthly Adjustment Amount is an extra charge added to Medicare Part B and Part D premiums for higher-income retirees. In 2026 a single filer with 2024 income above $109,000, or a married couple above $218,000, is subject to it. A single filer just over the line pays $284.10 a month instead of the $202.90 standard for Part B, roughly $974 more a year, and the top tier reaches $689.90 a month.
Why does the surcharge use income from two years earlier?
The government applies a two-year look-back, so premiums at 65 are set by income earned at 63. A salary, bonus or business sale in that earlier year can therefore raise premiums in the year of enrolment, even if income has since fallen. A surviving spouse can also be pushed into the surcharge because the same retirement income is then tested against the single threshold.
How can a household legally reduce the impact?
Qualified Roth withdrawals are excluded from the surcharge income calculation, and health savings account withdrawals for qualified medical costs are treated similarly, provided contributions stop before Medicare enrolment. Roth conversions made in bridge years before Social Security starts can help if they are sized against the surcharge threshold, but they raise income in the conversion year and can lift the premium two years later, so professional guidance is required.
Receive alerts for hidden Medicare fees and more like it.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Hidden Medicare Fees Draining Your Retirement Savings, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Paul Nwogo
Paul Nwogo is an engineer, published author, and the Head Manager at AfriLatest. He has written numerous books available on Amazon covering a diverse range of topics, including health, personal finance, relationships, work ethics, and scam survival. With his technical background and passion for writing, Paul now oversees the editorial direction of AfriLatest, delivering practical, accurate, and engaging content on trending news, music, and global lifestyle topics.
View all articles by Paul NwogoSavings & Investing
Global X Russell 2000 Covered Call ETF Declares $0.21
Global X Russell 2000 Covered Call ETF declares CAD $0.21 per unit for an Oct 30 record date. What the filing says — and what it does not.

Global X Investments Canada Inc. put a number on the table: CAD $0.21000 per security for the Global X Russell 2000 Covered Call ETF, ticker RSCC on CBOE. The ex-date and record date are 30 October 2026. The pay date is 6 November 2026. Holders take cash, or reinvested units if they are enrolled in the fund’s distribution reinvestment plan.
The number is precise. Its meaning is narrower than it looks.
A distribution declaration is an administrative event. It tells a holder how much cash leaves the fund per unit on a set date. It says nothing about whether the fund made money, nothing about the yield a new buyer would earn over the next twelve months, and nothing about the direction of the unit price.
Nothing moved on this news, and that is the correct reaction. The same October 2026 notice carries dozens of tickers, many declaring identical amounts on identical dates across monthly and semi-monthly schedules. It is a calendar release, not a market event.
Why the Global X Russell 2000 Covered Call ETF Payout Is Not a Yield
RSCC sits inside a suite that Global X markets as solutions for a range of market conditions. The mechanical part is the covered call structure. The fund holds a portfolio tied to the Russell 2000 small-cap universe and writes call options against it. Option premiums arrive as cash. In exchange, the fund surrenders part of the upside when small caps rally hard.
That trade has a signature. Income is steadier than the underlying index. Appreciation is capped in strong markets. Downside is not removed — a fall in small caps still flows into the unit price, less whatever premium was collected.
When the ex-date passes, the distribution is typically reflected as a reduction in net asset value per unit. A holder who receives CAD $0.21000 and watches the price fall by a comparable amount has gained nothing that day. Total return, price change plus distributions, is the measure that matters. The notice does not supply it.
The filing also discloses no net asset value, no assets under management for this specific fund, and no yield figure. Anyone quoting a yield from this press release is calculating it off an outside price source, not off the filing.
Why the Enhanced Line Pays More Per Unit
The same table carries RSCL, the Global X Enhanced Russell 2000 Covered Call ETF, at CAD $0.34000 per security, on the same dates and the same exchange.
The higher figure invites an obvious but wrong conclusion: that the enhanced version is the better product. Global X’s own cautionary language covers the gap. The company states that certain funds may use leveraged investment techniques that magnify gains and losses, producing greater volatility, and that those risks are described in the prospectus.
Leverage applied to a covered call strategy on small-cap equities does two things at once. It lifts the cash distribution per unit. It also enlarges the drawdown when the trade turns. The distance between $0.34 and $0.21 is compensation for risk, not a free upgrade.
Two further details sit in the filing. Global X states plainly that distributions for the ETFs will vary from period to period. And the table lists both RSCC and its RSCC.U line at CAD $0.21000, with currency shown as CAD on both rows — a designation holders should confirm against the fund’s own documents before assuming what settles in the account.
What the Filing Leaves Out, and Where Nigeria Fits
Two structural differences separate a Canadian listed fund from what a Lagos-based investor can reach.
The first is product availability. The Nigerian Exchange listed ETF range remains built around index trackers and commodity funds. A covered call wrapper, which depends on a functioning listed options market underneath it, is not part of that line-up. A Nigerian investor seeking this exposure is buying a foreign-listed security, which brings a brokerage with CBOE access, foreign currency funding, and the naira-to-funding-currency spread into the return calculation.
The second is currency. These distributions are declared in CAD. Naira outcomes depend on the exchange rate on the conversion date, and that rate can move further in a month than a monthly distribution pays.
Minimum investment amounts follow from the same set of facts. The notice gives no unit price, so the cash outlay for a single unit cannot be computed from the release. One unit is the practical minimum on an exchange, and a reinvestment plan only helps holders who already own enough for it to matter. For a Nigerian buyer, the effective minimum is set as much by brokerage floors and conversion costs as by the unit price. Small positions get eaten by friction before they compound.
Scale is worth noting but proves nothing about safety. Global X reports more than $55 billion in assets under management and more than 160 ETFs listed on major Canadian exchanges, and is a wholly-owned subsidiary of Mirae Asset Financial Group, which manages over $1 trillion across 21 countries. Size does not underwrite a small-cap option overlay.
The Dates That Actually Bind
Trading on or after the ex-date of 30 October 2026 does not carry the October distribution. Payment follows on 6 November. The November declaration, the next real data point, is not in this release.
For a holder, the framework is rolling. A monthly distribution means monthly re-pricing of income. One CAD $0.21000 figure says nothing about twelve months of cash flow, which is why the variation clause carries more weight than the headline number.
Investor Takeaway
The Global X Russell 2000 Covered Call ETF declaration is verifiable and specific: CAD $0.21000 per unit, ex-date 30 October 2026, pay date 6 November 2026, CBOE. Everything an investor actually needs — yield, NAV behaviour, total return, the effect of the option overlay on a small-cap drawdown — sits outside the notice, in the prospectus and the fund’s financial reporting. Treat the announcement as a calendar entry. Size positions against total return rather than against the distribution, and read the $0.21 and the $0.34 as amounts declared for one period, not promises about the next.
Nothing here is personalized financial advice. Global X states that the funds are not guaranteed, their values change frequently, and past performance may not be repeated. Covered call and leveraged strategies can lose money.
Frequently Asked Questions About Global X Russell 2000 Covered Call ETF
How much is the Global X Russell 2000 Covered Call ETF distribution for October 2026?
The notice declares CAD $0.21000 per security for RSCC, with an ex-date and record date of 30 October 2026 and a pay date of 6 November 2026. Payment is in cash, or reinvested units for holders enrolled in the fund’s distribution reinvestment plan.
Is RSCL the same fund as RSCC?
No. RSCL is the Global X Enhanced Russell 2000 Covered Call ETF, declared at CAD $0.34000 per security on the same ex-date and pay date. Global X states that certain funds may use leveraged investment techniques that magnify gains and losses, which increases volatility. The higher distribution per unit is not evidence of a better return.
Does the distribution notice tell me the fund’s yield?
No. The release discloses the cash amount per security, the ex-date and record date, the pay date, the currency and the exchange. It does not state the fund’s net asset value, its assets under management, or a yield. Global X notes that distributions will vary from period to period, so a single month cannot be annualised into a reliable income figure.
Can a Nigerian investor buy this ETF directly on the NGX?
No. The security is listed on CBOE in Canada. Reaching it from Nigeria requires a brokerage with access to that exchange plus foreign currency funding, which introduces conversion costs and exchange-rate risk into the return. A covered call structure of this kind is not part of the Nigerian Exchange’s listed ETF range.
Receive alerts for Global X Russell 2000 Covered Call ETF and more like it.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Global X Russell 2000 Covered Call ETF Declares $0.21, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Paul Nwogo
Paul Nwogo is an engineer, published author, and the Head Manager at AfriLatest. He has written numerous books available on Amazon covering a diverse range of topics, including health, personal finance, relationships, work ethics, and scam survival. With his technical background and passion for writing, Paul now oversees the editorial direction of AfriLatest, delivering practical, accurate, and engaging content on trending news, music, and global lifestyle topics.
View all articles by Paul Nwogo-

 Car Reviews2 weeks ago
1955 Chevy Bel Air Restomod: What SEMA Really Proves
-
Savings & Investing3 weeks ago
Hidden Medicare Fees Draining Your Retirement Savings
-
Car Reviews4 weeks ago
Ford Bronco ORV Package: $18,995 Ownership Reality Check
-
JAMB & WAEC4 weeks ago
JAMB Admission Process: What Changed And What Is Still Talk
-
Movies & TV4 weeks ago
Silo Season 1 Ending Explained: What the Showrunner Said
-
Movies & TV3 weeks ago
Wizkid Starboy Desire Ft Banky W Shaydee: Fact Or Fan Fiction?