World News
U.S. Sporting Goods Retailers Stack Up: JD, Dick’s, Academy
JD Sports, Dick’s and Academy are the big U.S. sporting goods retailers. Promotions, thin inventory on new styles and a soft consumer define 2026.

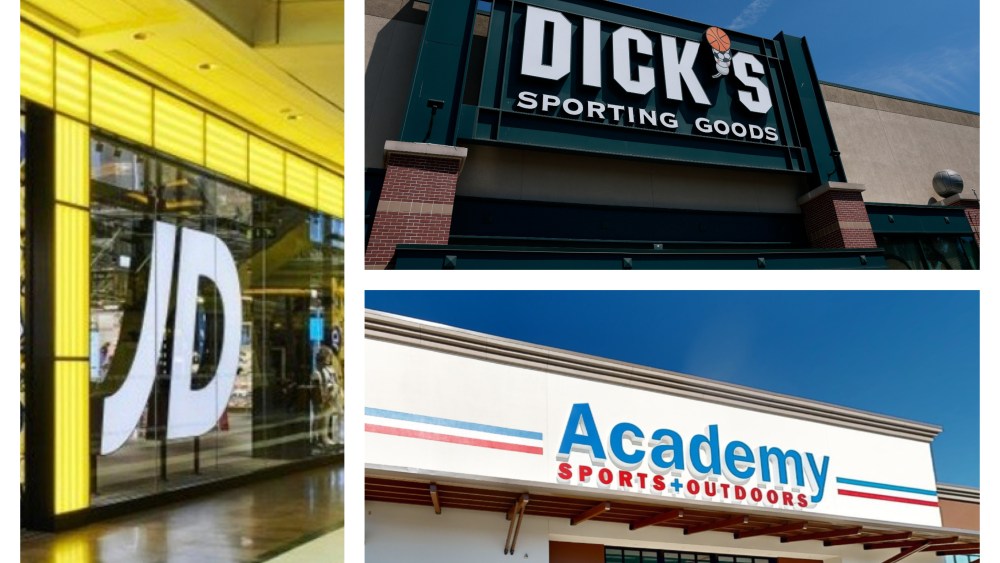
Three of the biggest U.S. sporting goods retailers have now described the same trading environment, and the picture is less about demand collapsing than about inventory arriving in the wrong shapes. JD Sports, Dick’s Sporting Goods and Academy Sports + Outdoors each disclosed conditions in recent results and analyst calls, compiled in a WWD industry report. The pressures facing these U.S. sporting goods retailers are expected to persist through the rest of 2026, a forecast rather than a settled outcome.
The distinction matters. Company results and executive statements are confirmed records. Analyst commentary is interpretation. Guidance about the balance of 2026 is projection. This account keeps the three apart.
What JD Sports Confirmed About Running
At JD Sports, the U.S. business absorbed what chief executive Régis Schultz called “weaker core consumer sentiment” on a first-half results call, alongside July back-to-school demand that slipped into the first half of August. Sales of high-heat product slowed and end-of-cycle shoe lines stayed soft.
Two offsets appear in the company’s own account: performance running and new footwear styles. Schultz said running has split into retro running and new running, with On, Hoka, Salomon and the Vomero Plus growing quickly. He also said running clubs and gyms are “becoming the new nightclubs” as health and fitness climb the priority list for JD’s core customer. That is an executive’s characterization, not a measured figure.
Growth in running and related sneaker purchases has offset declines in retro basketball and retro football. JD skews toward footwear with a heavy lifestyle concentration, which is precisely the exposure that turns into a liability when legacy silhouettes stall.
Telsey Advisory Group analyst Cristina Fernández supplied the structural detail. Nike is the number one brand at JD and is expected to remain so, she said, on strength with male shoppers and children. The banner mix does different work: Finish Line reaches women through shop-in-shops at Macy’s, Shoe Palace targets a large Hispanic audience, DTLR posted $875 million in fiscal 2026 sales with footwear at 70 percent, and Hibbett recorded $1.4 billion in 2025, also 70 percent footwear, serving secondary and tertiary markets.
JD is the most premium banner in the group, sited in key cities and A-malls, and its core shopper is the 18-to-24-year-old male. Fernández’s caution is the sharpest line in the material: that consumer “prioritizes fashion and sneakers” but “is under pressure given rising costs.” She also noted JD is New Balance’s biggest wholesale partner globally, with the brand at $9.2 billion in 2025 sales against $3.3 billion in 2020, and lifestyle at 35 percent of its business.
Why U.S. Sporting Goods Retailers Are Split On Footwear
Dick’s Sporting Goods reported second-quarter net income of $315 million, or $3.50 a diluted share, down from $381 million, or $4.71 a share, a year earlier. Net sales rose 53.4 percent to $5.59 billion from $3.65 billion, short of Wall Street’s $5.64 billion expectation. The company also lowered its yearly guidance for Foot Locker.
The report gives no like-for-like breakdown behind that 53.4 percent sales increase and does not detail the Foot Locker guidance cut, so the revenue figure cannot be read as comparable-store growth on this evidence alone.
Executive chairman Ed Stack said at a Goldman Sachs Global Consumer and Retail Conference that conditions across parts of the athletic footwear and apparel market grew increasingly promotional as the quarter progressed, and he expects promotions to continue through the balance of 2026. That is a chairman’s forecast, and it should be treated as one.
Stack’s diagnosis is narrower than “weak demand.” He said Dick’s footwear business is “really very good” and placed the difficulty in the specialty channel, the mall business represented by Foot Locker, which depends more heavily on retro shoe launches. The industry, he argued, holds too much capacity in some legacy product and too little in the new styles consumers want, an imbalance that leaves retailers unable to stock what sells. Nike’s Mind sensory shoe, he said, drew a “terrific” response.
Academy’s Performance Skew And The Hyrox Bet
Academy Sports + Outdoors is the outlier on the evidence. Outdoor is its largest category at 30 percent of sales, and Fernández cited localization, shop-in-shops and assortment mix, Nike, Jordan Brand and Ariat among them, as differentiators. She flagged Ariat’s rise as workwear turned into lifestyle wear, plus a strong performance running mix from Adidas, Nike and Brooks including price points above $200.
Its second-quarter report showed gains in both profit and sales, meeting Wall Street expectations that it would outrun Dick’s and JD Sports. The reason is structural rather than tactical: Academy carries less footwear exposure, and what it sells leans toward performance, running and cleats, rather than the retro lifestyle lines now sitting in oversupply. The network totals 327 stores, with 11 more due to open in the third quarter of fiscal 2026.
On Wednesday, Academy said it would become Hyrox’s official North American partner, activating in Tampa, Dallas, Nashville, Atlanta and Houston ahead of title-sponsoring Hyrox Houston in 2027. This is an announced plan. Commercial terms were not disclosed in the material reviewed.
The Bigger Picture For Global Buyers
For readers outside the United States, the scope of this evidence is narrow. Nothing in the disclosed material covers African retail, sourcing, currency exposure or pricing; the record is three U.S. chains plus one analyst’s coverage. The transferable lesson is about inventory discipline, not about any single brand’s momentum.
The confirmed facts: Dick’s net income fell year on year, Academy posted profit and sales gains, JD grew running while retro basketball and football declined, and promotional intensity increased across parts of the market. The forecasts: an extended promotional cycle into 2026 and Nike holding its position at JD. The capacity imbalance between legacy and new silhouettes is neither confirmed nor forecast. It is a diagnosis offered by a retailer with an interest in the outcome.
For U.S. sporting goods retailers, the 2026 question is not whether shoppers will buy running shoes. It is whether supply can deliver the models they want before the promotional cycle takes the margin.
Frequently Asked Questions
Which three retailers does the report cover?
JD Sports, Dick’s Sporting Goods and Academy Sports + Outdoors, described in the source material as the big box outdoor specialists in the U.S. market.
What did Dick’s Sporting Goods report for the second quarter?
Net income of $315 million, or $3.50 a diluted share, down from $381 million, or $4.71 a share, a year earlier. Net sales rose 53.4 percent to $5.59 billion from $3.65 billion, below Wall Street’s $5.64 billion expectation. The company also lowered its yearly guidance for Foot Locker.
Why is Academy Sports + Outdoors described as the outlier?
According to Telsey Advisory Group analyst Cristina Fernández, Academy has less exposure to footwear than its peers and what it does sell skews toward performance styles such as running and cleats. Its second-quarter report showed gains in both profit and sales, meeting Wall Street expectations that it would outperform Dick’s and JD Sports.
Receive alerts for sporting goods retailers and more like it.
 Follow AFRILATEST on Google News
FIRST TIME REACTIONS:
Be the first to leave us a comment – U.S. Sporting Goods Retailers Stack Up: JD, Dick’s, Academy, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:

About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare Dominic
World News
US Hails Progress in Venezuela Transition Talks
Washington calls the first US flight to Caracas in seven years proof of progress in Venezuela transition talks. The election stage has not begun.
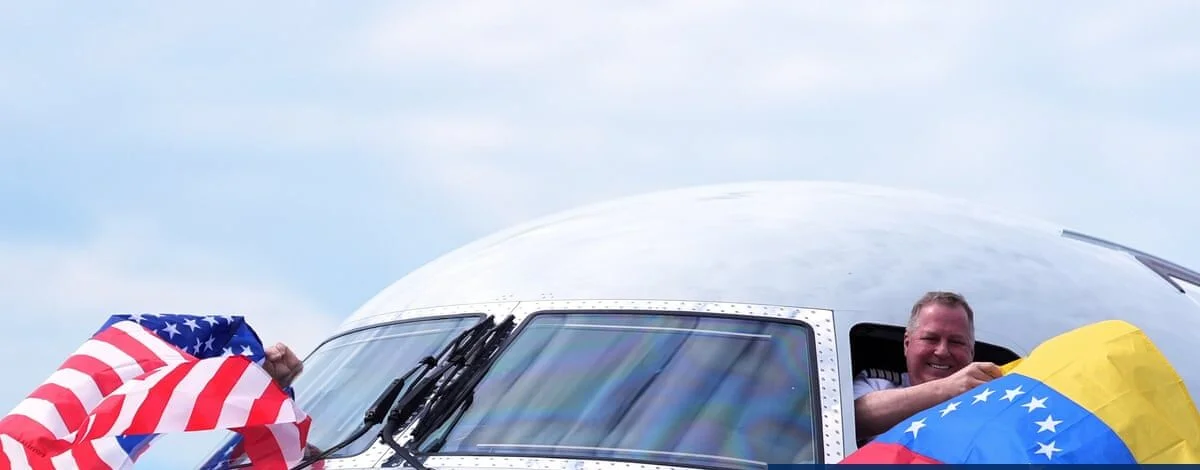
The first direct commercial flight between the United States and Venezuela in more than seven years landed in Caracas on Thursday, and Washington presented it as proof of momentum in the Venezuela transition talks — a process whose final stage, an actual transfer of power through elections, has not begun.
American Airlines Flight 3599 from Miami touched down at Simón Bolívar international airport at 1.15pm local time, The Guardian reported. The last US commercial flight left Caracas in March 2019, when relations collapsed during Donald Trump’s first term.
José Freig, the carrier’s vice-president of international operations, called it ‘a historic day’ before handing Venezuela’s transport minister, Jacqueline Faría, a model of one of his company’s planes. On the runway, Venezuelan passengers queued to board the return leg to Florida.
The US chargé d’affaires in Caracas, John Barrett, went further, calling the route ‘a direct result’ of a three-phase plan for post-Maduro Venezuela: stabilising the country, rebooting its economy, and ‘eventually securing a political transition back towards democracy. ‘We are only just getting started,’ he said.
What The Miami Flight Actually Confirms
The flight is evidence of phase two. Commercial ties are being rebuilt at speed, nearly four months after US special forces seized Nicolás Maduro in the capital and Delcy Rodríguez, his former vice-president, took power with Washington’s blessing.
It is not evidence that phase three has started. No election date has been published, and the official who would help organise one has publicly ruled it out for now. ‘It’s not time for elections,’ interior minister Diosdado Cabello said on the eve of the landing.
Faría framed the route in trade language: ‘This country wants to connect itself to the world.’ Félix Plasencia, Venezuela’s top diplomat in Washington, said it ‘should be the first one of many’.
Where The Venezuela Transition Talks Stand
The gap between the two governments’ language and the calendar is the story. Barrett describes a trajectory toward democracy. Rodríguez’s administration, according to the Guardian, appears in no rush to hold fresh elections.
John Feeley, a former US ambassador to Panama, described the arrangement bluntly as ‘a viceroyship’ — ‘a powerful king-like figure that extracts rent from overseas territories’, with Rodríguez ensuring ‘the king or the crown, or in this case Washington, gets its due’.
Feeley said he would not foreclose the possibility that the intervention ends up benefiting Venezuelans. He also said: ‘I’m pessimistic because of the track record of the Trump team and Donald Trump himself and his own attitudes towards democracy.’
Earlier in the year, Trump said he had held a ‘very good’ phone call with Rodríguez covering oil, minerals, trade and national security, writing on Truth Social that ‘we are making tremendous progress, as we help Venezuela stabilize and recover’, Kurdistan24 reported. No policy details accompanied that call.
Oil, Gold And What Has Not Been Published
The economic track has moved fastest and with the least transparency. Trump said Washington had struck a deal giving US interests control of more than 65 billion barrels of Venezuelan reserves — more than double American reserves, in his account, and enough to ‘substantially lower Gas Prices’. BBC News reported that Rodríguez put the term at 25 years, covering 17 fields, targeting 1.5 million barrels a day, with $100bn in investment and $209bn in taxes for Venezuela.
A US official told CBS News, the BBC’s US partner, that Washington would hold 55% of a joint venture with an ‘experienced private operator’, which was granted a 100-year concession. The text of the agreement has not been published.
David Goldwyn, president of Goldwyn Global Strategies, told Reuters there was ‘no precedent’ for the US government leasing Venezuelan oil fields and that it was ‘hard to see how this kind of arrangement would accelerate investment at any material scale’, citing political uncertainty, a weak power grid and limited export capacity.
Rachel Ziemba of the Center for a New American Security told the BBC the deal was ‘unlikely to have any material impact on global oil supplies in the next month or even the next year’. Venezuela’s crude is heavy and sour, costlier to refine than the light, sweet grades the US produces.
Britain, meanwhile, said in September it would upgrade its mission in Caracas to ambassador level, with Latin America minister Chris Elmore citing ‘an important opportunity’ for democracy and UK backing for ‘US-backed transition talks between the interim government and parts of the opposition’, Hürriyet Daily News reported. Venezuelan parties are separately negotiating the return of gold reserves frozen in London.
Why The Sequence Matters Beyond Caracas
The BBC noted the oil arrangement appears wider in scope than the US-led Coalition Provisional Authority’s control of Iraqi oil revenue after 2003. That comparison is the useful one: resource control can be arranged in weeks; legitimising a government takes institutions and a vote.
The sequence also explains why the Venezuela transition talks draw attention far beyond South America. Sanctions relief, diplomatic recognition and access to resources are moving in the same package, negotiated between two capitals, with allies such as Britain adjusting their posture afterwards. Governments that have spent years bargaining over sanctions and frozen assets will recognise the mechanics, even where the commodity differs.
The runway ceremony cost little and can be reversed. An electoral calendar cannot be improvised as easily.
What To Watch
Four checkpoints will separate progress from presentation. Whether the oil agreement’s full text is published. Whether the Chevron and Halliburton investment talks reported by the Wall Street Journal convert into signed contracts. Whether Cabello’s line on elections changes. And whether a British ambassador actually arrives in Caracas.
Until an electoral calendar appears, the Venezuela transition talks remain a framework with a flight schedule and no date for a vote.
Frequently Asked Questions
What did the US actually announce about the Venezuela transition talks?
The US chargé d’affaires in Caracas, John Barrett, said the first direct commercial flight in more than seven years was ‘a direct result’ of a three-phase plan: stabilising Venezuela, rebooting its economy, and eventually securing a political transition back towards democracy. He gave no timetable for the third phase, and no election date has been published.
Has Venezuela agreed to hold elections?
Not publicly. Interior minister Diosdado Cabello said on the eve of the flight that ‘it’s not time for elections’. The Guardian reported that Delcy Rodríguez’s administration appears in no rush to hold fresh elections. No electoral calendar has been announced in the reporting reviewed.
Why does the oil deal matter if the reserves are not being pumped yet?
Trump said the deal covers more than 65 billion barrels and would more than double US reserves. Analysts quoted by the BBC and Reuters said the text has not been published, there is no precedent for a US government lease of Venezuelan fields, and the arrangement is unlikely to affect global oil supplies in the next month or even the next year, given Venezuela’s heavy sour crude, weak grid and limited export capacity.
FIRST TIME REACTIONS:
Be the first to leave us a comment – US Hails Progress in Venezuela Transition Talks, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare DominicWorld News
Oura Sues Ultrahuman Again: Inside the Ring Pro Patent Fight
Oura sues Ultrahuman again over Ring Pro patents in a Texas federal court, threatening the Indian startup’s US market comeback.
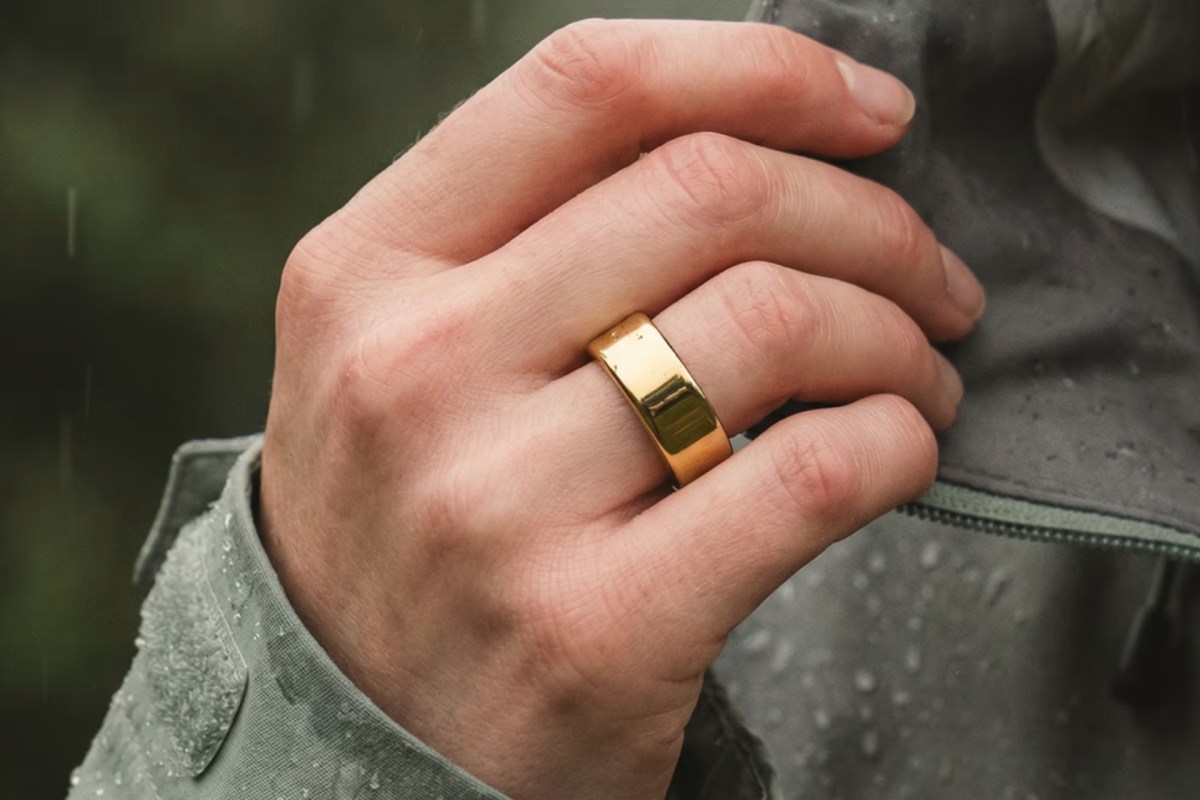
Mohit Kumar spent most of this year making an engineering argument. On Thursday, a federal court in Texas turned it into a legal one.
Oura filed a patent infringement complaint seeking to block US sales of Ultrahuman’s Ring Pro, the redesigned ring that carried Kumar’s Bengaluru company back into the American market only months after an import ban pushed it out. It is the second time Oura sues Ultrahuman in a US court, and the first aimed at the device the startup built specifically to get back in.
The complaint names Ultrahuman and SVTronics, a Plano, Texas electronics manufacturer that Oura says builds the Ring Pro under Ultrahuman’s direction and control. Oura is seeking monetary damages and a permanent injunction.
Kumar’s position is now double-edged. He runs a company valued at about $365 million after a $70 million raise in September that drew Qualcomm Ventures and Labcorp. He is also the defendant in a case that could remove his flagship product from the largest smart-ring market outside his home base.
Why Oura Sues Ultrahuman Again, Two Days After A New Patent
The timing is the detail worth pausing on. The complaint cites two Oura patents: D804,471, a design patent, and 12,769,363, which covers a ring architecture built around a curved battery, circuit board, magnets and sensors. The second was issued to Oura on 20 October, two days before the company filed suit.
Oura argues that the Customs decision which let the Ring Pro into the US covered only the patent at issue in the earlier dispute, not these two. “Ultrahuman has a history of copying Oura’s innovations, as demonstrated by the 2025 ITC ruling against the company,” an Oura spokesperson told TechCrunch. “Ultrahuman introduced a redesigned ring but failed to address continued infringement of Oura’s patents.”
Ultrahuman did not respond to TechCrunch’s request for comment. The company has not publicly answered the new filing.
From The Ring Air Ban To Ring Pro Clearance
The dispute dates to 2023, when Oura first sued Ultrahuman over the Ring Air. Oura then brought a case at the US International Trade Commission in 2024 and won a ruling in August 2025, which blocked imports of the Ring Air and its components. Wired reported that the ITC finding rested on a hardware patent covering layered internal and external components, a description broad enough to reach most rings on the market.
Ultrahuman’s answer was a redesign. It unveiled the Ring Pro in February, began selling globally, and in March received a favourable ruling from US Customs and Border Protection. CNET reported the clearance opened preorders at $349 for the first 1,000 buyers and $399 afterwards, with a charging case at $100 or $479 as a bundle. The ring claims 15 days of battery life, 45 with the case, and unlike Oura charges no subscription for core sleep, recovery and stress data.
“We’re delighted to be back in the US with Ring Pro,” Kumar said at the time. “Ultrahuman is an engineering company, and we believe that the company that leads with engineering will ultimately win in this space.”
The Delhi Counterclaim That Did Not Survive
Kumar’s company has fought back in court before, without success. In 2025 Ultrahuman filed its own infringement suit against Oura in the Delhi High Court, alleging Oura copied women’s health features, circadian tools and its glucose monitoring platform. The court dismissed the case on 1 September 2025, with Justice Manmeet Pritam Singh Arora presiding, Mashable reported. Ultrahuman said it would clarify and re-file.
Oura called that action meritless at the time and described the ITC outcome as decisive. Ultrahuman’s public case has rested on patent age rather than patent absence. “This isn’t a dispute over years of secret R&D,” the company wrote in a blog post about the litigation. “It’s about a very recent patent purchase now being wielded to limit the choices ring-wearers like you have.”
The pattern is now established: Oura sues Ultrahuman in US courts, and Ultrahuman counters where jurisdiction allows.
What The Ring Fight Means For Buyers Outside America
IDC expects global smart-ring shipments to rise 12.8% this year to 4.9 million units and reach about 6.3 million by 2030. Neither company breaks out Africa figures in the filings and statements described here, and that gap matters. Distributors and buyers on the continent sit at the end of an import chain that reacts to US legal outcomes: a permanent injunction would not simply shift American pricing, it would reshape which devices reach secondary markets and at what cost.
The commercial asymmetry is stark. Research firm Omnia put Oura at roughly 74% of the smart ring market last November and Ultrahuman at about 9%. Oura has converted several rivals into licensees, with RingConn and Circular agreeing to pay royalties, while cases against Samsung and Zepp Health continue. It has also shelved a $2.2 billion IPO, citing market “uncertainty,” just weeks before filing this complaint.
That context cuts both ways. A company preparing to return to public markets has reason to defend its patent portfolio loudly. A challenger that just raised $70 million and is co-developing a Qualcomm-powered ring has reason to keep selling.
Kumar’s wager, that engineering beats litigation, now waits on a judge in Texas. Whether Oura sues Ultrahuman again after this complaint, or settles into another royalty arrangement, will say more about the structure of the smart-ring market than any product launch. For buyers in Lagos, Nairobi or Johannesburg, the practical question is narrower: which ring, and at what price, survives the injunction stage.
Frequently Asked Questions
What patents does Oura say the Ultrahuman Ring Pro infringes?
Oura’s complaint cites two: design patent D804,471 and patent 12,769,363, which covers a ring design using a curved battery, circuit board, magnets and sensors. The second patent was issued to Oura on 20 October, two days before the suit was filed.
Why is SVTronics named in the lawsuit?
Oura alleges that SVTronics, a Plano, Texas electronics manufacturer, builds the Ring Pro under Ultrahuman’s direction and control, and that both companies infringe its patents through manufacture, importation and sale of the device in the US.
How did Ultrahuman return to the US market before this suit?
After the ITC import ban on its Ring Air, Ultrahuman redesigned the hardware as the Ring Pro, launched it in February, and received a favourable ruling from US Customs and Border Protection in March, which cleared it for US preorders.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Oura Sues Ultrahuman Again: Inside the Ring Pro Patent Fight, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare DominicWorld News
Lunai Bioworks Nasdaq Delisting Ends A Bid-Price Illusion
Lunai Bioworks Nasdaq delisting: LNAI exits on Nov 12 with a $9.02M equity deficit, two reverse splits and no OTC quoting plan.
The Lunai Bioworks Nasdaq delisting is no longer a risk disclosure. It is a calendar entry. On 21 October 2026 the Sacramento-based company received a letter from the Listing Qualifications Department of Nasdaq stating that it no longer complies with Listing Rule 5550(b)(1), which requires minimum stockholders’ equity of $2,500,000. Trading in LNAI is expected to be suspended at the opening of business on 30 October 2026. A Form 25 is due on or about 2 November 2026, with the delisting effective on or about 12 November 2026, followed by a Form 15 intended to suspend SEC reporting obligations.
The company did not contest the finding. Its board voted on 22 October 2026 to withdraw the common stock from Nasdaq voluntarily under Rule 12d2-2(c) of the Securities Exchange Act of 1934. The reason given was the staff determination and the company’s financial condition, with the board concluding that the cost of continued listing and SEC reporting is no longer justified.
Why The Lunai Bioworks Nasdaq Delisting Was Never A Bid-Price Story
The failure was on equity, not price. Lunai’s Annual Report on Form 10-K for the fiscal year ended 30 June 2026 reported a stockholders’ deficit of $(9,024,946). Against a $2.5 million minimum, that is a shortfall of roughly $11.5 million by simple arithmetic. The release also states the company does not meet Nasdaq’s alternative tests based on market value of listed securities or net income.
That detail matters because the public record around this ticker over the past year pointed the other way. In a separate SEC filing, Lunai disclosed that Nasdaq had confirmed it regained compliance with the exchange’s $1 minimum bid price requirement, following an initial notice on 20 April and extension letters on 12 May. Stocktwits reported that shares rose more than 100% in pre-market trading on a Wednesday after that disclosure, with retail sentiment flipping to “extremely bullish” and message volume up sharply.
Two Reverse Splits Did Not Build Equity
That bid-price compliance was manufactured, not earned. Shareholders at a special meeting on 8 May approved a reverse split within a 1-for-3 to 1-for-30 range, and the board settled on 1-for-8, effective 22 May. Outstanding shares fell from about 36.3 million to about 4.5 million. The company had already executed a 1-for-10 reverse split on 30 September 2025.
Stacked, those two actions mean an investor holding 80 shares before September 2025 would hold one share after May 2026, absent other issuance. A reverse split raises the quoted price arithmetically while leaving market capitalisation and stockholders’ equity unchanged. It cannot close a $9 million deficit. Nasdaq also placed Lunai under a one-year monitoring period, under which a renewed bid-price failure would not qualify for a standard compliance plan or extension.
Then came the procedural trap. Because Lunai was subject to a mandatory Hearings Panel Monitor under Nasdaq Listing Rule 5815(d)(4)(B), the release states that Nasdaq staff determined to delist rather than route the company through a fresh cure period. Lunai declined to request a hearing. The release does not itemise the listing and reporting costs the board weighed, and it does not give a figure for them.
An Exit With No Secondary Venue
What follows the delisting is unusually bare. Lunai says it does not intend to arrange for quotation of its common stock on any over-the-counter market, and cannot assure that any trading market will exist once Nasdaq trading stops. Its SEC reporting obligations continue unless and until they are terminated or suspended under SEC rules, and the company describes its own filings as forward-looking intentions subject to Nasdaq and SEC procedures.
This is not an isolated pattern. In the same month, SITE Centers Corp. (NYSE: SITC), a self-managed REIT based in Beachwood, Ohio, announced its intention to notify the New York Stock Exchange of a voluntary delisting, anticipating that a special distribution declared on 15 October 2026 would push its share price and market capitalisation toward levels triggering involuntary removal. Per the SITE Centers announcement, the delisting is expected before trading begins on 4 December 2026, and no listing, registration or Rule 15c2-11 quotation arrangement has been made elsewhere.
Set the two side by side and the contrast is instructive. One company is leaving to distribute capital; the other is leaving with negative equity. The mechanics are identical: a Form 25, an exchange exit, and no regulated venue for holders afterwards. The Lunai Bioworks press release makes no mention of its research programmes, headcount, financing plans or operations, so the effect of the exit on the underlying business cannot be assessed from the primary document.
What African And Global Issuers Should Read In It
For founders and investors in Africa and other emerging markets who treat a US exchange listing as a badge of maturity, the case separates two things that get conflated in headlines: listing compliance and financial health. A company can pass the price test, issue a triumphant press release about compliance, and fail the equity test months later without any change in its underlying position.
It also clarifies who carries the residual risk. Under the announced plan, the last regulated price becomes the last price. Holders using mobile brokerage apps in Lagos, Nairobi or London face the same outcome as institutional shareholders, with no OTC quotation to exit through, and no assurance from the company that any market will exist.
All of this is confirmed in the company’s own 22 October 2026 statement, corroborated by its earlier bid-price filing and by the parallel SITE Centers exit. What remains allegation or forecast: nothing in the record suggests misconduct, and none should be inferred. What remains unknown is the company’s post-delisting strategy, which the release does not address.
The big picture is a reminder that the Nasdaq floor is a compliance floor, not a solvency floor. The Lunai Bioworks Nasdaq delisting was scheduled within nine days of the Nasdaq letter, executed by board vote, and leaves no backstop market behind it. Read the equity line of a 10-K before the pre-market headline.
Frequently Asked Questions
Why is Lunai Bioworks delisting from Nasdaq?
Nasdaq’s Listing Qualifications Department notified the company on 21 October 2026 that it no longer complies with Listing Rule 5550(b)(1), which requires minimum stockholders’ equity of $2,500,000. Lunai reported a stockholders’ deficit of $(9,024,946) for the fiscal year ended 30 June 2026 and did not meet alternative market value or net income standards. Because the company was under a mandatory Hearings Panel Monitor, Nasdaq staff determined to delist.
When will LNAI stop trading on Nasdaq?
Trading is expected to be suspended at the opening of business on 30 October 2026. The company intends to file a Form 25 on or about 2 November 2026, with the delisting effective on or about 12 November 2026. It then intends to file a Form 15 to suspend SEC reporting obligations, to the extent it is eligible.
Will Lunai Bioworks shares trade over the counter after delisting?
No. The company stated it does not intend to arrange for quotation of its common stock on any over-the-counter market and cannot assure that any trading market will exist after Nasdaq trading is suspended. A comparable October 2026 announcement from SITE Centers Corp. also confirmed no alternative listing or Rule 15c2-11 quotation arrangement.
Did reverse stock splits cause the delisting?
They did not cause it, and they could not have prevented it. Lunai executed a 1-for-10 reverse split on 30 September 2025 and a 1-for-8 split effective 22 May 2026, reducing outstanding shares from roughly 36.3 million to about 4.5 million. A reverse split lifts the quoted share price arithmetically but leaves stockholders’ equity unchanged, so it addresses the $1 bid price rule rather than the $2.5 million equity requirement.
FIRST TIME REACTIONS:
Be the first to leave us a comment – Lunai Bioworks Nasdaq Delisting Ends A Bid-Price Illusion, down the comment section.
JOIN US ON OUR SOCIAL MEDIA:
About Clare Dominic
Clare Dominic is the Editor at AfriLatest. With a background in journalism and a passion for storytelling, she oversees the editorial process to ensure content is accurate, engaging, and relevant. Clare works closely with contributors to maintain the highest standards of journalistic integrity across all news, sports, and lifestyle coverage.
View all articles by Clare Dominic-

 Startups4 weeks ago
What a Successful Dangote Refinery IPO Really Says
-
Health and Fitness1 week ago
Curly Hair Hydration: 5 Proven Steps That Actually Work
-
Trending Entertainment News2 weeks ago
Taylor Swift Joins Beatles as Only Acts With 100 Weeks at No. 1
-
World News4 weeks ago
Carney Calls U.S. Tariffs a Miscalculation as Canada Retaliates
-
Tech & Gadgets2 weeks ago
Apple Watch and AirPods Fall Deals: Save $120 Today
-
Football4 weeks ago
Mexico vs Colombia 2026: Márquez Debut Ends in Defeat
-
University Admissions4 weeks ago
UNILAG 2026/2027 Admission: Direct Entry & Post-UTME Guide
-
Fintech4 weeks ago
OPay No Dey Comot Nigeria: How to Verify Fintech News